Key takeaways:
- Climate and nature are secular macro forces, not ethical add-ons. They sit alongside geopolitics, demographics, and technology as structural forces shaping long-term investment risk and opportunity, and are already visible in company cash flows.
- The science is non-linear, and most financial models assume linear change. Carbon budgets, tipping points, and planetary boundaries behave in a way backward-looking models systematically underestimate.
- Nature is the next frontier of materiality. Biodiversity underpins a vast share of economic activity yet remains difficult to price. It creates hidden risk and, for prepared investors, genuine opportunity.
The investment challenge
For years, many investors treated climate and biodiversity as ethical considerations sitting outside of financial models — as a values overlay rather than a valuation input. Today that view is increasingly hard to sustain. The scientific picture is now clearer and more urgent as the physical impacts become harder to ignore and the remaining room for delay narrows. At the same time, the political environment is less predictable. Recent geopolitical events have reinforced the strategic case for renewable energy and energy independence, while also prompting some countries to increase their reliance on fossil fuels to meet near-term energy-security needs. For investors, the result is not a simpler transition, but a more complex one.
Like geopolitics, demographics, and technological change, climate and nature are reshaping markets. But because the underlying science is less familiar to most investors, its financial implications are more easily overlooked and, at times, mispriced.
A core difficulty is that models used to value companies are largely built around linear, incremental change. Climate and nature risks rarely behave so uniformly. Some impacts are already visible today, but their most significant effects build over time and can accelerate unexpectedly. Emissions accumulate; damage compounds; and beyond certain points, change becomes self-reinforcing and irreversible on any human – or investment – timescale.
Three concepts are particularly useful in understanding how climate and nature risks evolve over time. The carbon budget sets a finite quantity of CO₂ that can be emitted before key warming limits are passed. At current global emissions of roughly 59 gigatonnes of CO₂ equivalent a year, the budget associated with 1.5°C would be exhausted in around seven years, not decades. Planetary boundaries identify nine systems that keep the Earth stable, from freshwater use to biodiversity; seven have now been pushed beyond their safe operating limits. Tipping points are thresholds beyond which natural systems can shift abruptly and, in some cases, irreversibly into a new state. While the timing is debated, scientists warn that several major systems, including ice sheets and coral reefs, may be nearing them.
For investors, these are uncomfortable ideas because they challenge the assumption that risks emerge gradually and can be extrapolated from the past. Together they suggest that environmental change may occur faster, and with greater force, than conventional models imply.
Exhibit 1: Tipping points – when change becomes irreversible
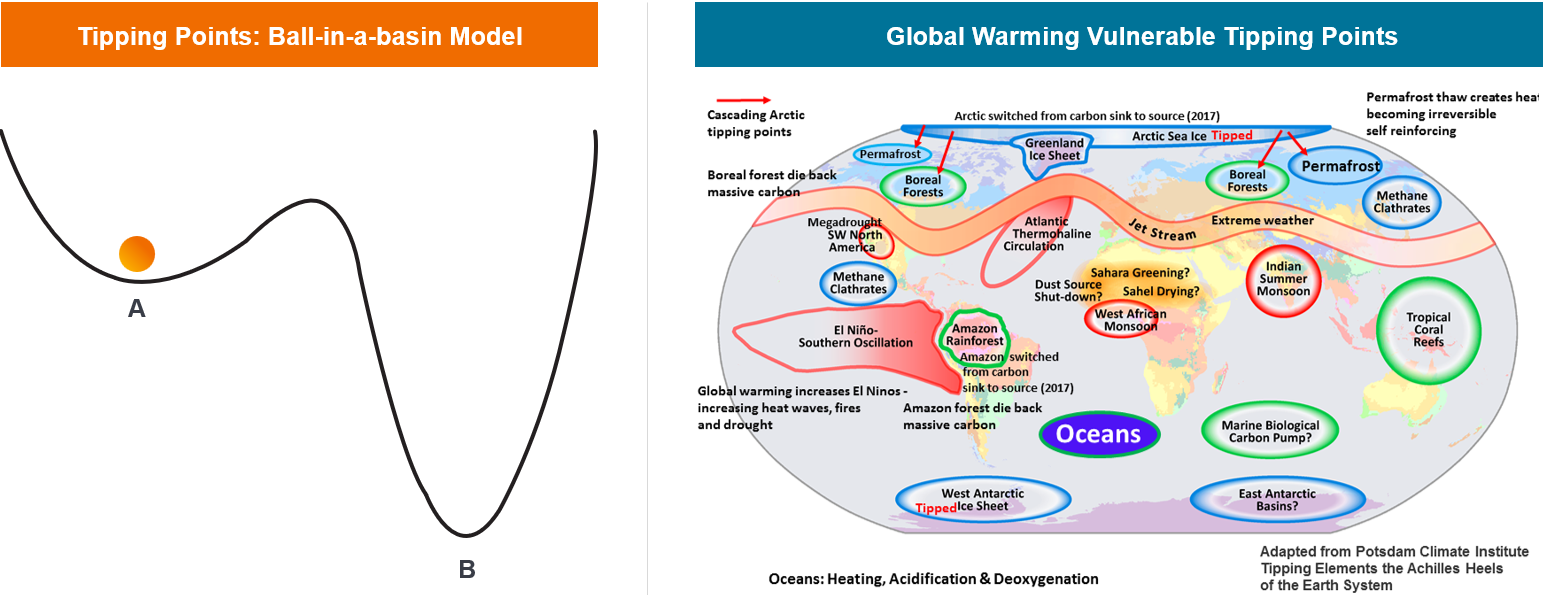
The ball-and-basin model shows why change may not be gradual: a system absorbs pressure until it is displaced past the rim, at which point it settles into a different state. The map identifies the Earth systems considered most vulnerable. Source: Hodgson, Systemic risk and climate tipping points, Thinking Ahead Institute; tipping elements adapted from Potsdam Climate Institute.
How we – and Berkeley – think about it
The central argument is simple: climate and nature science matters to investors when it changes how they assess risk, value companies, or allocate capital. Through our partnership with UC Berkeley, we can connect scientific insight with the practical implications for investment decision-making.
That partnership lens is particularly valuable when considering the non-linear nature of environmental risk. As Berkeley’s Dara O’Rourke (Associate Professor, Dept of Environmental Science, Policy & Management, Rausser College of Natural Resources) puts it: “The market’s mistake isn’t denying climate risk — it’s assuming it will arrive gradually. Ecosystems can look stable right up until they aren’t.” The investment implication follows directly: if risk is non-linear but priced as if it were, the market may be systematically underestimating the timing and potential scale of change, and timing is often where active managers can add value.
Biodiversity is where this is starkest. Nature is harder to measure than carbon, has no single price signal, and is intensely local, so markets largely ignore it. Yet the economic dependence is enormous. Berkeley’s Matthew Potts (Professor; S.J. Hall Chair in Forest Economics, Dept of Environmental Science, Policy & Management, Rausser College of Natural Resources) highlights the concept of option value: the Gila monster, a desert lizard, is proven to be the biological source of the GLP-1 drug, now underpinning a market worth roughly $500 billion. Had the species been lost before its discovery, that option would simply never have existed. As Potts says: “Our wealth of biological diversity represents an amazing library of biological experimentation. Today we risk burning that library down without having read the books.”
In practice
So, what does this mean in practice for investors? Climate and nature considerations need to be incorporated into existing investment models, rather than treated as a separate process. Financial analysis should extend beyond a company’s own operations and through its supply chain. Biodiversity risks often emerge in places that are far removed from where a company generates its revenues, making them easy to overlook in traditional financial analysis. And because impacts are cumulative and can accelerate, scenario analysis often becomes more informative than historical averages alone.
Exhibit 2: Global trade transmits local biodiversity loss through supply chains
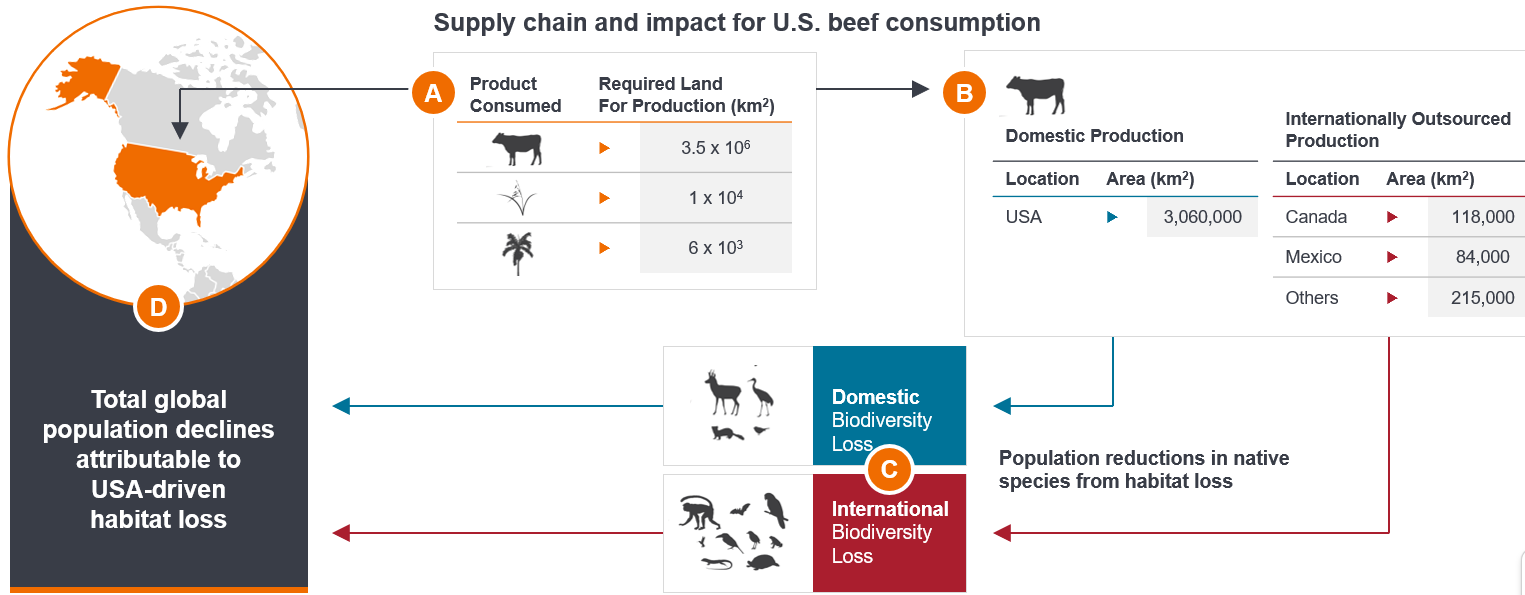
Biodiversity loss driven by consumption in one country often occurs elsewhere. The chart splits the footprint of a single consumption category between impacts arising domestically and those occurring in producing countries overseas. Source: Nature, 2025
For active investors, the goal is not simply to understand these risks, but to identify where they are not yet fully reflected in market prices:
Investment outcomes are ultimately driven by how companies create and preserve value. Climate and nature increasingly influence both. The opportunity for investors is identifying where those effects are not yet fully understood, or fully priced.
– Hamish Chamberlayne, Head of Global Sustainable Equities at Janus Henderson
What’s next
Seeing the science clearly is only the first step. The harder question is how to translate carbon budgets, tipping points, and nature loss into information investors can actually use. In the next article in this series, we explore how data, scenarios, and models can help investors assess the implications of climate and nature risks for companies and portfolios, including where their limitations lie, and where investment judgement still matters.
Asset allocation: The allocation of a portfolio between different asset classes, sectors, geographical regions, or types of security to meet specific objectives of risk, performance, or time horizon
Biodiversity: The variety of living organisms, ecosystems, and genetic resources on Earth. Biodiversity underpins economic activity by supporting food systems, clean water, medicine, and many industrial supply chains.
Capital: When referring to a portfolio, the capital reflects the net asset value of a fund. More broadly, it can be used to refer to the financial value of an amount invested in a company or an investment portfolio.
Decarbonisation: The process of reducing the amount of carbon, mainly carbon dioxide (CO₂), sent into the atmosphere, to combat global warming and climate change.
Carbon budget: The cumulative amount of carbon dioxide that can be emitted while still maintaining a reasonable chance of limiting global warming to a specified temperature threshold.
Cash flow: The net balance of cash that moves in and out of a company. Positive cash flow shows more money is moving in than out, while negative cash flow means more money is moving out than into the company.
Environmental, Social, and Governance (ESG): Environmental, Social and Governance (ESG) factors relate to the quality and functioning of the natural environment, the rights, well-being and interests of people and communities, and the governance of companies and their stakeholders.
ESG integration: The consideration of financially-material ESG risks and opportunities throughout the investment process.
Exposure: The amount invested in an asset or market, and could potentially lose, should an investment fail. It is another way of describing financial risk.
Fundamental analysis: The analysis of information that contributes to the valuation of a security, such as a company’s earnings or the evaluation of its management team, as well as wider economic factors. This contrasts with technical analysis, which is centred on idiosyncrasies within financial markets, such as detecting seasonal patterns.
Net zero: A state in which greenhouse gases, such as carbon dioxide (CO₂), being released into the atmosphere are balanced by their removal from the atmosphere.
Option: A contract between two parties that gives one of them the right to buy or the right to sell a specific asset, such as shares, bonds, or currencies at a date and price that is fixed when the option is bought.
Portfolio: A grouping of financial assets such as equities, bonds, commodities, properties, or cash. Also often called a fund.
Planetary boundaries: A scientific framework that identifies key Earth system processes and the environmental limits within which humanity can safely operate.
Risk / Risk taking: The acceptance of greater risk in exchange for potentially higher returns. This can apply to both individual investors and companies. An assessment of investors’ attitude to risk forms a fundamental part of identifying a suitable investment strategy for their objectives.
Scenario analysis: A tool used to assess how different future outcomes or assumptions may affect companies, portfolios, or investment decisions. It is particularly useful when risks may be non-linear or difficult to estimate from historical data alone.
Systemic risk: The risk of a critical or harmful change in the financial system as a whole which would affect all markets and asset classes.
Tipping points: Critical thresholds beyond which natural or climate systems can shift abruptly into a different state, often with potentially irreversible consequences.
Valuation metrics: Metrics used to gauge a company’s performance, financial health, and expectations for future earnings.
Volatility: The rate and extent at which the price of a portfolio, security, or index, moves up and down. If the price swings up and down with large movements, it has high volatility. If the price moves more slowly and to a lesser extent, it has lower volatility. The higher the volatility, the higher the risk of the investment.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.