Key takeaways:
- Demand remains broad and robust: Expanding cloud backlogs provide greater visibility into contracted demand as AI adoption spreads across organisations.
- Capex allocation takes time to move from land, build, equip, power to ramping capacity and revenue generation. Mid-term elections may impact the pace and location of deployment in out years.
- Contrasting business models, financing needs and pathways to AI monetisation strengthen the case for active stock selection.
The latest earnings reports from the ‘Magnificent 4 hyperscalers’ prompted some of the weakest market reactions that we have seen in recent years. The performance between Meta, Amazon, Alphabet, and Microsoft diverged significantly. This upholds our team’s long-held mantra that the Mag 7 should not be treated as a monolith.
Here we identify five core themes and takeaways from the results and some of the associated key debates around the four hyperscalers.
1. AI demand remains strong and broad. Cloud backlogs provide stronger visibility into contracted demand
The third quarter of 2026 saw the fastest growth in revenues for AWS (Amazon Web Services) in five years. Microsoft’s Azure cloud business grew 48%, while Google Cloud’s business more than doubled (+103%). Token growth has continued to rise parabolically with enterprises and consumers using both frontier and open-weight models managed on these platforms. That growth meant a tripling in backlog for Amazon and Alphabet this year, now sitting at over US$1.7 trillion combined for Alphabet, Amazon and Microsoft. This represents contracted revenues that will be recognised over the next one to six years for these companies.
Microsoft guided further Azure revenue growth of 49-50% for the fiscal second quarter (ending December 2026), while Amazon was able to guide revenue growth for AWS, not only for 2027 but also for 2028. Putting a floor (not a ceiling) on its AWS revenue growth of 40% offers strong visibility. It was not only the strength but the breadth of demand that provides visibility. This demand is no longer concentrated around a limited number of AI frontier labs like OpenAI and Anthropic. It is being driven by a wide range of governments and enterprises across the broader economy that are scaling their use of AI from training into inferencing workloads. So, unlike the dot.com era, customer demand is not coming from IT capex budgets alone. It is also from operating expenditure, R&D, marketing: the entire knowledge work that is being disrupted – on paper, a more than US $30 trillion opportunity.
2. Focus on free cash flow inflection and second derivative infrastructure read through. Patience required – it is ‘when’, not ‘if’
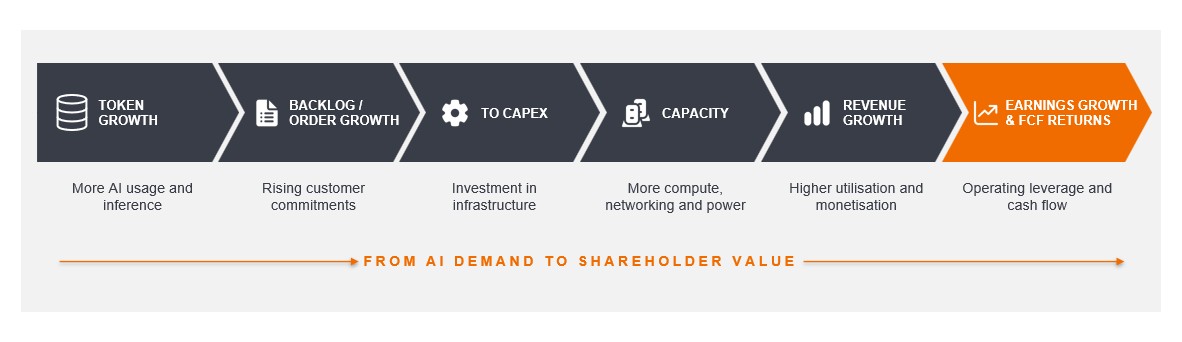
Capital expenditure (capex) for the recent quarter exceeded operating cash flow for Amazon, Alphabet and Meta, with deteriorating free cash flow (FCF) overhanging the multiple of earnings that investors are willing to pay. It is supply and not demand that is dictating the pace of revenue growth at present. Total backlog has more or less tripled this year, with all three companies indicating that capex would increase “significantly”, “meaningfully”, “aggressively” in 2027 as they spend to provide capacity. There is a time lag between capex turning into additional capacity due to permitting, power and deployment that takes time to first token, which then converts to revenue growth.
The recent mid-term elections and wins for the Democrats in key data centre-building states like Texas, Georgia and Ohio have increased concerns that stricter environmental and permitting rules might slow the pace of capacity addition. A slowdown in the pace of capex build could in fact bring forward the point of FCF inflection for those hyperscalers that have the largest embedded capacity base at present – namely Amazon and Microsoft. We believe regulatory change may affect the pace but not the magnitude of spend over the next three years. The amount of capex spend will continue to be driven by the growth in demand and AI usage.
The trends in operating margins at Alphabet, Amazon and Microsoft’s cloud divisions continue to bode well for the profitability derived from revenue generating capacity – as we see ever greater progress along the spectrum from AI demand to shareholder value.
How AI infrastructure investment could translate into revenue and earnings
Source: Janus Henderson Investors. For illustrative purposes only.
3. Heightened focus on compute efficiency through vertical integration, silicon and higher utilisation
Meta’s management noted compute cost-efficiency for its integrated agentic personal AI assistant (Muse) was expected to improve more than tenfold over the next year. This was based on better utilisation of peak and spare capacity, deployment of smaller more efficient models, inference optimisation and higher GPU utilisation. Meta also noted that AI-driven internal efficiency improvements from software output per engineer is expected to more than double year-on-year.
The search for efficiency has benefited the hyperscalers in their role of managing and orchestrating model use, but also the increasing demand for their own silicon (chips). Amazon noted that usage of Bedrock, which enables faster build and scale of generative AI applications, grew 17x year-on-year, making it the fastest-growing multi-billion-dollar service in AWS history. Meanwhile, Microsoft highlighted broader model adoption on Foundry, as customers increasingly build multi-model, agentic AI solutions.
All of the hyperscalers are increasingly focused on custom silicon to complement NVIDIA GPUs, creating more vertically integrated, heterogeneous AI infrastructure platforms. For Alphabet, and increasingly Amazon, selling proprietary chips to external customers is emerging as a business in its own right. However, the business models and margin structures have yet to be fully disclosed. This build-out weighs on short-term FCF as inventories increase, but should drive strong growth and profitability as sales ramp.
Encouragingly, Alphabet and Amazon noted that AI compute remains highly utilised; Amazon AI accelerators are being installed at a rate of one every 14 seconds. Typically, as quickly as Amazon installs that capacity, customers are consuming it and turning it into revenue.
4. Funding capex growth – will external financing needs continue?
Funding the build out of AI infrastructure is a key focus given the issuance of debt and equity from these mega caps has increased significantly in 2026. As well as heavy debt issuance, Alphabet and Meta have now tapped equity markets for financing. Alphabet did so earlier this year but still has US$25 billion of at-the-market offering capacity, while Meta raised US$35 billion post results, announcing a new C share class to raise a further US$60bn in late January.
Meta likely continues to tap shareholders for funding given the extent of its contractual commitments beyond capex (more than US$300 billion of long-duration infrastructure, energy, content and purchase obligations), while unlike the other hyperscalers it has no existing cloud business with backlog visibility.
Despite this overhang for equity shareholders, the level of dilution has been modest, given the strength of balance sheets, cash generation and multi-year demand visibility, meaning funding needs are unlikely to constrain the mega-cap hyperscalers. However, the size of capital raises, combined with a large IPO pipeline, could create a challenge for neoclouds and others seeking financing as investors digest overall supply. Over time we would expect these companies to fulfill their capacity needs with their internal resources and ultimately pull back from expensive third-party agreements that have been signed for short-term needs.
5. Impact of AI on core businesses
Aggregate Mag 4 hyperscaler growth slowed from 22% last quarter to 18% this quarter. Although the companies expect this to pick up in the fourth quarter of 2026, we think investors should be mindful of seasonality and some idiosyncratic issues impacting the latest quarter’s earnings.
Alphabet
Investors were concerned with search revenue growth slowing to 12% and the company’s indication of further slowing, given tougher comparisons from a year ago. We think it is important to differentiate the slowdown this quarter to that of early 2025, when the market was concerned about cannibalisation of search from Chat GPT. This quarter, Alphabet saw record growth in the number of search queries, so the slowdown was driven not by volume but by monetisation.
This is something Alphabet has historically demonstrated it can solve, given its ad tech and industry-leading return on ad spend. We see a parallel with Meta’s Reels monetisation journey. Alphabet is building the best user experience, and engagement, ad placement, optimisation and more competitive advertising auctions could progressively close the monetisation gap as they scale high-quality ads in AI Overviews and AI Mode. Alphabet also alluded to evolving its Gemini app into a more holistic agent while continuing to build out the infrastructure needed for AI agents to interact securely with shopping and payment systems. This is likely to take a number of quarters to become evident.
Amazon
The ecommerce and advertising business slowed during the quarter but this was expected given Amazon had previously flagged the move of Prime Day into the second quarter from the third. Amazon’s online fresh grocery business is growing rapidly – especially in unit terms – around 3x faster than the broader store. The company continues to reduce its cost to serve, which is driving higher long-term profit margins. The company continues to outgrow the majority of its peers, but trades at a significantly lower valuation than Wal-Mart or Costco, for example. The flywheel effect of Amazon’s Prime membership, where more members, and more people watching and buying, attracts more sellers and advertisers, benefiting the platform.
Meta
Advertising is one of the first clear beneficiaries of AI; Meta stood out for its AI spend, demonstrating sustained growth in its core business for a second consecutive year, while most other digital platforms decelerated. Management expects to see continued strong growth (>20% into 2027), while AI continues to have a strong positive impact on engagement and advertising monetisation. Over the quarter, Meta also launched Muse, and laid out a monetisation path that could tap into search advertising revenues. We also saw the launch of Meta Enterprise, selling AI tools, models, and infrastructure directly to organisations and developers. While the advertising core business is strong, there is a lack of certainty and visibility in building out these non-core businesses where they face tough competition.
Microsoft
The company’s business covers a broad range of enterprise and consumer markets, with growth rates varying across these areas. The cloud business, Azure, and M365 (the cloud-based subscription service that combines productivity applications like Word, Excel, Outlook etc, collaboration tools, device management, and security features), remain as key drivers of the business. But other areas have shown slower growth rates, depending on product cycles and business maturity. MS Dynamics 365, its enterprise resource planning (ERP) and customer relationship management (CRM) applications, and LinkedIn, reported moderating bookings and remain a small part of the overall business. Importantly, Microsoft remained positive in FCF terms, a benefit of having such a diversified business.
Conclusion
We remain positive about the outlook for the technology sector as investment in AI infrastructure continues to scale, platforms emerge and applications develop. Hyperscaler capex continues to expand to meet strong token demand. AI monetisation appears to be progressing faster than in previous technology cycles, and demand visibility across the physical AI infrastructure layer now appears to extend into 2028 and beyond. In our view, this remains an earnings-driven cycle rather than one reliant on multiple expansion.
IMPORTANT INFORMATION
References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
There is no guarantee that past trends will continue, or forecasts will be realised.
All company information sourced from earnings results releases and call transcripts, unless otherwise specified. Amazon Investor Relations; Q3 2026 earnings results; 29 October 2026; Google Blog; Q3 2026 earnings call28 October 2026; Microsoft Investor Relations; Earnings Release FY27 Q1; 28 October 2026; Meta Q3 2026 earnings call; 21 October 2026.
—–
Agentic AI: AI systems capable of planning and completing multistep tasks, often by interacting with external software, data or services with limited human intervention.
At-the-market (ATM) offering: Allows a listed company to issue and sell new shares gradually into the public market at prevailing market prices, rather than raising a large amount through a single underwritten equity offering.
Backlog (Remaining Performance Obligations or RPO): The value of contracted revenue that a company has not yet recognised because the services have not yet been delivered. A growing backlog can provide greater visibility into future revenues.
Capital expenditure (capex): Money invested to acquire or upgrade fixed assets such as buildings, machinery, equipment, vehicles, technology in order to maintain or improve operations and foster future growth.
Capital structure: The amount of debt and/or equity used by a company to fund its operations and finance its assets.
Cloud computing: The delivery of computing services, including data storage, processing power and software, over the internet rather than through local computers or servers.
Custom silicon: Computer chips designed for a specific purpose rather than general use. Companies such as Amazon and Alphabet develop custom AI chips to improve performance and reduce costs.
Enterprise seat expansion: Refers to the traditional software growth model where an organization scales its deployment by purchasing more user licenses (“seats”) as adoption of workplace AI tools (such as enterprise assistants or LLMs) grows across teams and departments.
Free Cash Flow (FCF): Cash that a company generates after allowing for day-to-day running expenses and capital expenditure. It can then use the cash to make purchases, pay dividends, or reduce debt.
Frontier model: A highly advanced AI model that performs at or near the leading edge of current artificial intelligence capabilities.
Generative AI: Artificial intelligence capable of creating new content, including text, images, audio and software code, based on patterns learned from large datasets.
GPU (graphics processing unit): A type of computer processor designed to perform many calculations simultaneously. GPUs are widely used to provide the computing power required to train and run AI models.
Hyperscaler: A large cloud computing company that operates vast data-centre networks and provides computing infrastructure at global scale. Examples include Amazon Web Services (AWS), Microsoft Azure and Google Cloud.
Inference: The process of using a trained AI model to generate outputs, such as answering questions, producing images or making predictions.
Magnificent Seven (Mag 7): A group of large US technology-related companies comprising Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla.
Mega cap: A designation for the largest companies in terms of market capitalisation. In the US, companies with a valuation above US$200 billion are generally considered mega caps.
Monetisation: The process of generating revenue from a product, service or investment.
Open weight model: Provides the final trained parameters and model architecture but typically omits the full training dataset or complete data collection methodology due to legal, cost, or privacy constraints.
Operating cash flow: The cash generated by a company’s normal business operations.
Operating margin: A measure of profitability showing the proportion of revenue remaining after operating expenses have been deducted.
Profit margin: The amount by which the sales of a product or service exceeds business and production costs.
Time to first token: The period between submitting a request to an AI model and receiving the beginning of its response. In an infrastructure context, the phrase can also be used more broadly to describe the time needed to bring new compute resources into productive use.
Vertical integration: A business model in which a company controls multiple stages of its supply chain or production process rather than relying solely on external suppliers.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.