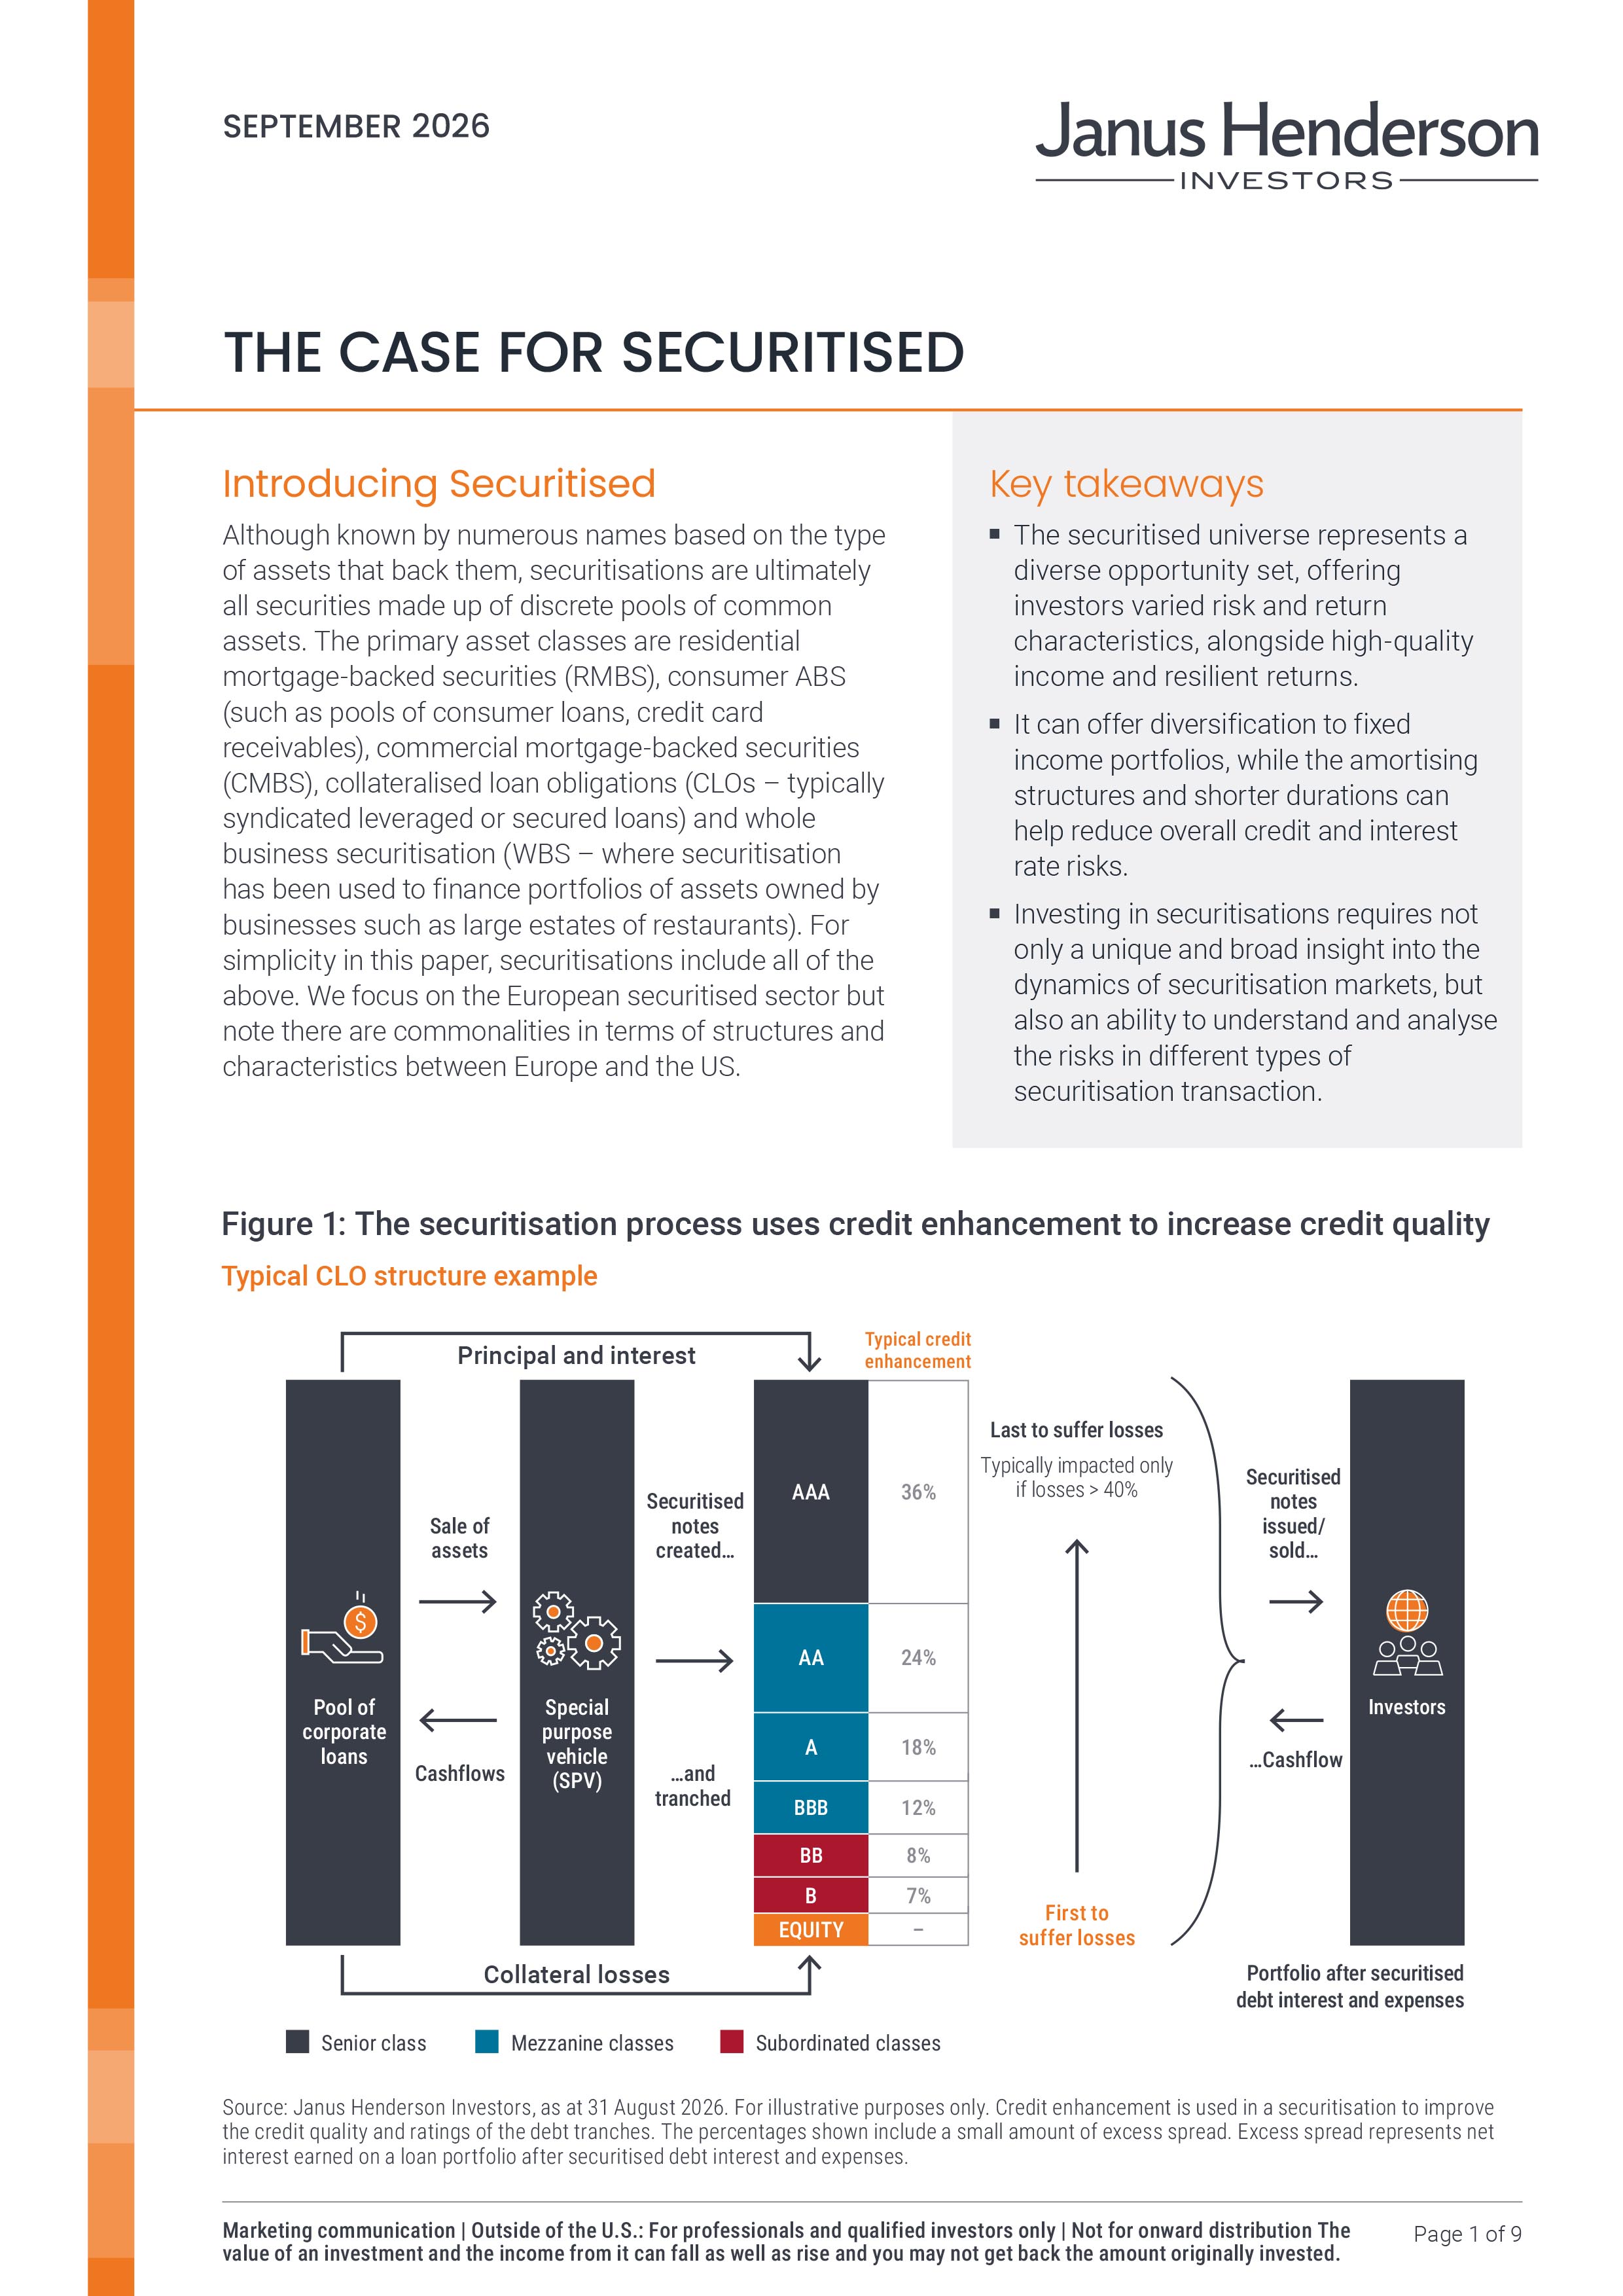
Key takeaways:
- The securitised universe represents a diverse opportunity set, offering investors varied risk and return characteristics, alongside high-quality income and resilient returns.
- It can offer diversification to fixed income portfolios, while the amortising structures and shorter durations can help reduce overall credit and interest rate risks.
- Investing in securitisations requires not only a unique and broad insight into the dynamics of securitisation markets, but also an ability to understand and analyse the risks in different types of securitisation transaction.
Investors benefit from securitised due to its defensive nature and a broad opportunity set as well as attractive relative value. Securitised offers better spreads compared to similarly-rated corporate bonds, historically lower default rates, and more attractive risk-adjusted returns (higherSharpe ratios). It is a misunderstood asset class, but misconceptions should not deter investment.
Securitisations serve as a valuable diversifier, reducing risks in core fixed income portfolios due to their amortising structures, shorter durations and exposure to ‘real economy’ and consumer-driven risks. European securitised has performed well, offering strong risk-adjusted returns compared to investment grade corporate bonds without liquidity concerns, even during market stress.
Specialist expertise can help navigate the nuances of the market. It enables investors to effectively evaluate risk against opportunity, adhere to regulatory standards, integrate ESG considerations effectively, and ultimately achieve long-term stability and diversification of returns. In other words, maximise the benefits of securitised.
In this Case for Securitised, we take a deep dive into the sector and evaluate each of its distinguishing features that enable the asset class to be combined successfully with other fixed income in diversified portfolios.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.
Important information
Please read the following important information regarding funds related to this article.
- An issuer of a bond (or money market instrument) may become unable or unwilling to pay interest or repay capital to the Fund. If this happens or the market perceives this may happen, the value of the bond will fall.
- When interest rates rise (or fall), the prices of different securities will be affected differently. In particular, bond values generally fall when interest rates rise (or are expected to rise). This risk is typically greater the longer the maturity of a bond investment.
- Some bonds (callable bonds) allow their issuers the right to repay capital early or to extend the maturity. Issuers may exercise these rights when favourable to them and as a result the value of the Fund may be impacted.
- The Fund may use derivatives to help achieve its investment objective. This can result in leverage (higher levels of debt), which can magnify an investment outcome. Gains or losses to the Fund may therefore be greater than the cost of the derivative. Derivatives also introduce other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- When the Fund, or a share/unit class, seeks to mitigate exchange rate movements of a currency relative to the base currency (hedge), the hedging strategy itself may positively or negatively impact the value of the Fund due to differences in short-term interest rates between the currencies.
- Securities within the Fund could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- The Fund could lose money if a counterparty with which the Fund trades becomes unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.