Key takeaways:
- Since the post-pandemic boom in luxury spending began to fade in 2023, global luxury demand has struggled to regain momentum amid persistently sluggish Chinese consumption, signs of price fatigue in certain segments, and a series of false starts that have fueled investor skepticism.
- Beneath the surface, important differences have emerged across luxury categories, customer cohorts, and regions, reinforcing the importance of a selective approach.
- We believe downbeat sentiment may be causing investors to overlook select luxury franchises whose long-term strengths remain intact, including deep brand heritage, high barriers to entry, pricing power, and strong free cash flow generation.
After booming in the wake of the pandemic, the global luxury market has been grappling with a prolonged slowdown since 2023. The sector includes some of the world’s most recognizable brands. Names such as Louis Vuitton, Gucci, Cartier, and Ferrari have built their reputations over generations, in some cases centuries, becoming synonymous with quality, craftsmanship, and desirability.
Yet few sectors face more investor skepticism today. And after a series of false starts, the debate has only intensified: Is luxury demand permanently impaired, or has a particularly challenging post-pandemic digestion cycle merely delayed its recovery?
While the answer is certainly nuanced, we believe the current environment may be offering opportunities for investors with a long-term view.
How the post-pandemic boom gave way to a tougher backdrop
After the initial economic shock from the onset of the pandemic in early 2020, a wave of government stimulus, combined with rising asset prices (which boosted household wealth) and the return of global travel helped unleash pent-up demand. Improved confidence and a broader desire to “feel good” among consumers added further momentum.
The result was a surge in consumption coupled with strong pricing power that drove rapid sales growth and significant outperformance among European luxury stocks through 2023. Growth was further supported as consumers demonstrated a willingness to trade up to higher-priced and more premium options.
As demand eventually normalized and inflation pressures continued to build, brands increasingly leaned into price increases to sustain growth, which eventually weighed on volumes, particularly among more occasional, or aspirational, luxury buyers. Optimism for a gradual recovery in 2026 has since been challenged by the U.S.-Iran conflict, with higher energy prices and geopolitical uncertainty dampening travel and consumer confidence, while demand from China has remained sluggish.
Exhibit 1: Luxury’s post-pandemic outperformance has reversed
Goldman Sachs EU Luxury Goods basket and STOXX Europe 600 Index, total returns in euro terms
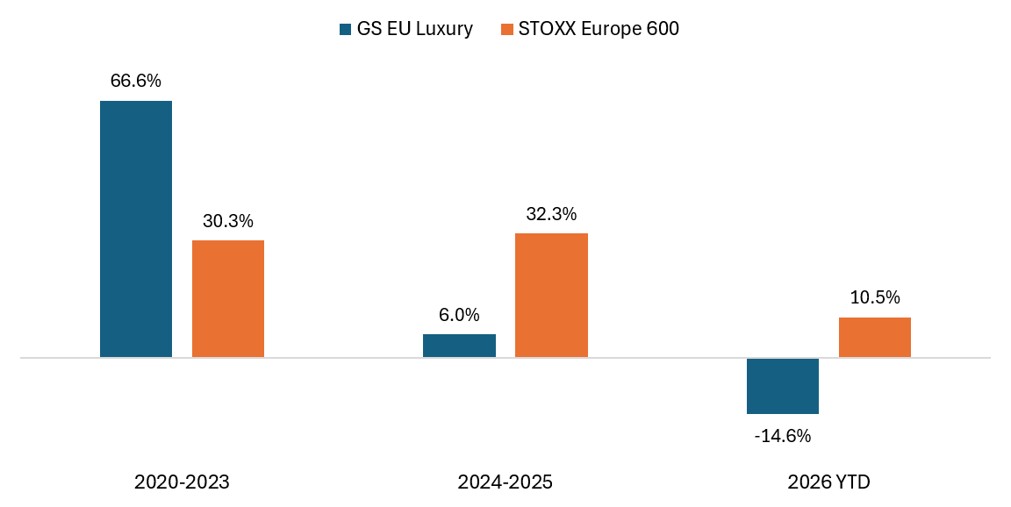
Source: Bloomberg, Janus Henderson Investors, as of 24 September 2026. Cumulative total returns in euro terms for the periods 31 December 2019 to 31 December 2023; 31 December 2023 to 31 December 2025; and 31 December 2025 to 24 September 2026. Past performance is no guarantee of future returns.
The bull/bear debate: Cyclical or structural?
The crux of the debate facing investors boils down to whether the stalled recovery primarily reflects a confluence of cyclical pressures or a more fundamental change in luxury demand.
Those in the bullish camp argue that the industry’s long-term growth drivers remain intact, citing high barriers to entry, premium pricing, high margins, and strong free cash flow generation. Moreover, affluent cohorts have continued to spend, and the industry has a long history of recovering following periods of economic uncertainty.
Bears counter that the slowdown points to a more lasting structural shift. They argue that repeated price increases have narrowed the customer base, while luxury increasingly competes with experiences, second-hand purchases, higher-quality replicas, and local brands for discretionary spending. With less scope for store expansion and outsized price increases, they argue, future growth could also prove harder to achieve than in prior cycles.
While we believe the luxury outlook is more constructive than the most downbeat scenarios imply, the challenges facing the sector are real, reinforcing the importance of a selective approach.
Forces shaping the luxury landscape
Crosscurrents beneath the surface, across product categories, customer groups, and regions, continue to shape industry dynamics and impact valuations. Since 2024, for instance, so-called hard luxury names, those specializing in jewelry and watches, have meaningfully outperformed their soft-luxury peers, brands more associated with leather goods and apparel (Exhibit 2). Jewelry has been particularly strong, benefiting from more resilient high-end demand and the perceived store-of-value appeal of precious metals. The gap has widened further this year, exacerbated by the Middle East conflict.
Exhibit 2: Hard luxury has held up better than soft luxury
BofA EU Hard Luxury and BofA EU Soft Luxury baskets, total returns in euro terms
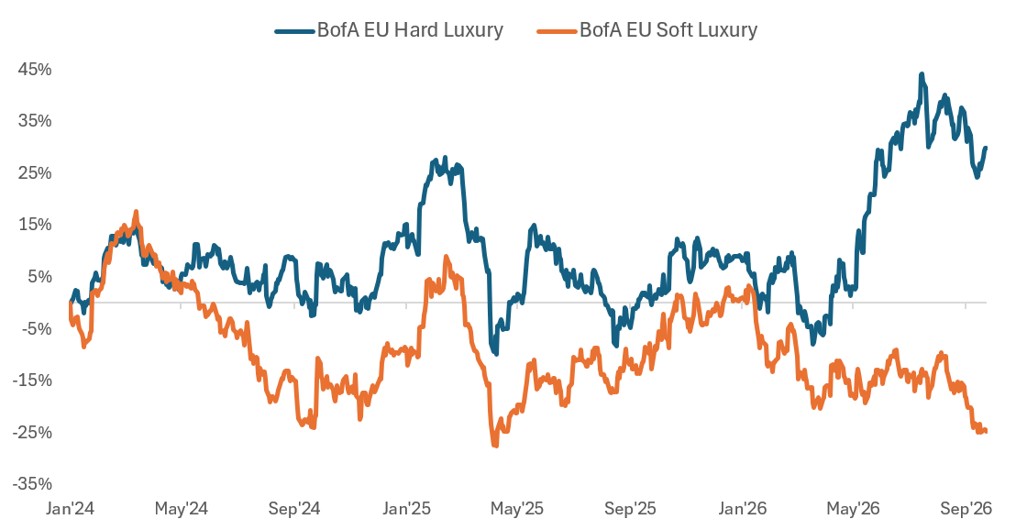
Source: Bloomberg. Data from 31 December 2023 to 24 September 2026. Past performance is no guarantee of future returns.
Consumer behavior helps explain some of this divergence. Luxury demand has become more concentrated at the very high end of the market, mirroring the K-shaped consumer dynamics evident across the broader economy. The most affluent cohorts and repeat customers have continued to spend, while affordability pressures have been a headwind for occasional luxury buyers and made new customer growth more of a challenge.
The luxury industry also serves as a useful reminder that where companies are listed is not necessarily where the demand comes from. While Europe may be home to many leading brands, their revenues are driven by a global customer base. Notably, U.S. consumers account for the largest share of global luxury sales (Exhibit 3) and have remained the primary growth engine of late, supported by strong equity markets and related wealth effects.
Exhibit 3: Luxury sales by region (location of purchase) and by cluster/nationality
Tourism and travel influence where luxury goods are purchased, which can differ from where demand originates.
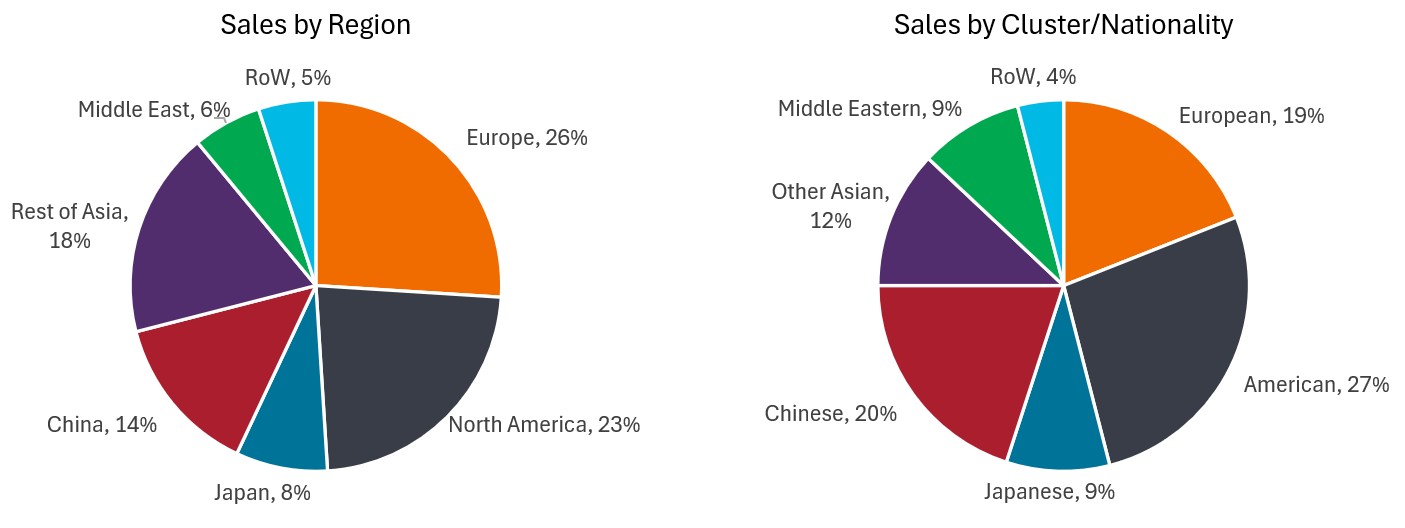
Source: Janus Henderson estimates. Global luxury data, 2025 annuals.
Lessons from prior downturns
Luxury demand has long been influenced by cyclical forces, and the sector has weathered downturns before. Historically, such periods have reflected delayed rather than permanently lost demand, with spending often rebounding as consumer confidence and the broader “feel-good” factor returns.
Prior episodes, including the global financial crisis in 2008-2009 and the Covid shock of 2020 saw annual luxury sales fall roughly 10% and 20%, respectively, with both instances followed by robust recoveries as sentiment improved. Similarly, the China anti-gifting campaign between 2012 and 2014, a government crackdown on gift-giving and luxury purchases by public officials, slowed industry growth but did not derail the sector’s longer-term expansion.
That said, the current cycle has been unusually prolonged, and the geopolitical landscape remains highly volatile, making the timing and shape of any recovery hard to predict.
Implications for investors
European luxury stocks have historically commanded premium valuations relative to the broader European equity market, for all the reasons previously discussed – durable brands, high barriers to entry, pricing power, among others. As of this writing, the sector is roughly back in line with the average premium to the STOXX Europe 600 Index observed over the last 10 years, and toward the lower end of the range seen during the post-Covid era.
Exhibit 4: European luxury valuation premium back in line with historical averages
Relative forward price to earnings (P/E) ratio
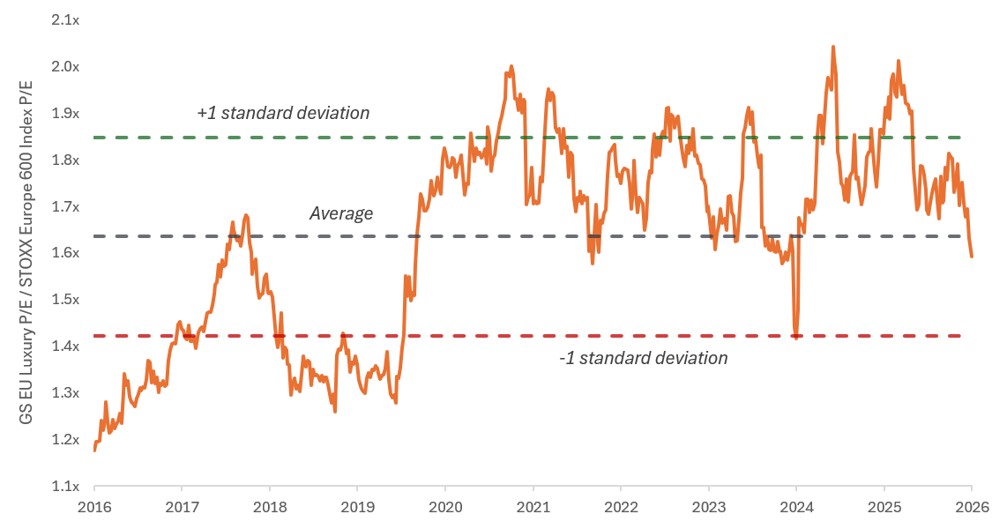
Source: Bloomberg. Data from 24 September 2016 to 24 September 2026. Represents the Goldman Sachs EU Luxury basket P/E relative to the STOXX Europe 600 Index P/E. Past performance is no guarantee of future returns.
What stands out most to us is the growing dispersion within the sector. While hard luxury names, particularly jewelry, have benefited from more resilient demand, much of that strength appears already reflected in valuations. Conversely, soft luxury stocks have been painted with the same broad brush, as though today’s more cautious consumer environment will persist in perpetuum. In some cases, leading brands are trading at their lowest price-to-earnings (P/E) ratios in more than a decade. While some discount may be warranted, we believe select leading franchises are being unduly penalized by the market.
In our view, the most compelling opportunities are likely to be found among those companies with quality franchises whose long-term strengths are being overlooked, rather than by chasing recent winners or unproven turnaround stories.
Ultimately, for a broader recovery to take hold, the sector will likely need to see renewed volume growth and firmer signs of stabilization in Chinese demand. However, despite ongoing macroeconomic and geopolitical uncertainty, we believe the luxury sector appears stalled rather than structurally broken, creating potential opportunities for investors willing to look beyond the current cycle.
BofA European Hard Luxury basket comprises European companies with significant exposure to hard luxury categories such as jewelry and watches.
BofA European Soft Luxury basket comprises European companies with significant exposure to soft luxury categories such as apparel, leather goods, handbags, and accessories.
Goldman Sachs EU Luxury Goods basket comprises European companies with significant exposure to the global luxury goods market across categories such as fashion, leather goods, jewelry, and luxury automobiles.
STOXX Europe 600 Index represents large, mid and small caplitalization companies across 17 countries in the European region.
Volatility measures risk using the dispersion of returns for a given investment.
IMPORTANT INFORMATION
Actively managed investment portfolios are subject to the risk that the investment strategies and research process employed may fail to produce the intended results. Accordingly, a portfolio may underperform its benchmark index or other investment products with similar investment objectives.
Equity securities are subject to risks including market risk. Returns will fluctuate in response to issuer, political and economic developments.
Foreign securities are subject to additional risks including currency fluctuations, political and economic uncertainty, increased volatility, lower liquidity and differing financial and information reporting standards, all of which are magnified in emerging markets.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.
Important information
Please read the following important information regarding funds related to this article.
- Shares can lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may fall as a result.
- Shares of small and mid-size companies can be more volatile than shares of larger companies, and at times it may be difficult to value or to sell shares at desired times and prices, increasing the risk of losses.
- High exposure to a particular country or geographical region carries a higher level of risk than a more broadly diversified portfolio.
- Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- If the Fund holds assets in currencies other than the base currency of the Fund, or you invest in a share/unit class of a different currency to the Fund (unless hedged, i.e. seeks to mitigate exchange rate movements between the share/unit class currency and the base currency of the Fund), the value of your investment may be impacted by changes in exchange rates.
- When the Fund, or a share/unit class, seeks to mitigate exchange rate movements of a currency relative to the base currency (hedge), the hedging strategy itself may positively or negatively impact the value of the Fund due to differences in short-term interest rates between the currencies.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- The performance of the Fund is not expected to precisely match the performance of the index at all times and the deduction of fees and expenses means the Fund might deliver a lower total return than the index.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
Specific risks
- Shares can lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may fall as a result.
- Emerging markets expose investors to higher volatility and greater risk of loss than developed markets; they are susceptible to adverse political and economic events, and may be less well regulated with less robust custody and settlement procedures.
- Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- If the Fund holds assets in currencies other than the base currency of the Fund, or you invest in a share/unit class of a different currency to the Fund (unless hedged, i.e. seeks to mitigate exchange rate movements between the share/unit class currency and the base currency of the Fund), the value of your investment may be impacted by changes in exchange rates.
- When the Fund, or a share/unit class, seeks to mitigate exchange rate movements of a currency relative to the base currency (hedge), the hedging strategy itself may positively or negatively impact the value of the Fund due to differences in short-term interest rates between the currencies.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.