Chart to Watch: Are rising bond yields getting you down?
It has been a tough year for traditional fixed income benchmarks given the sharp rise in government bond yields, with the G7 Government Index and Global Aggregate Bond Index (Global Agg) returning -2.5% and 1.5% respectively.*
In the US, lacklustre performance has been driven by a surge in yields (the 10-year U.S. Treasury has risen 83 basis points (bps) since the beginning of the year) on the back of reaccelerating inflation due to the Iran War, robust corporate earnings, heavy government and corporate debt issuance, large fiscal deficits, and a more hawkish Federal Reserve.
Globally, the story in other developed nations has been similarly bleak, with yields rising sharply on 10-year government bonds in Germany (+48 bps), Japan (+72 bps), the UK (+89 bps), and France (+146 bps).
Portfolio Managers John P Kerschner, Denis Struc and Nick Childs discuss why AAA rated collateralised loan obligations (CLOs) have outperformed benchmark fixed income indices with lower volatility thus far in 2026.
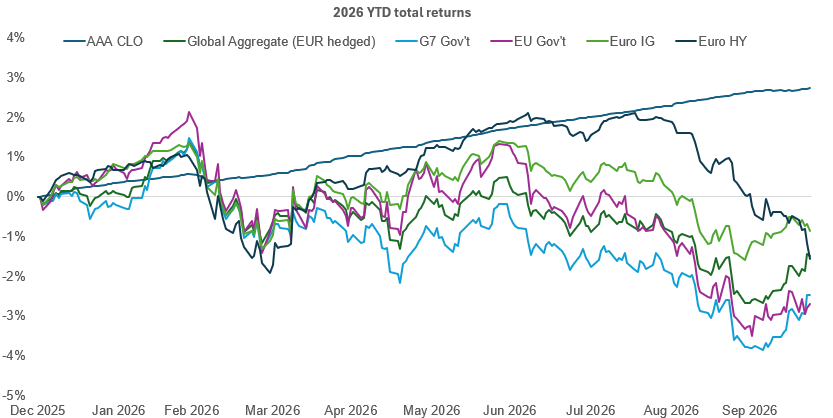
Source: Bloomberg, as of 23 October 2026. All returns are in Euros or EUR hedged. Indices used to represent asset classes: Global Agg = Bloomberg Global Aggregate Bond Index (EUR hedged), G7 Gov't = Bloomberg G7 Government Bond Index; EU Gov't — Bloomberg Euro Aggregate Treasury Index; Euro IG= ICE BofA Euro Corporate Index; Euro HY= ICE BofA Euro High Yield; European AAA CLOs = J.P. Morgan CLOIE AAA Index. Past performance does not predict future results.
Carry, or coupon income, is the most significant contributor to long-term returns on fixed income assets. Changes to bond prices are a secondary driver of returns, and can either add to, or detract from, carry returns. Long-duration bonds move more than short-term bonds when yields fluctuate, all else equal. Our preferred approach in the present environment is to a) focus on high-coupon bonds, b) be up in credit quality, and c) keep duration low to protect against fluctuations in yields. Currently yielding around 4%*** with a AAA rating and almost no duration risk, AAA CLOs check all the boxes, in our view, and have shown why they have been a consistent standout performer.
Key takeaways
- Looking across traditional fixed income sectors, investor returns in 2026 have been dragged down by poor performance within sovereign debt. In contrast, European AAA CLOs have returned nearly 3% year to date and have exhibited 90% less volatility than the Global Agg and corporate credit indices, supported by floating-rate income and lower spread duration. **
- AAA CLO credit spreads have remained tight amid robust economic growth, while this floating-rate structure means they stand to benefit when rates rise, as their coupons reset quarterly. Even if cash rates eventually fall, the additional credit spread on AAA CLOs can help cushion the impact on income.
- Given the heightened geopolitical and monetary policy uncertainty, we think fixed income investors should seek to maximise carry while keeping portfolio volatility to a minimum in the current environment. Attractive starting yields and supportive technicals suggest carry could remain a key driver of AAA CLO returns into 2027.
* Source: Bloomberg, in Euros, 31 December 2025 to 23 October 2026.
** Source: Bloomberg, daily year-to-date standard deviation as of 23 October 2026. Year-to-date annualised daily volatility is only 0.2% for Euro AAA CLOs, much lower than the circa 3% seen in European investment grade corporate and government markets.
*** Source: Bloomberg, as at 29 October 2026. J.P. Morgan CLOIE AAA Index.
Collateralized Loan Obligations (CLOs) are debt securities issued in different tranches, with varying degrees of risk, and backed by an underlying portfolio consisting primarily of below investment grade corporate loans. The return of principal is not guaranteed, and prices may decline if payments are not made timely or credit strength weakens. CLOs are subject to liquidity risk, interest rate risk, credit risk, call risk and the risk of default of the underlying assets.
Fixed income securities are subject to interest rate, inflation, credit and default risk. The bond market is volatile. As interest rates rise, bond prices usually fall, and vice versa. The return of principal is not guaranteed, and prices may decline if an issuer fails to make timely payments or its credit strength weakens.
Securitized products, such as mortgage- and asset-backed securities, are more sensitive to interest rate changes, have extension and prepayment risk, and are subject to more credit, valuation and liquidity risk than other fixed-income securities.
Credit quality ratings are measured on a scale that generally ranges from AAA (highest) to D (lowest).
A credit spread is the difference in yield between a corporate or securitized bond and a government bond (such as a U.S. Treasury) of the same maturity. It compensates investors for the risk that the borrower might default.
Spread duration: A measure of how sensitive a bond or other fixed income security’s price is to changes in its credit spread. A lower spread duration means its price is less sensitive to movements in credit spreads.
Volatility measures risk using the dispersion of returns for a given investment.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.
Important information
Please read the following important information regarding funds related to this article.
- An issuer of a bond (or money market instrument) may become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
- Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- The performance of the sub-fund’s investments in CLOs will depend in part upon the performance and operational effectiveness of the managers of the CLOs. The sub-fund will invest in CLOs which are subject to management and performance fees charged by the managers of the CLOs. These are in addition to the fees charged to the sub-fund.
- Repayments from underlying loans are used to repay CLO securities after a specified period, but the timing is uncertain. Faster repayments can lead to early prepayment of securities trading above par, causing mark-to-market losses and forcing reinvestment at lower yields, reducing income. Slower repayments extend maturity, which can also result in losses. CLOs and callable securities may be redeemed early by issuers or equity holders, creating reinvestment challenges and potential income decline.
- Collateralised Loan Obligations (CLOs) are investments backed by pools of corporate loans. They carry risks from both the loans and the structure of the CLO. Risk varies by tranche, and credit ratings are not guarantees— even highly rated tranches can lose value in stressed markets. Key risks include liquidity, interest rate changes, credit defaults, and uncertainty around repayments.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- The Company may use options for efficient portfolio management and to increase income. Options can be volatile and may sometimes result in loss of capital.
Specific risks
- An issuer of a bond (or money market instrument) may become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
- Active management techniques that have worked well in normal market conditions could prove ineffective or negative for performance at other times.
- Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
- Collateralised Loan Obligations (CLOs) are investments backed by pools of corporate loans. They carry risks from both the loans and the structure of the CLO. Risk varies by tranche, and credit ratings are not guarantees— even highly rated tranches can lose value in stressed markets. Key risks include liquidity, interest rate changes, credit defaults, and uncertainty around repayments.
- Repayments from underlying loans are used to repay CLO securities after a specified period, but the timing is uncertain. Faster repayments can lead to early prepayment of securities trading above par, causing mark-to-market losses and forcing reinvestment at lower yields, reducing income. Slower repayments extend maturity, which can also result in losses. CLOs and callable securities may be redeemed early by issuers or equity holders, creating reinvestment challenges and potential income decline.
- The performance of the sub-fund’s investments in CLOs will depend in part upon the performance and operational effectiveness of the managers of the CLOs. The sub-fund will invest in CLOs which are subject to management and performance fees charged by the managers of the CLOs. These are in addition to the fees charged to the sub-fund.
Specific risks
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
- Collateralised Loan Obligations (CLOs) are investments backed by pools of corporate loans. They carry risks from both the loans and the structure of the CLO. Risk varies by tranche, and credit ratings are not guarantees— even highly rated tranches can lose value in stressed markets. Key risks include liquidity, interest rate changes, credit defaults, and uncertainty around repayments.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- Repayments from underlying loans are used to repay CLO securities after a specified period, but the timing is uncertain. Faster repayments can lead to early prepayment of securities trading above par, causing mark-to-market losses and forcing reinvestment at lower yields, reducing income. Slower repayments extend maturity, which can also result in losses. CLOs and callable securities may be redeemed early by issuers or equity holders, creating reinvestment challenges and potential income decline.
- The performance of the sub-fund’s investments in CLOs will depend in part upon the performance and operational effectiveness of the managers of the CLOs. The sub-fund will invest in CLOs which are subject to management and performance fees charged by the managers of the CLOs. These are in addition to the fees charged to the sub-fund.
- Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- An issuer of a bond (or money market instrument) may become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
- The Company may use options for efficient portfolio management and to increase income. Options can be volatile and may sometimes result in loss of capital.
Specific risks
- An issuer of a bond (or money market instrument) may become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
- When interest rates rise (or fall), the prices of different securities will be affected differently. In particular, bond values generally fall when interest rates rise (or are expected to rise). This risk is typically greater the longer the maturity of a bond investment.
- While high yield (non-investment grade) bonds generally offer higher rates of interest than investment grade bonds, they are more speculative and more sensitive to adverse changes in market conditions.
- Asset-Backed Securities (ABS) and other forms of securitised investments may be subject to greater credit / default, liquidity, interest rate and prepayment and extension risks, compared to other investments such as government or corporate issued bonds and this may negatively impact the realised return on investment in the securities.
- Some bonds (callable bonds) allow their issuers the right to repay capital early or to extend the maturity. Issuers may exercise these rights when favourable to them and as a result the value of the Fund may be impacted.
- High exposure to a particular country or geographical region carries a higher level of risk than a more broadly diversified portfolio.
- Derivatives may be used to help achieve the investment objective. This can result in leverage (higher levels of debt), which can magnify an investment outcome. Gains or losses may therefore be greater than the cost of the derivative. Derivatives also introduce other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
- When the Fund, or a share/unit class, seeks to mitigate exchange rate movements of a currency relative to the base currency (hedge), the hedging strategy itself may positively or negatively impact the value of the Fund due to differences in short-term interest rates between the currencies.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- The Fund may incur a higher level of transaction costs as a result of investing in less actively traded or less developed markets compared to a fund that invests in more active/developed markets.
- Some or all of the ongoing charges and other costs of the Fund may be taken from capital, which may erode capital or reduce potential for capital growth.
- In addition to income, this share class may distribute realised and unrealised capital gains and original capital invested. Fees, charges and expenses are also deducted from capital. Both factors may result in capital erosion and reduced potential for capital growth. Investors should also note that distributions of this nature may be treated (and taxable) as income depending on local tax legislation.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.