Key takeaways:
- The Budget prioritised fiscal credibility, avoiding major tax rises or unfunded spending measures that could have unsettled gilt and equity markets.
- A relatively stable gilt market could ease pressure on companies’ financing costs and provide a more supportive backdrop for UK equity valuations.
- UK equities remain attractively valued relative to global peers, with particularly compelling opportunities among more domestically-focused mid-cap companies.
Last year we argued that the UK Autumn Budget was a clearing event. Having eased some of the uncertainty weighing on businesses and consumers, it allowed investors to refocus on corporate fundamentals. Since then, despite US equities and artificial intelligence (AI) companies dominating headlines, the FTSE All-Share has kept pace with both the S&P 500 and the MSCI World indices.
Figure 1: UK equity performance since the Autumn Budget 2025
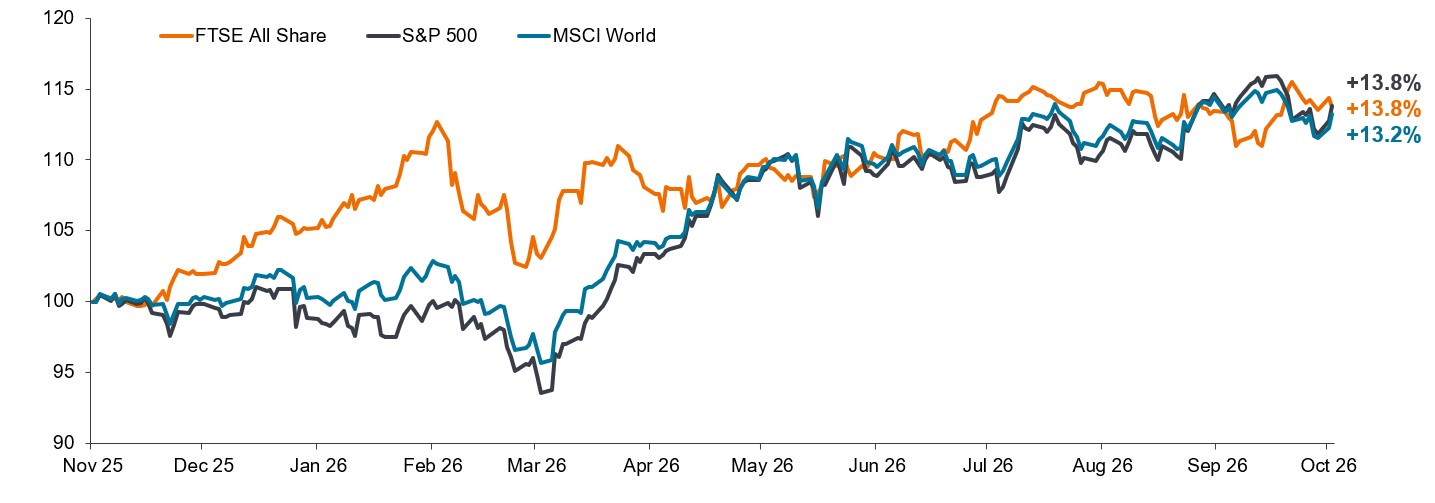
Source: Bloomberg; Janus Henderson Investors, total returns in GBP. Data as at 26 October 2026. Index returns rebased to 100 as at 26 November 2025. Past performance does not predict future returns.
The periods leading up to the last two Autumn Budgets were marked by significant speculation and uncertainty for businesses, consumers and investors, impacting confidence and market volatility. This year, therefore, we were looking for the government’s first Budget under Prime Minister Andy Burnham and Chancellor John Healey to be more of a non-event, which they appear to have delivered. Against a backdrop of decade-high gilt yields, sticky inflation and elevated government borrowing levels, the Budget looks to have prioritised fiscal credibility, avoiding measures that could be perceived as adding to inflationary or fiscal pressures, while providing some support for consumers given the ongoing cost of living crisis. This has (at the time of writing) been received positively by the bond market, with yields falling slightly (yields move in opposite directions with bond prices).1 For equity investors, the absence of significant tax hikes or new government spending, and the bond market’s muted reaction, has been helpful. A stable gilt market should reduce pressure on companies’ cost of capital and provide a more supportive backdrop for equity valuations.
One of the Budget’s key announcements was the temporary three-percentage-point increase in the Bank Corporation Tax Surcharge, which will help fund the government’s short-term spending increase. This was below the expected increase already priced in by markets, and saw bank stocks outperform on the day.2 The Budget also helped ease concerns around potential government intervention in utilities. Share prices across the sector rose, including water companies, as well as SSE and National Grid, with the Chancellor committing to cheaper and faster grid connections.3
While the Budget offered no significant new catalyst for UK equities, following several years of political and fiscal uncertainty impacting sentiment towards UK assets, we think this Budget does little to alter the investment case for UK equities, which remains attractively valued relative to global peers.
Figure 2: UK equities: Undervalued yet overlooked
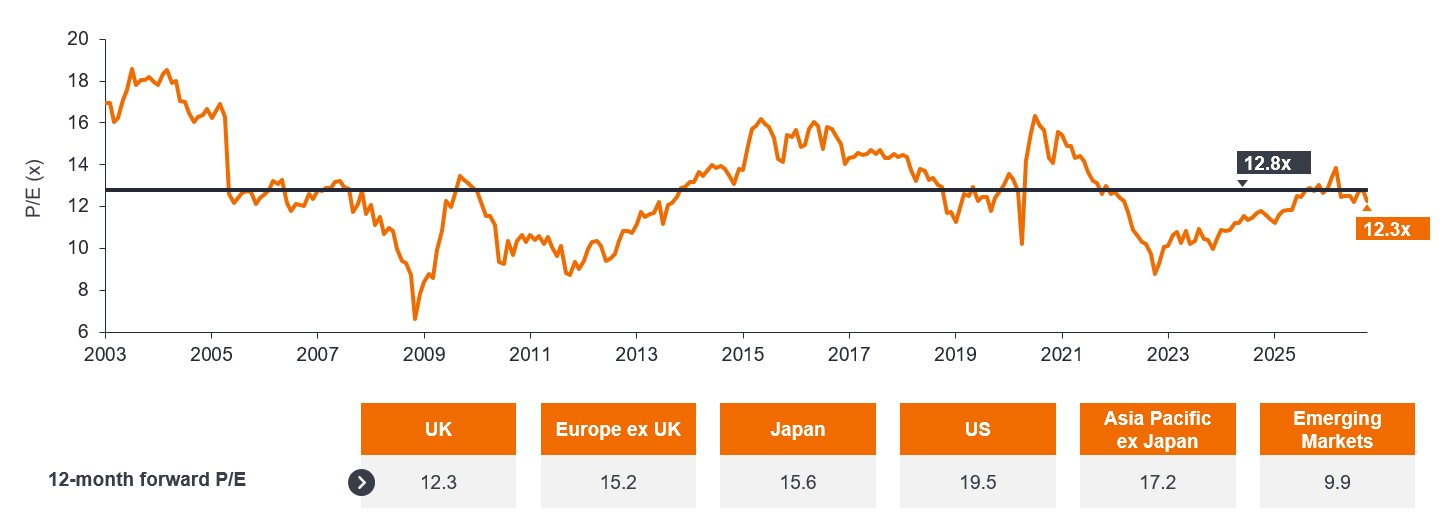
Source: DataStream, Janus Henderson Investors analysis, as at 30 September 2026. Table: UK – FTSE 350, Europe ex UK – MSCI Europe ex UK, Japan – TOPIX, US – MSCI United States, Asia Pacific ex Japan – MSCI Pacific ex Japan, Emerging Markets – MSCI Emerging Markets. Past performance does not predict future returns.
In particular, the more domestically-focused FTSE 250 stocks, appear undervalued versus the globally-focused FTSE 100, especially given the slightly better UK economic growth so far this year. Further, foreign flows into UK equities may improve as investors look beyond US equities for diversification. Against this backdrop, we believe the case for reassessing allocations to UK equities is becoming increasingly compelling.
IMPORTANT INFORMATION
References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
There is no guarantee that past trends will continue, or forecasts will be realised.
www.gov.uk; 2026 Budget in full; 28 October 2026.
1, 2, 3 Bloomberg, Janus Henderson Investors as at 28 October 2026. Past performance does not predict future returns.
Bond yield: The level of income on a security expressed as a percentage rate. For a bond, this is calculated as the coupon payment divided by the current bond price. There is an inverse relationship between bond yields and bond prices. Lower bond yields mean higher bond prices, and vice versa.
Cost of capital: The return a company must offer investors and lenders to obtain funding. Higher interest rates generally increase this cost.
Diversification: A way of spreading risk by mixing different types of assets or asset classes in a portfolio on the assumption that these assets will behave differently in any given scenario. Assets with low corelation should provide the most diversification.
Fiscal credibility: Investors’ confidence that a government can manage taxation, spending and borrowing sustainably.
Gilt: UK government bonds sold by the Bank of England used to finance public spending.
Price-to-earnings ratio: A popular ratio used to value a company’s shares compared to other stocks or a benchmark. It is calculated by dividing the current share price by its earnings per share.12-month forward price-to-earnings: Calculated by dividing the current share price by projected earnings for the next 12 months to value a company’s shares.