Key takeaways:
- Signs of broader market participation remained evident in the third quarter despite mixed sector performance. Energy rebounded sharply as oil prices rose, while technology and healthcare also outperformed. Several rate-sensitive sectors lagged as higher interest rates pressured valuations.
- Artificial intelligence (AI) remained a powerful investment theme across sectors, but attention increasingly centered on which companies can translate AI adoption and investment into sustainable earnings and competitive advantages.
- As investors became more selective about assessing AI’s potential beneficiaries, we believe a focus on company fundamentals and a long-term perspective remain important, with opportunities taking shape across secular themes such as growing demand for compute, electrification, and healthcare innovation.
Global equities advanced in the third quarter, supported by strong corporate earnings performance and resilient economic growth. Stocks experienced some headwinds, however, as higher commodity prices and rising interest rates pressured valuations and injected uncertainty into the economic outlook. Amid these crosscurrents, we saw signs of market broadening, both from a sector and geographic standpoint. AI remained a powerful investment theme, though investors have become increasingly selective in assessing its potential beneficiaries.
While we continue to closely monitor macroeconomic developments and their potential impact across sectors, our approach remains deeply rooted in bottom-up research and fundamentals. Below, several of our global analysts share their perspectives on recent market developments and what they anticipate going forward.
Q3 2026 global equity performance (total return)
Energy rebounded amid higher oil prices, while technology and healthcare also outperformed. Utilities, industrials, real estate, and consumer sectors lagged as several rate-sensitive areas came under pressure.
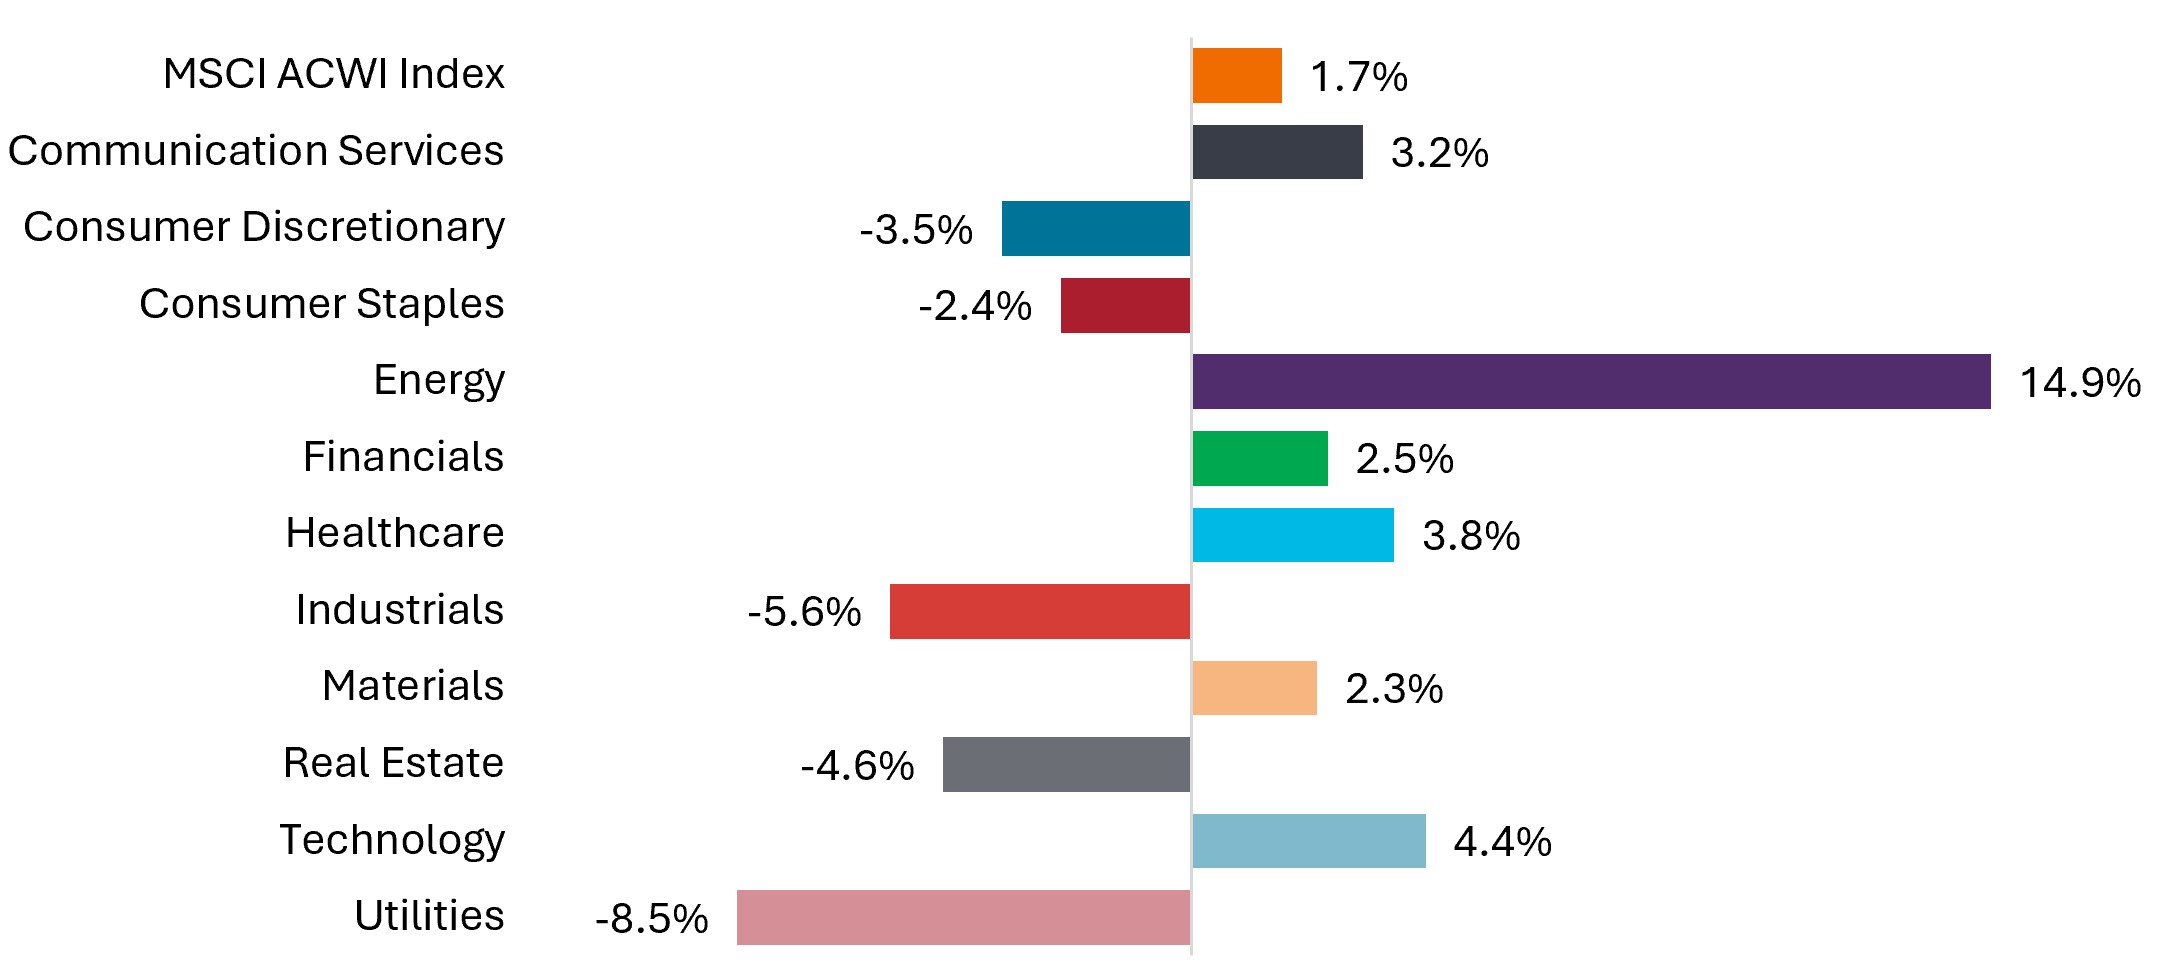
Source: Bloomberg, data from 30 June 2026 to 30 September 2026. Returns are for the MSCI All Country World Index (ACWI) and its 11 sectors. The MSCI ACWI Index captures large- and mid-cap representation across 23 developed markets and 24 emerging markets countries. Past performance is no guarantee of future results.
Communication Services
AI continues to reshape the competitive landscape
What happened: The Communication Services sector outperformed the broader market in the third quarter, although performance remained highly dispersed and largely company specific. Shares of Meta rose sharply as strong advertising fundamentals and early traction for its Muse AI agent helped offset ongoing concerns about the scale and financing of its AI investment cycle. Shares of media companies were also relatively resilient. By contrast, telecommunications and cable stocks lagged due to investor concerns over slower subscriber growth, competitive pricing pressures, higher funding costs, and increasing balance sheet leverage.
Looking Ahead: We continue to see attractive opportunities across the Communication Services sector, particularly among companies that are effectively incorporating AI to enhance their competitive positioning and earnings potential. We believe the long-term impact of AI will ultimately be far more pervasive and value-creating than many investors currently anticipate. At the same time, we recognize that AI is likely to create both winners and losers. We expect investors will pay close attention to rising capital intensity and whether companies can deliver attractive returns on AI-related investments. As a result, we anticipate increasing divergence between companies that successfully monetize their AI investments and those that struggle to generate adequate returns.
Consumer
Balancing near-term pressures and long-term opportunities
What happened: Higher fuel prices, persistent inflation, and rising interest rates contributed to a less certain environment for discretionary spending and a mixed quarter for consumer stocks. Shares of Amazon rallied amid the ongoing strength in its cloud business, advertising revenues, and e-commerce assets. We also saw relative outperformance among value-oriented or market share-gaining retailers. In contrast, prospects for higher mortgage rates pressured shares of homebuilders and housing-related retailers, while uncertainty for discretionary spending led to relative weakness across restaurant, travel, and leisure stocks.
Looking ahead: U.S. household balance sheets appear generally healthy, and we have continued to see resilient spending by upper-income consumers. At the same time, we recognize that higher food, fuel, and financing costs may put an increased strain on consumer budgets, especially for lower-income households. As a result, we could see spending become more selective as people prioritize essential purchases. Pressure on consumers could worsen if energy-driven inflation accelerates or the labor market deteriorates. Conversely, easing geopolitical tensions and moderating inflation could provide a positive tailwind for consumer discretionary spending going forward.
Given the uncertainties in this environment, we continue to favor an approach that balances investments in durable, defensive consumer businesses with select cyclical opportunities. We are also finding opportunities in companies we believe are positioned to benefit from long-term secular trends such as digitization and the growing adoption of AI.
Energy & Utilities
Opportunity amid uncertainty
What happened: Energy and utilities stocks delivered sharply different performance in the third quarter. Energy stocks significantly outperformed both utilities and the broader market as crude oil prices surged higher amid escalating tensions in the Middle East. Prospects for a near-term peace agreement with Iran deteriorated, and concerns surrounding the Strait of Hormuz pushed oil prices above $100 per barrel. Rising commodity prices benefited many energy producers and supported strong sector performance.
Utilities stocks, by contrast, lagged during the quarter. Concerns surrounding data center permitting and regulatory policy uncertainty weighed on investor sentiment, while rising interest rates pressured stock valuations. However, we believe long-term demand fundamentals remain attractive, particularly for companies exposed to power infrastructure and electrification needs.
Looking ahead: The outlook for commodity prices and energy stocks remains closely tied to developments in the Iran conflict, where we have yet to see a resolution. The Trump administration has expressed a desire to bring down oil and diesel prices, including by reconsidering export bans, ahead of the U.S. midterm elections. However, the effectiveness of such measures remains uncertain. We also have yet to see any evidence that higher prices are reducing energy demand.
As we navigate this environment, we believe maintaining a relatively defensive posture within energy remains appropriate, focusing on companies with high-quality, long-duration assets that are underappreciated by the market. Within utilities, we continue to favor independent power producers positioned to benefit from growing electricity demand driven by data center expansion, AI adoption, and broader electrification trends.
Financials
Uncovering opportunities across global financial services
What happened: The third quarter saw uneven performance by financial stocks despite generally favorable fundamentals. Consumer spending remains relatively steady, while most consumer and corporate credit metrics appear healthy. Capital markets activity, including M&A and capital raising, continued to expand, though growth moderated relative to the second quarter.
Looking ahead: Our deep fundamental research has continued to uncover compelling opportunities across the global financial services sector. We remain encouraged by long-term growth drivers, including a strengthening capital markets environment and expanding global wealth. Increased adoption of AI has the potential to reshape business models across the industry, creating both opportunities and risks. We are actively engaged in research and dialogue to identify potential winners and avoid potential losers as business models evolve. We also continue to see opportunities with select European banks, which may benefit from an improving regulatory backdrop and possible industry consolidation. Higher interest rates could also provide an earnings tailwind for financial services companies.
Healthcare
Focused on innovation and differentiated market opportunities
What happened: Healthcare was one of the stronger-performing sectors in the third quarter, led by gains in biotechnology, medical technology, and healthcare equipment companies. Investor enthusiasm was especially concentrated in a relatively small group of biotech and life sciences tools companies with potential connections to AI-enhanced drug discovery and medical research. The resulting narrow market rally overshadowed other biotechnology companies with strong fundamentals and promising pipelines. In our view, this disconnect reflected investor sentiment more than underlying business fundamentals.
The quarter also brought encouraging regulatory and clinical developments. Leadership appointments at the FDA and key review divisions improved regulatory visibility, while we saw a steady pace of drug approvals. Clinical trial activity remained robust, highlighted by positive Phase 3 results for Eli Lilly’s obesity therapy, retatrutide, and continued advances across several oncology programs. M&A activity also remained strong as large pharmaceutical companies increasingly turned to acquisitions to replenish product pipelines and address upcoming patent expirations.
Looking Ahead: We believe the healthcare sector offers attractive opportunities for patient, selective investors. Healthcare stocks continue to trade at valuation discounts relative to both historical averages and the broader equity market, creating a favorable landscape for active stock selection.
We remain focused on companies with differentiated products, strong clinical data, and durable competitive advantages. These include early commercial-stage companies with breakthrough products and later-stage development businesses with lower clinical risk profiles. We are also constructive on managed care, where reimbursement visibility is improving and medical cost trends support the potential for margin recovery. Meanwhile, we see potential for life sciences tools companies that may benefit from healthier biotech funding, sustained pharmaceutical R&D spending, and gradually improving demand trends. While the current environment has created periodic headwinds, we remain confident that disciplined stock selection and a focus on differentiated innovation can create long-term value in the sector.
Industrials
Manufacturing continues to show signs of resilience
What happened: Industrial shares underperformed broader equities in the third quarter. Economic uncertainty increased after fading prospects for a Middle East peace agreement led to a renewed rise in crude oil prices. Investors worried that higher-for-longer interest rates could potentially derail an anticipated manufacturing recovery. However, measures of business confidence continued to indicate cautious optimism, while manufacturing activity showed signs of improvement. Earlier this year, the Institute for Supply Management Purchasing Managers’ Index (PMI) moved above the key 50 level that signals a renewed expansion in the manufacturing sector, and the PMI remained above this threshold throughout the third quarter.
Looking ahead: We remain encouraged by the resilience of the industrial sector, even as we recognize uncertainty tied to interest rates, commodity prices, tariffs, freight demand, and consumer and business confidence. Developments around the U.S. midterm elections and the upcoming USMCA (United States-Mexico-Canada Agreement) joint review negotiations could also lead to share-price volatility.
We continue to prioritize well-managed businesses that we believe have the potential for operational improvements, or where we see company-specific catalysts that may drive sustainable profit growth. We have also sought to capitalize on secular tailwinds such as increased demand for commercial aerospace, electrification, and infrastructure to support AI-related power demand and data centers. While public debate surrounding AI and data center development may create uncertainty, our enthusiasm for these long-term themes remains intact.
Technology
AI continues to drive opportunity
What happened: Global technology stocks rose in the third quarter, although at a slower pace than in the second quarter. While the second-quarter rally was broad-based, fueled by enthusiasm around AI, the recent quarter saw investors become more selective. This led to a reassessment of valuations in certain areas of the market.
Sector leadership also shifted. Software stocks generally outperformed in the third quarter, after underperforming in the first half of the year, while semiconductor and capital equipment companies gave back a portion of their strong year-to-date gains. Despite this rotation, AI remains the key driver of technology-sector performance, in our view. Demand for memory, processors, networking equipment, and other critical AI components continues to expand rapidly, while supply constraints have limited the pace at which new capacity can be brought online. We believe this combination of strong demand and constrained supply continues to support pricing power and earnings growth potential that remains underappreciated by the market.
Looking ahead: We remain constructive on the long-term opportunities created by AI. In our view, the next phase of the AI buildout will likely be shaped by constraints across memory, optics, graphics processing units (GPUs), central processing units (CPUs), power infrastructure, and other critical inputs. As businesses, governments, and consumers increasingly adopt AI-enabled tools, we believe demand for this infrastructure should remain strong.
While much of the market’s attention has focused on companies building AI infrastructure, we also see growing opportunities for businesses helping customers deploy and utilize these technologies. These include data storage and processing providers and software companies incorporating AI to power more efficient workflows.
We remain focused on identifying high-quality companies with durable competitive advantages, strong balance sheets, and the ability to create value across a range of economic and technological outcomes. We have identified opportunities among suppliers of critical AI components and materials. In the software industry, we remain selective, favoring businesses that can leverage AI to accelerate revenue growth or expand margins.
IMPORTANT INFORMATION
Artificial intelligence (“AI”) focused companies, including those that develop or utilize AI technologies, may face rapid product obsolescence, intense competition, and increased regulatory scrutiny. These companies often rely heavily on intellectual property, invest significantly in research and development, and depend on maintaining and growing consumer demand. Their securities may be more volatile than those of companies offering more established technologies and may be affected by risks tied to the use of AI in business operations, including legal liability or reputational harm.
Consumer discretionary industries can be significantly affected by the performance of the overall economy, interest rates, competition, consumer confidence and spending, and changes in demographics and consumer tastes.
Consumer staples industries can be significantly affected by demographics and product trends, competitive pricing, food fads, marketing campaigns, environmental factors, and government regulation, the performance of the overall economy, interest rates, and consumer confidence.
Energy industries can be significantly affected by fluctuations in energy prices and supply and demand of fuels, conservation, the success of exploration projects, and tax and other government regulations.
Financials industries can be significantly affected by extensive government regulation, subject to relatively rapid change due to increasingly blurred distinctions between service segments, and significantly affected by availability and cost of capital funds, changes in interest rates, the rate of corporate and consumer debt defaults, and price competition.
Health care industries are subject to government regulation and reimbursement rates, as well as government approval of products and services, which could have a significant effect on price and availability, and can be significantly affected by rapid obsolescence and patent expirations.
Monetary Policy refers to the policies of a central bank, aimed at influencing the level of inflation and growth in an economy. It includes controlling interest rates and the supply of money.
Purchasing Managers’ Index (PMI) is an index of the prevailing direction of economic trends in the manufacturing and service sectors, based on a survey of private sector companies.
S&P 500® Index reflects U.S. large-cap equity performance and represents broad U.S. equity market performance.
Technology industries can be significantly affected by obsolescence of existing technology, short product cycles, falling prices and profits, competition from new market entrants, and general economic conditions. A concentrated investment in a single industry could be more volatile than the performance of less concentrated investments and the market as a whole.
Volatility measures risk using the dispersion of returns for a given investment.