Key takeaways:
- Passive ETFs deliver index exposure either physically, by holding the underlying shares, or synthetically, by using a swap with a counterparty that delivers the index return.
- For US equities, synthetic ETFs have historically outperformed physical ETFs through greater efficiency in managing dividend withholding taxes at the fund level.
- For a synthetic ETF, the drag versus the index is a combination of the total expense ratio (TER) and the swap spread. Keeping both as low as possible should create better outcomes for investors.
Exchange traded fund (ETF) investing has transformed the way investors access markets. Over the past two decades, the range of exposures available has grown significantly, while costs have continued to fall. For investors building a core allocation to a major market such as US equities, a passive ETF offers a simple, low-cost way to capture the return of the index.
But not all passive ETFs are built the same way. How an ETF obtains its exposure – its replication method – can have a meaningful impact on how much of the index return ultimately reaches the investor.
Physical and synthetic replication: two routes to the same index
Passive ETFs generally obtain their index exposure in one of two ways.
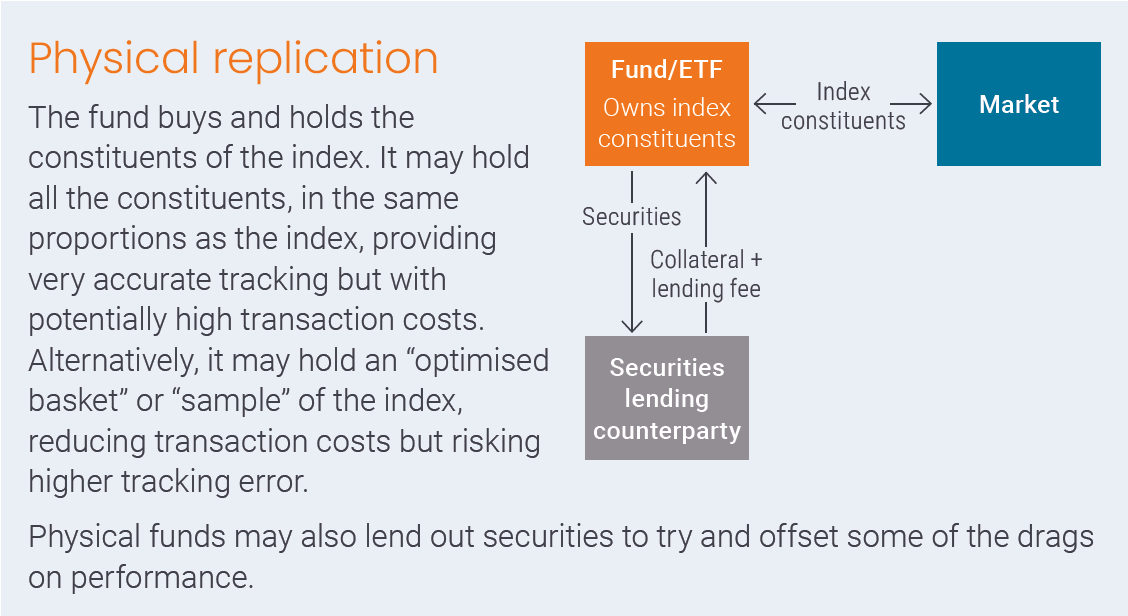
A physical ETF buys and holds some or all of the securities in the index. It may hold every constituent in the same proportions as the index, or an optimised sample designed to reduce trading costs. Physical funds may also lend out securities to help offset some of the drags on performance.
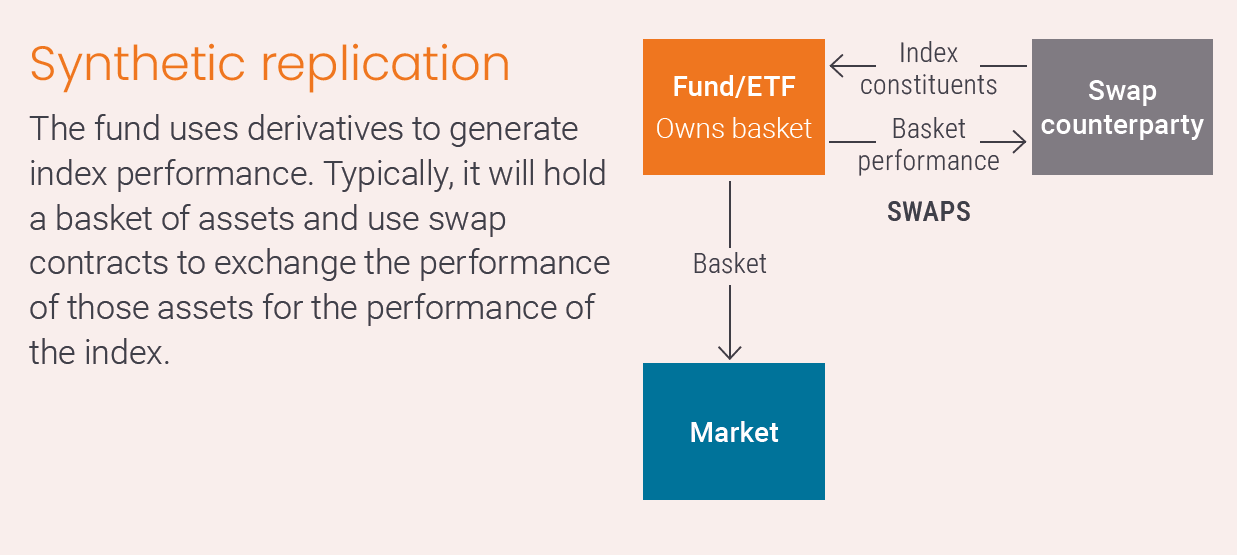
A synthetic ETF typically holds a basket of equities and enters into a swap agreement with a counterparty, usually one or more large banks. Under the swap, the fund exchanges the performance of its basket for the performance of the index. The counterparty is contractually obliged to deliver the index return, which allows for precise index exposure.
Source: Janus Henderson Investors. For illustrative purposes.
Both are well-established approaches. Which one is more efficient depends on the market being tracked – and in US equities, tax is often the deciding factor.
Why synthetic can have the edge in US equities
Many US companies pay dividends, and those dividends are subject to withholding tax when paid to non-US investors. A European-domiciled physical ETF that holds US shares directly will typically have 15% or 30% of every dividend withheld at source. That tax reduces the income retained by the fund and is a permanent drag on returns compared with the index.
The impact is not trivial. As a hypothetical illustration, if a broad US equity index had a dividend yield of 1.3%, a 15% withholding tax would cost a physical fund roughly 0.2% a year (1.3% × 15% ≈ 0.195%) before any other costs are considered.
A synthetic ETF works differently. The swap counterparty delivers the total return of the index. Under US tax rules, swaps referencing qualifying indices are generally not subject to the same dividend withholding tax, which means a synthetic ETF can receive the index return with dividends reinvested without the 15% deduction.
For investors that would otherwise face withholding tax on US dividends, this structural advantage means synthetic ETFs have historically outperformed their physical equivalents over time.
Understanding the costs of a synthetic ETF
All passive ETFs face drags on performance, be it from tax, transaction costs, costs of running the fund or imperfect replication. For an investor in a synthetic ETF, the drag versus the index traded is a combination of two elements:
- The total expense ratio (TER): the annual cost of managing the fund, deducted from fund assets.
- The swap spread: the cost charged by the swap counterparty for delivering the index return.
Together, these represent the gap between the return of the index and the return the fund delivers. At Janus Henderson, we disclose both components on our website so investors can clearly understand what they are paying for and how much of the index return they can expect to receive.
What determines where fees and swap spreads are set?
Several factors influence the level of the TER and the swap spread:
- Market financing dynamics. Swap counterparties price their spreads based on their own costs of funding and hedging the exposure they deliver, as well as wider demand for that exposure across the market. These conditions change over time, which is why swap spreads can move.
- The cost of building and running the product. An issuer faces a range of costs in bringing an ETF to market and operating it, including fund administration, custody, listing and benchmark licensing fees paid to index providers.
The issuer’s role is to manage these costs efficiently – negotiating competitive swap terms, controlling operating costs and structuring the product to minimise performance drag.
The bottom line
For investors building core exposure to US equities, the replication method is important – as is the headline fee.
Physical ETFs that hold US shares directly typically lose part of every dividend to withholding tax. A synthetic structure may deliver the full index return without that deduction. For many investors, that makes it the more efficient way to own the US market.
That efficiency comes at a cost, and it should be transparent. For a synthetic ETF, the gap between the index and the fund comes down to the TER and the swap spread. Both depend on market financing conditions and on what it costs to build and run the product.
Our role as an issuer is to manage both efficiently and disclose them clearly, so investors can understand the principal costs associated with the exposure.
An efficient structure, delivered at a competitive cost, can help reduce performance drag for investors.
Basis point (bp): One basis point equals 1/100 of a percentage point. 1 bp = 0.01%; 100 bps = 1%.
Benchmark: A standard, usually an index, against which the performance of an investment portfolio can be measured.
Credit spread: The difference in yield between securities with similar maturity but different credit quality, often used to describe the difference in yield between corporate bonds and government bonds. Widening spreads generally indicate a deteriorating creditworthiness of corporate borrowers, while narrowing indicates improving.
Derivative: An investment instrument whose value is derived from the value of an underlying asset, index, rate or other financial instrument.
Dividend: A distribution of a company’s earnings to its shareholders, generally in the form of cash or additional shares.
Dividend yield: A ratio that shows how much a company or investment fund pays out in dividends relative to its share price.
Exchange traded fund (ETF): An investment fund that trades on a stock exchange and is designed to track the performance of a basket of securities, an index or another asset.
Exposure: The amount an investor stands to lose in an investment should the investment fail.
Index: A measure used to represent the performance of a market or a particular segment of a market. An index may also serve as a benchmark against which an investment portfolio’s performance is measured.
Investment style: The method or philosophy that an investment manager uses when selecting investments for a portfolio or strategy.
Passive investing: An investment approach that seeks to replicate the performance of a market index rather than outperform it. It is the opposite of active investing.
Physical replication: An ETF replication method in which the fund holds the underlying securities contained in the index it is seeking to track.
Swap: A derivative contract in which two parties exchange the returns or cash flows of different assets or indices according to agreed terms.
Synthetic replication: An ETF replication method that uses derivatives, typically swaps, to deliver the performance of an index rather than holding all the underlying securities directly.
Tax drag: The reduction in an investment’s return caused by taxes paid on income or capital gains.
Total expense ratio (TER): The annual cost of operating a fund, expressed as a percentage of its assets under management.
Tracking difference: The difference between the return delivered by a fund and the return of its benchmark index over a given period.
Tracking error: An indication of the expected divergence between the price behaviour of an investment or portfolio and its benchmark.
Withholding tax: Tax deducted at source from income payments, such as dividends, before the income is received by the investor.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.
Important information
Please read the following important information regarding funds related to this article.
- Derivatives may be used to help achieve the investment objective. This introduces other risks, in particular that a counterparty may not meet its contractual obligations.
- Shares can lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may fall as a result.
- The performance of the Sub-Fund is not expected to precisely match the performance of the index at all times and the deduction of fees and expenses means the Sub-Fund might deliver a lower total return than the index.
- High exposure to a particular country or geographical region carries a higher level of risk than a more broadly diversified portfolio.
- Securities could become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
- Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
- Swap returns are subject to the returns of the index or reference assets. Valuations of investments, the index tracked or replicated, or the financial instruments used to track or replicate the index may, in certain circumstances, only be available from a limited number of market participants who may also act as counterparties to these transactions. This means valuations can be subjective, and different sources may provide significantly different values.