Key takeaways:
- Global equities broadly declined in September, led lower by Europe, China, and Australia as rising bond yields and higher oil prices weighed on sentiment. Strength in AI-related technology shares supported U.S. large-cap and tech-heavy Asian benchmarks, while small caps and most non-technology sectors lagged.
- Global government bonds fell as sovereign yields marched higher across major markets, with long-dated yields reaching multi-decade highs. Corporate bonds also declined as credit spreads widened, particularly in high yield.
- The higher bond-yield backdrop dominated the market narrative alongside higher oil prices and persistent geopolitical uncertainty. Meanwhile, continued enthusiasm for the AI theme supported technology stocks to the exclusion of nearly all other sectors, resulting in weaker market breadth beneath the surface.
Market overview
Global equities were broadly lower in September as rising bond yields, higher oil prices, and a stronger U.S. dollar weighed on most major markets. The MSCI World Index fell 1.2% in U.S. dollar terms but remained up 12.1% year to date. U.S. large-cap stocks and tech-heavy benchmarks in parts of Asia outperformed, while European equities, China, and Australia lagged. Global government bonds sold off as yields rose across major markets, with long-dated bond yields reaching multi-decade highs. Global corporate bonds also declined, with widening credit spreads – particularly in high yield – adding to the pressure from higher government yields.
Oil prices rose amid continued U.S.-Iran tensions and uncertainty surrounding Middle East supply. Brent crude advanced more than 10% and traded above $100 per barrel during the month. The U.S. Dollar Index rose 2.0% as U.S. yields climbed and investors reassessed the outlook for Federal Reserve (Fed) policy. Gold fell more than 6%, giving back some of the prior month’s gain, as higher bond yields and dollar strength weighed on the precious metal.
U.S. and Asia led global equity markets, while Europe and Australia lagged
AI-related technology stocks outperformed in September.
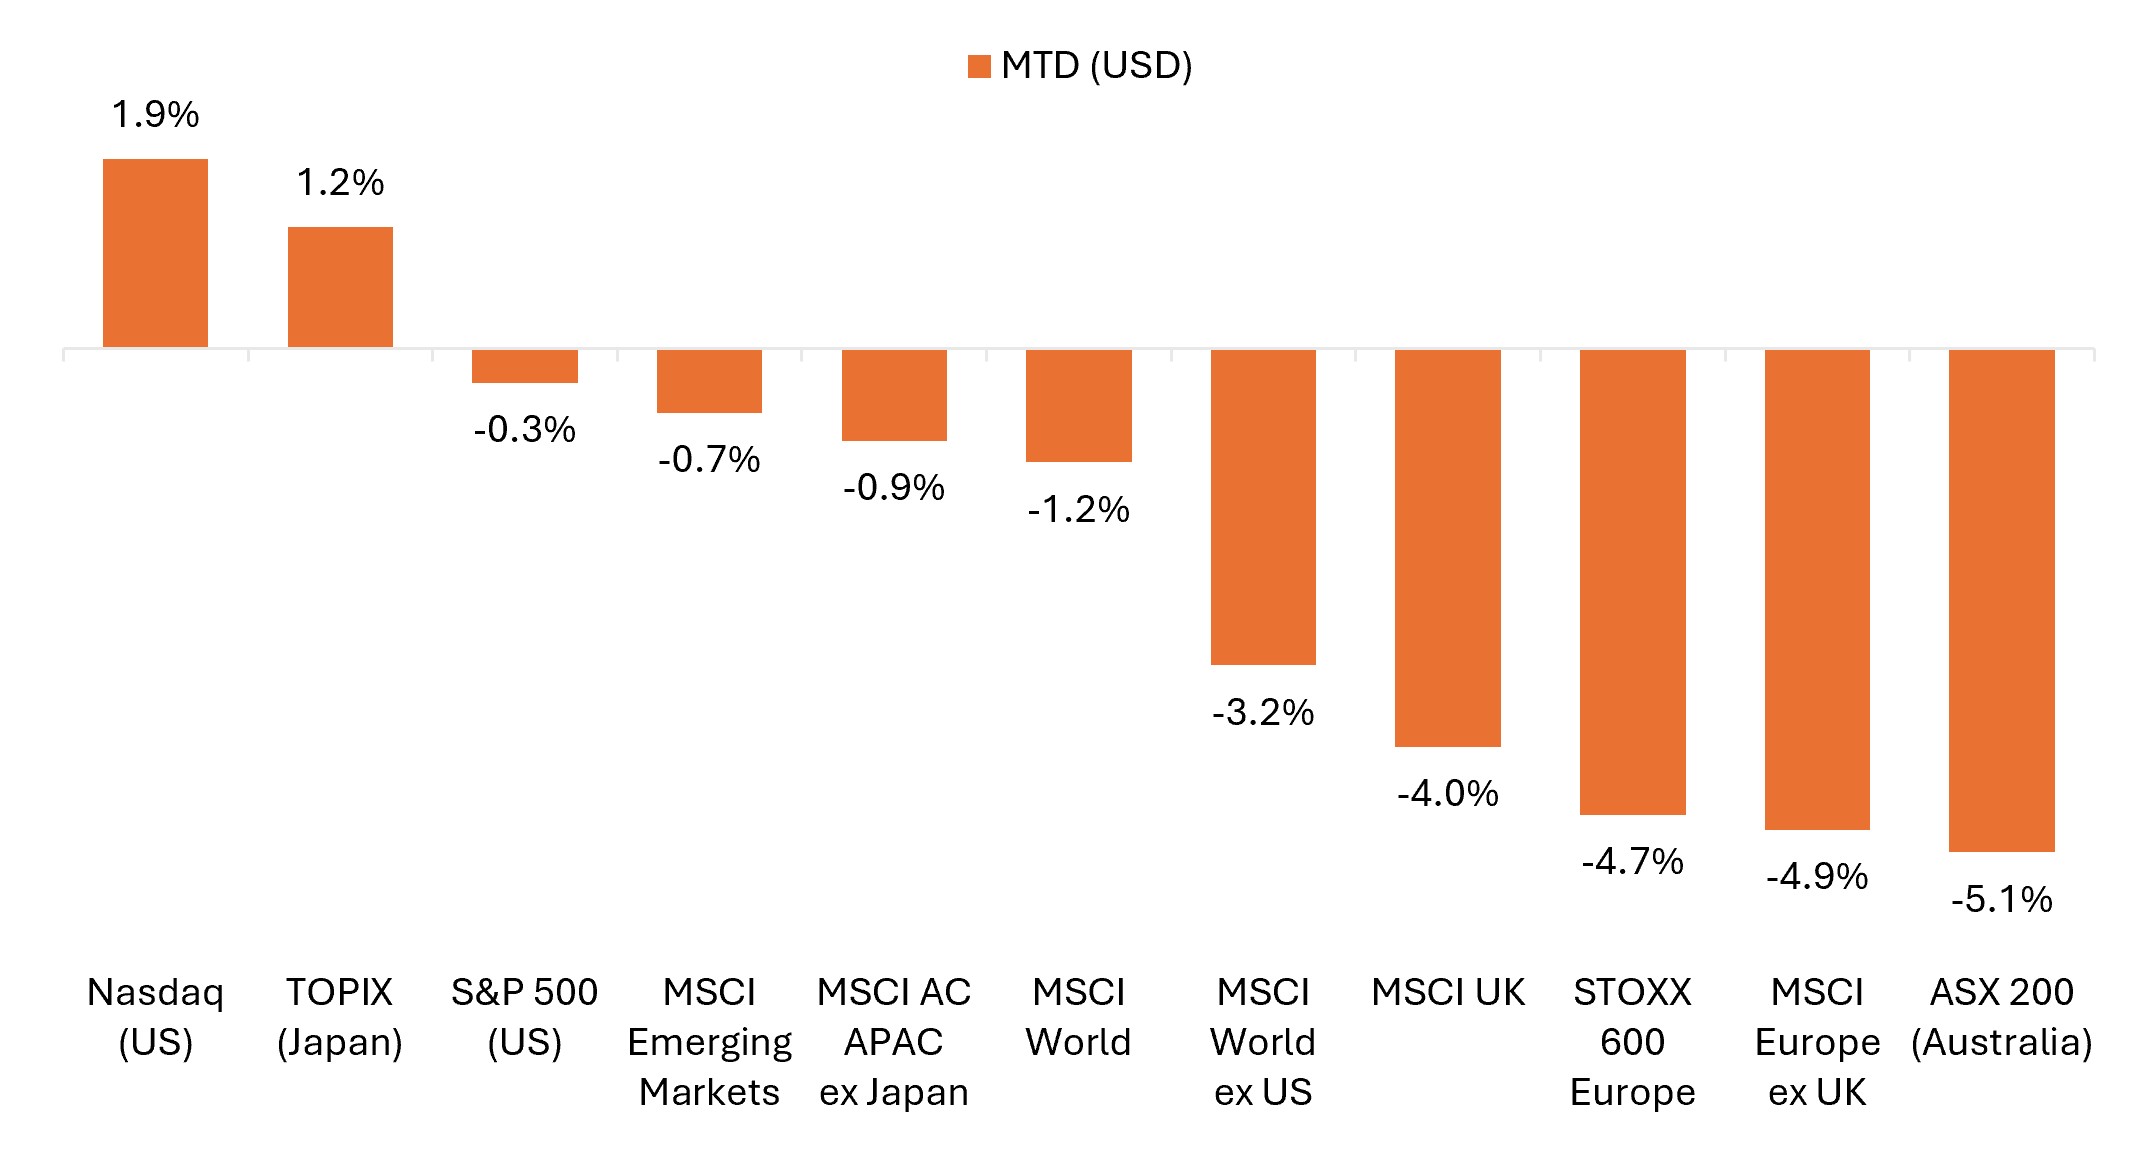
Source: Bloomberg, data from 31 August 2026 to 30 September 2026. Represents index total returns in U.S. dollar terms. Past performance is no guarantee of future results.
Key themes that mattered for markets
- Rising global bond yields dominated the market narrative in September: The combination of higher energy prices, mounting fiscal deficits, heavy AI-related debt issuance, and stronger-than-expected economic data pushed government bond yields higher across major markets. The yield on the Bloomberg Global Treasuries Index topped 4% for the first time since 2007, while long-dated U.S. Treasury yields reached their highest levels since 2002. The higher rate backdrop increased concerns about borrowing costs and stock valuations, although AI-related stocks and mega-cap technology companies helped support equity markets.
Global government bond yields reached multi-decade highs
The yield on the Bloomberg Global Treasuries Index topped 4% for the first time since 2007.
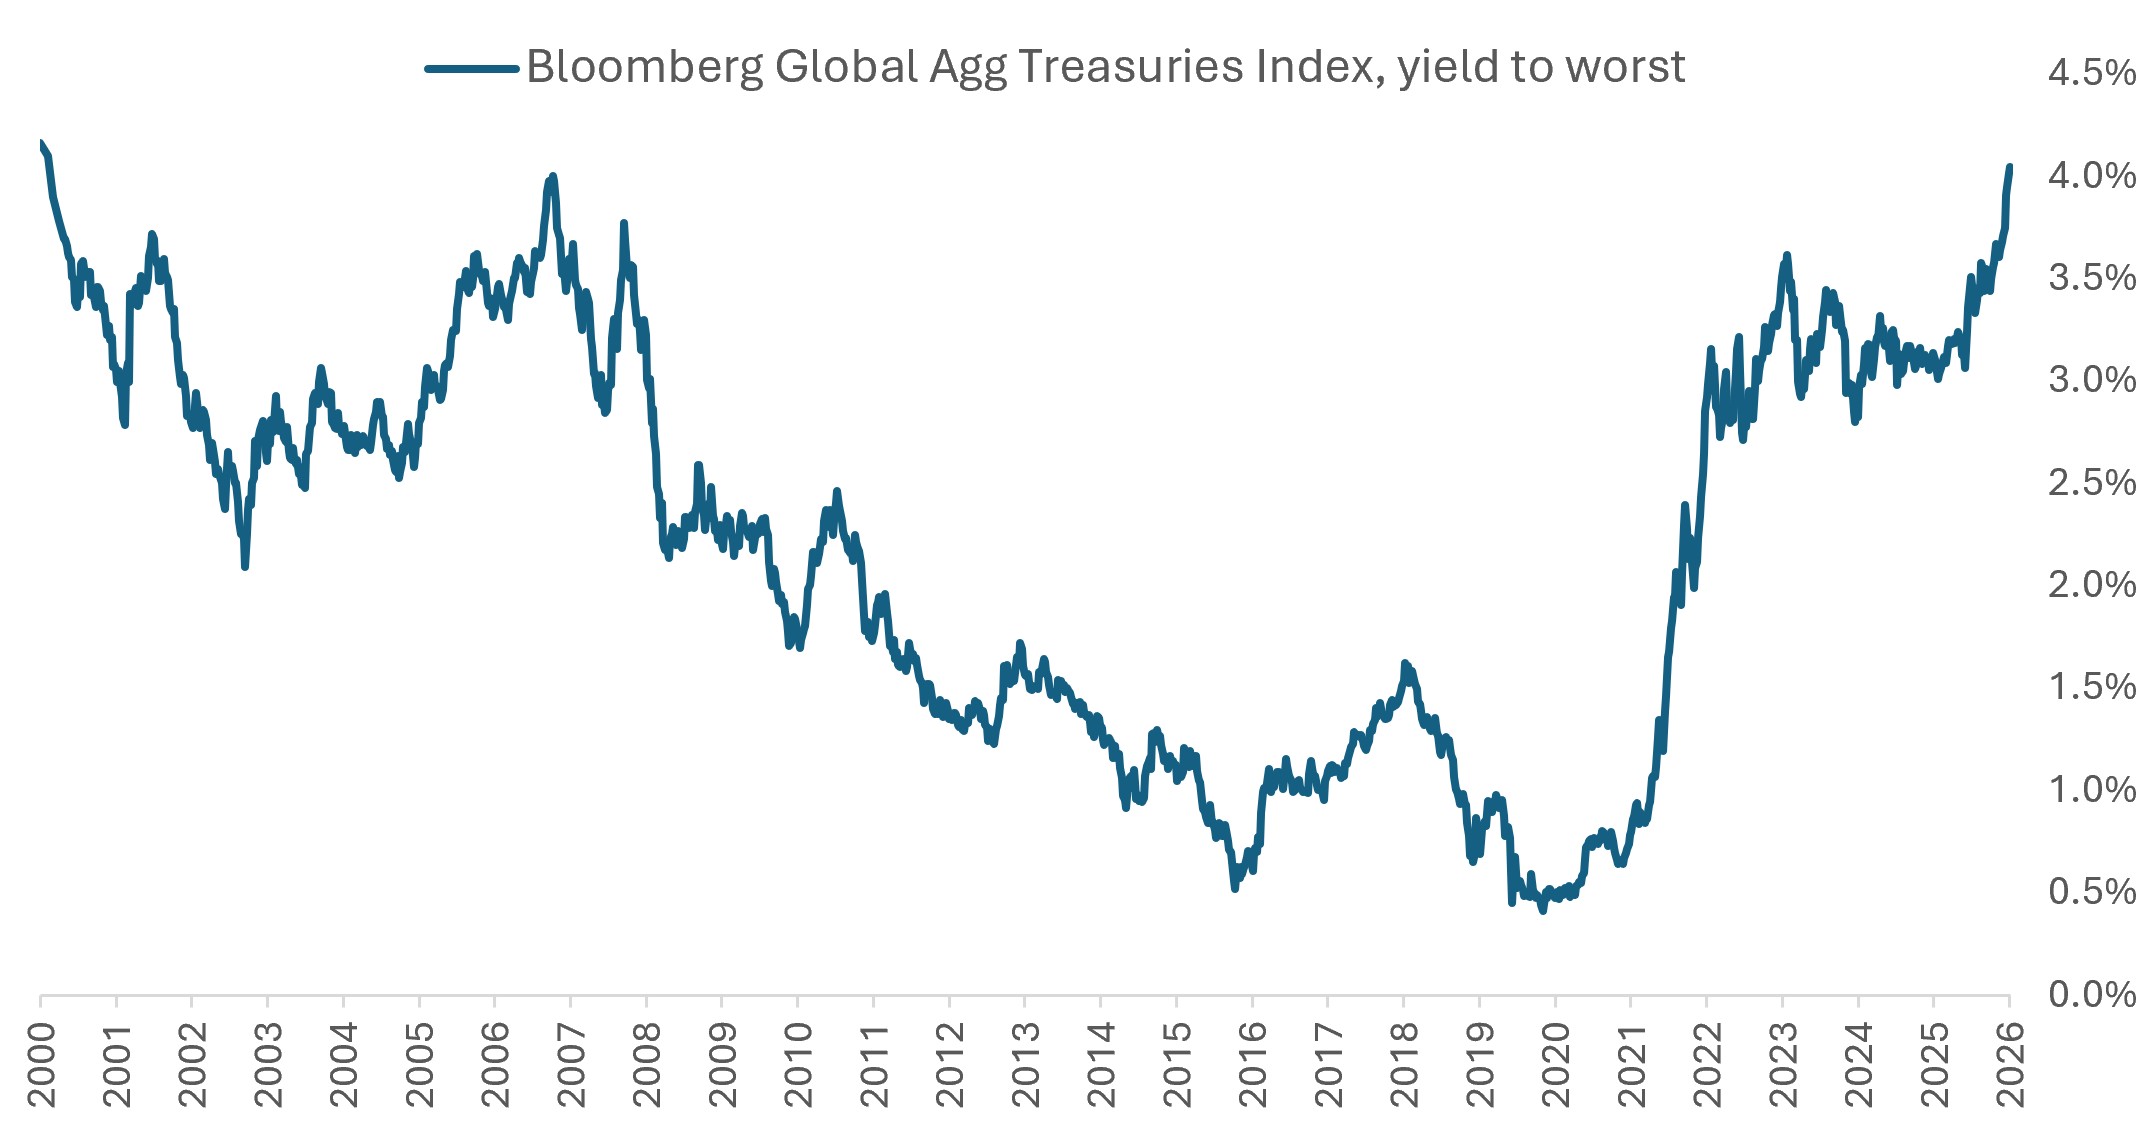
Source: Bloomberg, data from 30 September 2000 to 30 September 2026. The Bloomberg Global Agg Treasuries Index tracks fixed-rate, local currency government debt from investment-grade developed and emerging markets.
- AI-related technology stood out as market leadership narrowed: The AI theme continued to support semiconductors, hyperscalers, and other AI-linked technology stocks, while equal-weight benchmarks, small caps, and many non-technology sectors came under pressure amid higher crude prices and rising bond yields. The AI narrative also evolved, with agentic AI rollouts sparking disruption concerns while reinforcing demand for chips, memory, cloud infrastructure, and optical networking equipment. Calls from several AI leaders to slow the pace of frontier-model development highlighted growing safety concerns, though strong AI investment and adoption trends continued to support the sector.
- Higher oil prices and geopolitical uncertainty remained market headwinds: The U.S.-Iran conflict remained unresolved, with the seven-month war oscillating between military flare-ups and diplomacy efforts that yielded little tangible progress. Brent crude jumped more than 10% on the month and briefly rose above $100 per barrel. Elevated energy prices, particularly diesel and other fuels, reinforced inflation concerns, contributed to the rise in global bond yields, and posed an additional challenge for energy-importing economies.
- Economic resilience defied rate fears: Global Purchasing Managers’ Index readings largely surprised to the upside in September. U.S. business activity accelerated to its strongest level in more than five years, the Eurozone composite PMI reached a more than three-year high, and manufacturing activity across much of Asia remained broadly in expansion territory, supported by strong exports and continued demand for AI-related technology inputs.
United States
U.S. equities were mixed in September as AI-related technology strength offset broad weakness across most sectors. The S&P 500 Index declined modestly, while the tech-heavy Nasdaq Composite advanced. Growth outperformed value, and large-cap stocks significantly outpaced small caps. Market breadth narrowed sharply, with the equal-weight S&P 500 lagging its cap-weighted counterpart by 4.5 percentage points as higher bond yields weighed on rate-sensitive and cyclical areas of the market.
- The S&P 500 declined 0.3% in September but remained up 12.7% year to date.
- The S&P 500 Equal Weight Index fell 4.8%, highlighting the lack of market breadth as gains across large-cap tech masked broader weakness beneath the surface.
- The Nasdaq Composite rose 1.9%, extending its year-to-date advance to 16.1%, as semiconductor, AI infrastructure, and select mega-cap technology stocks outperformed.
- The small-cap Russell 2000 Index declined 5.3%, its steepest monthly decline in more than a year, though it remained up 13.9% year to date.
- Growth outperformed value among large-cap companies. The Russell 1000 Growth Index advanced 2.2%, while the Russell 1000 Value Index fell 3.1%. Among small- and mid-cap companies, the Russell 2500 Growth and Value indexes declined 4.1% and 5.4%, respectively.
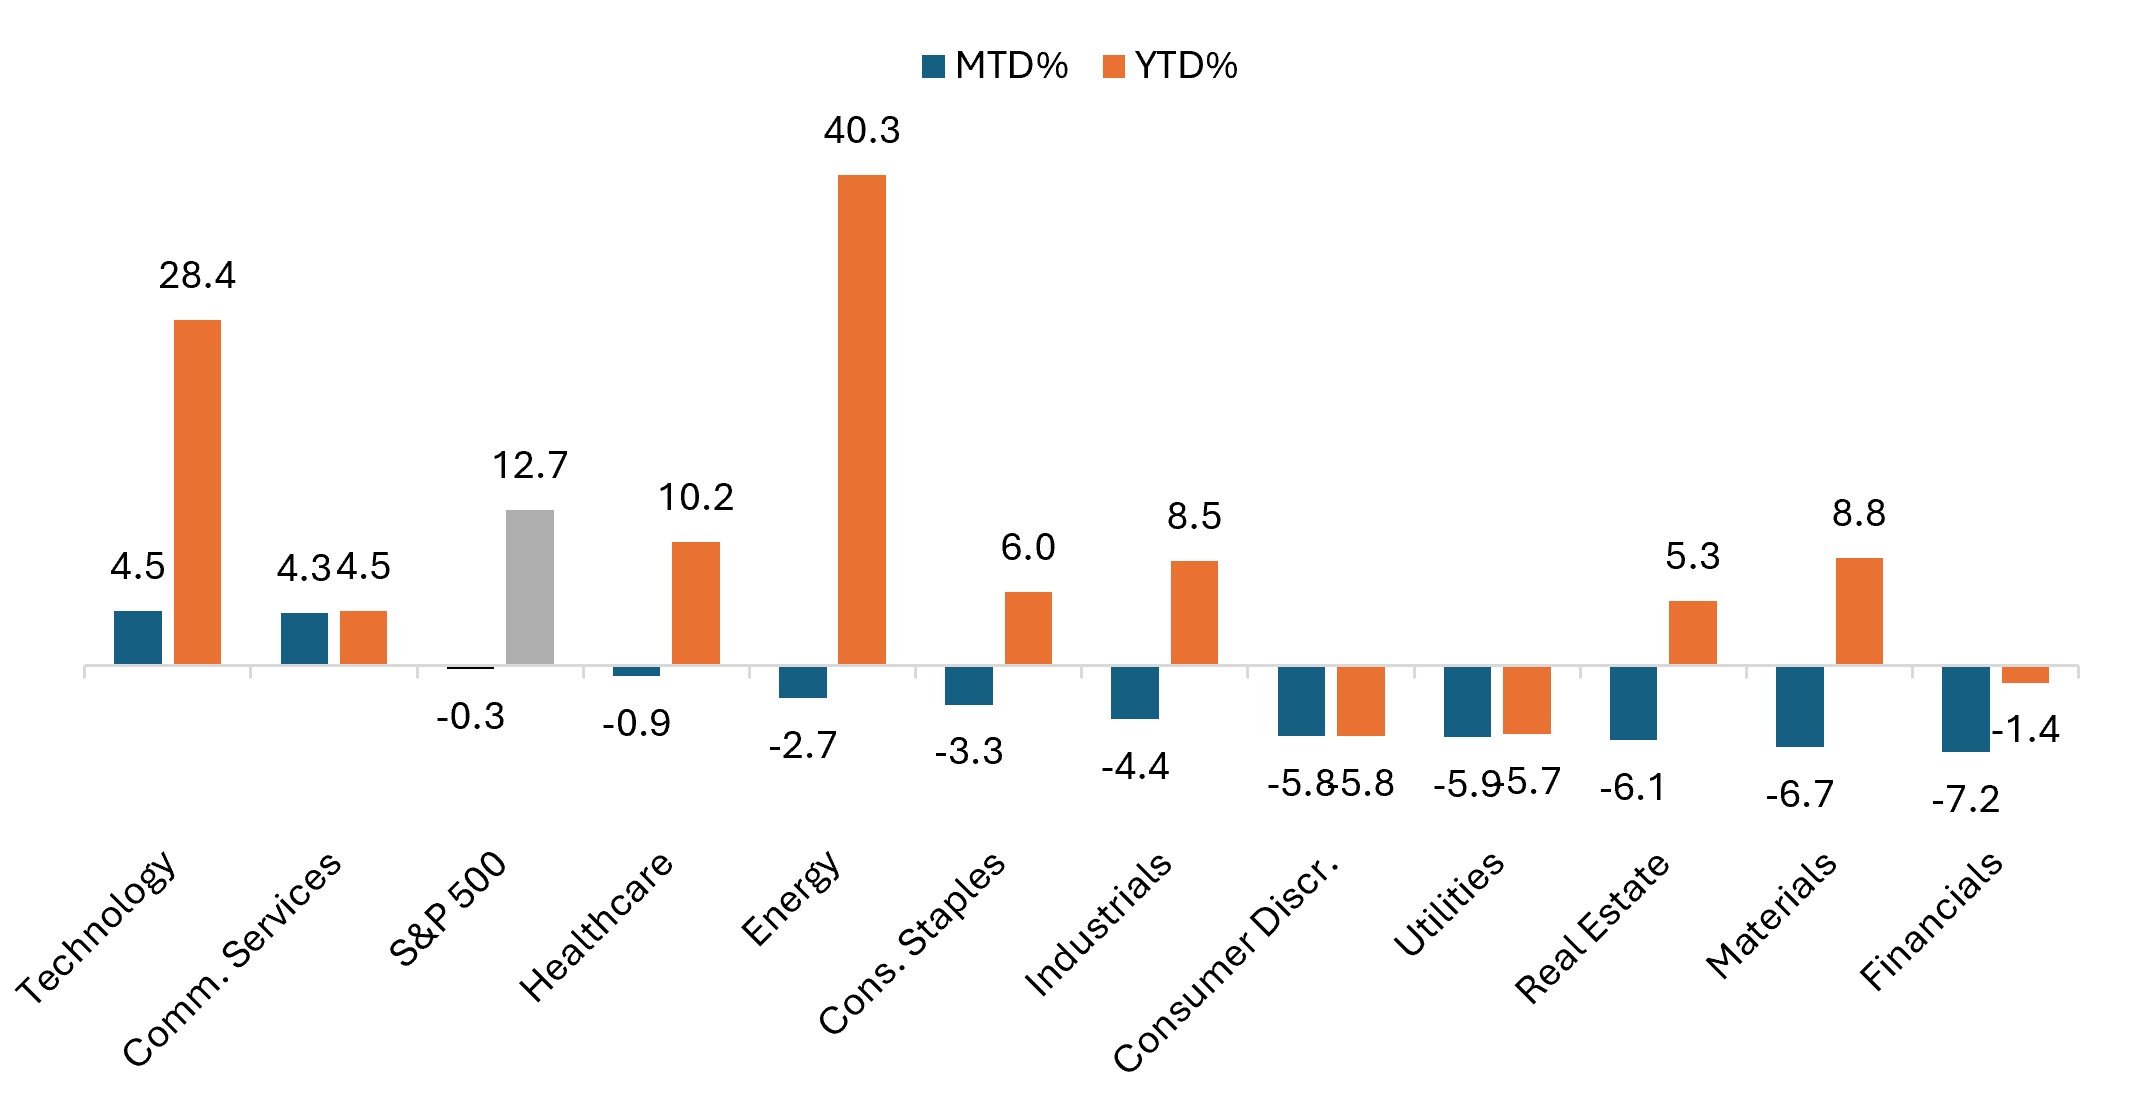
- Information Technology and Communication Services were the only S&P 500 sectors to advance, gaining 4.5% and 4.3%, respectively. All other sectors declined, led by Financials (-7.2%), Materials (-6.7%), and Real Estate (-6.1%).
Tech and Communication Services posted solid gains, while all other sectors fell
S&P 500 sector performance (September and year to date)
Source: Bloomberg, as of 30 September 2026. Past performance is no guarantee of future results.
U.S. economic data were largely resilient, supported by stronger labor market, consumer spending, and Purchasing Managers’ Index (PMI) readings:
- The Fed raised its benchmark rate by 25 basis points (bps) to 3.75%-4.00%, marking its first rate increase since 2023. Treasury yields moved higher and the yield curve flattened as markets priced in at least one additional rate hike by year end. However, cooler-than-expected PCE inflation data released at month end eased concerns about the need for an immediate follow-up move, with market-implied odds of an October rate hike falling to around 40%, down from roughly 70% just two days earlier.
- Labor market data came in stronger than expected. Nonfarm payrolls increased by 162,000 in August, ahead of consensus estimates for roughly 90,000, while June and July payrolls were revised higher by a combined 55,000. The unemployment rate held steady at 4.1%.
- Inflation remained above the Fed’s 2% target but showed signs of moderation late in the month. The Consumer Price Index (CPI) rose 0.4% month over month and 3.4% year over year in August, while core CPI increased 0.3% during the month and 2.4% year over year (down from 2.5% prior). Producer prices accelerated, with the Producer Price Index (PPI) rising 0.4% during the month and 5.4% year over year (up from 4.7% prior). However, August core PCE inflation surprised to the downside, slowing to 3.0% year over year from 3.3% in July.
- Consumer spending rebounded, while confidence remained weak. Retail sales rose 1.2% in August, exceeding expectations and reversing July’s decline. However, consumer confidence fell to 81.9 in September, its lowest reading since 2014, as concerns over inflation and higher energy prices weighed on sentiment.
- Business activity accelerated, led by strength in services, alongside rising cost pressures. The S&P Global flash U.S. composite Purchasing Managers’ Index (PMI) climbed to 58.4 in September (from 56.0 in August), its highest level since July 2021. Services activity remained the primary driver, coming in at 58.7 (from 56.5 prior). However, input costs also jumped the most since October 2022.
Europe
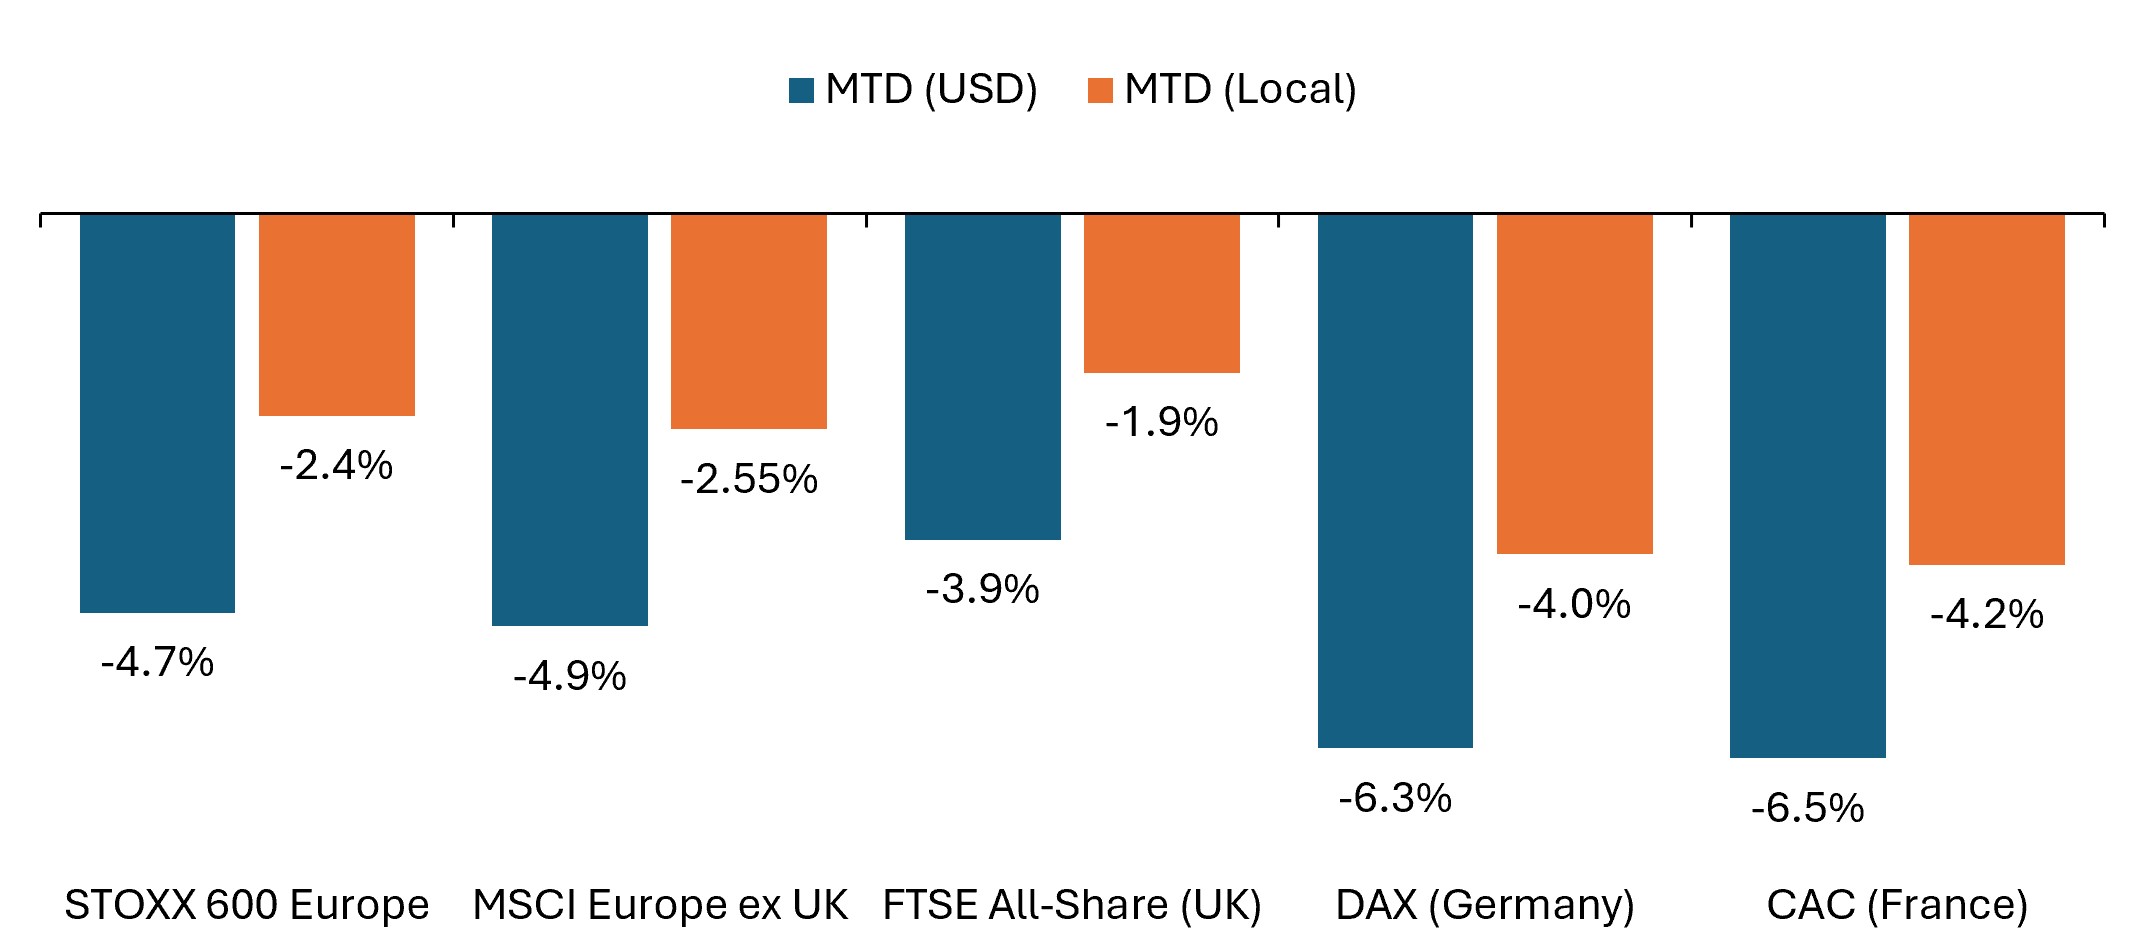
Eurozone equities declined in September as higher energy prices, rising government bond yields, and political and fiscal uncertainty outweighed resilient economic data. The STOXX Europe 600 Index fell 2.4% in euro terms and 4.7% in U.S. dollars, snapping a five-month winning streak. The MSCI Europe ex United Kingdom Index fell 2.6% in euro terms and 4.9% in U.S. dollars. Germany and France led the major-market declines, while continued strength in energy and select technology stocks helped offset weakness elsewhere.
- The European Central Bank (ECB) raised its key policy rates by 25 bps, as expected. Policymakers highlighted upside risks to inflation, particularly from higher energy prices, while also acknowledging downside risks to economic growth.
- Inflation moved higher in August. Headline eurozone CPI rose to 3.2% year over year from 2.9% in July but came in slightly below Eurostat’s flash estimate of 3.3%. Energy inflation accelerated to 14.3%, its highest level since January 2023, while core inflation edged down to 2.4% from 2.5%.
- Economic data pointed to continued resilience across the eurozone. The flash composite PMI rose to 53.1 in September (from 52.0 in August), marking a 41‑month high, as services activity continued to expand despite higher input costs. German factory orders also rose for a second consecutive month.
UK equities held up somewhat better than continental Europe, helped in part by a larger Energy weighting. The MSCI United Kingdom Index fell 2.0% in sterling terms and 4.0% in U.S. dollars, while the FTSE All-Share Index declined 1.9% in sterling and 3.9% in U.S. dollars. UK gilt yields also rose sharply amid the global bond selloff, with 30-year yields reaching their highest level since 1998 as fiscal uncertainty ahead of October’s budget added to upward pressure on borrowing costs.
- The Bank of England (BoE) left its policy rate unchanged at 3.75%, as expected. The decision was split 6-3, with three policymakers favoring a rate hike.
- UK inflation accelerated to 3.1% year over year in August from 2.9% in July, marking the first reading above 3% since March as higher energy prices pushed inflation higher.
- Labor market data pointed to further softening. Employment fell by 26,000 in August, while the unemployment rate remained unchanged at 4.9% in the three months to July. Wage growth continued to moderate.
- Business activity remained in expansion territory despite signs of moderation. The flash composite PMI fell to 51.7 in September (from 52.5 in August), a three-month low, as higher energy costs and budget concerns weighed on activity.
- Consumer data improved in August. Retail sales volumes rose 0.5%, rebounding from a decline in July, while GfK’s Consumer Confidence Index rose to -13 in September (up one point from August’s reading), its highest level in over two years.
France and Germany led the declines, while Energy strength helped cushion UK losses
A stronger dollar amplified declines in U.S. dollar terms
Source: Bloomberg, data from 31 August 2026 to 30 September 2026. Past performance is no guarantee of future results.
Within the STOXX 600 Index – comprising companies from 17 countries across developed Europe including the UK – most sectors declined, with Energy and Technology the only sectors to post gains in September.
- Energy (+3.0% in euro terms) was the strongest-performing sector, supported by higher crude oil and refined fuel prices.
- Technology (+2.0%) rose as semiconductor and AI infrastructure companies benefited from continued demand for AI and data-center investment.
- Banks (-1.0%) declined, while Personal Care, Drug & Grocery (-1.3%), Chemicals (-1.5%), Travel & Leisure (-1.6%), and Utilities (-1.7%) posted comparatively modest losses.
- Health Care (-3.0%), Industrials (-3.1%), Food, Beverage & Tobacco (-4.0%), Media (-4.3%), Insurance (-4.6%), and Telecommunications (-4.8%) posted larger declines.
- Construction & Materials (-5.9%), Retail (-6.4%), Basic Resources (-6.6%), Financial Services (-7.1%), Real Estate (-7.1%), and Autos & Parts (-8.1%) were the weakest-performing sectors.
Asia Pacific
Japanese equities were mixed in September as strength in semiconductor and other technology-related companies supported the Nikkei 225. The TOPIX declined 0.3% in yen terms but rose 1.2% in U.S. dollar terms, while the Nikkei gained 1.2% in local currency terms and 2.8% in U.S. dollars. The yen strengthened against the U.S. dollar during the month, while the Bank of Japan’s rate increase and rising government bond yields created a more challenging backdrop for rate-sensitive companies.
- The Bank of Japan (BoJ) raised its policy rate by 25 bps to 1.25%, as expected, taking rates to their highest level in more than three decades. However, the decision included two dissenting votes for a hold, leading some investors to view the outcome as less hawkish than anticipated.
- Inflation remained near the BoJ’s target. Core CPI rose 1.7% year over year in August, easing slightly from 1.8% in July and coming in below consensus expectations, while wholesale inflation remained elevated due to higher fuel costs.
- Japanese business activity slowed but remained in expansion territory. Japan’s flash composite PMI fell to a four-month low of 52.5 in September (down from 53.5 in August) as manufacturing moderated to 54.1 (from 54.9) and services activity eased to 51.6 (from 52.5), though both continued to signal economic expansion.
- The yen remained in focus throughout the month. The yen finished September 1.5% higher against the U.S. dollar, although gains moderated after the BoJ’s rate increase was perceived as less hawkish than expected. Meanwhile, ongoing discussions between U.S. and Japanese officials fueled speculation that authorities could take further steps to support the currency if needed.
Equities across Asia Pacific ex Japan declined in September as gains in Taiwan and South Korea were offset by weakness in China, Australia, and several Southeast Asian markets. The MSCI AC Asia Pacific ex Japan Index fell 0.9% in U.S. dollar terms but remained up 24.0% year to date. Higher oil prices and rising global yields weighed on energy-importing economies, while AI-related semiconductor demand supported tech-heavy markets. The MSCI China Index fell 4.6% in U.S. dollar terms as softness in retail sales, fixed investment, and the property sector outweighed continued strength in exports and AI-related manufacturing. Australia’s S&P/ASX 200 Index declined 2.1% in local currency terms and 5.1% in U.S. dollar terms as the Australian dollar weakened substantially against the greenback. The Reserve Bank of Australia raised its cash rate by 25 bps to 4.60%, as expected, with policymakers citing elevated inflation and economic resilience, while maintaining a data-dependent stance toward future policy decisions.
Emerging Markets
Emerging market equities declined modestly in September as a stronger U.S. dollar, higher global yields, and elevated oil prices offset strength in several technology-oriented Asian markets. The MSCI Emerging Markets Index fell 0.7% in U.S. dollar terms but remained up 23.5% year to date. Performance diverged sharply by country, with Taiwan, South Korea, Brazil, and Poland advancing while India, China, South Africa, and Turkey posted significant declines. Performance figures below reference MSCI country indexes reported in U.S. dollar terms.
- Taiwan rose 3.9% and South Korea gained 2.2%, with gains across semiconductors and memory chip manufacturers.
- India declined 7.1% as higher oil prices, currency pressure, and tighter global financial conditions weighed on sentiment. Indonesia fell 7.6%, while Malaysia (-3.4%), Thailand (-3.4%), and the Philippines (-4.0%) also declined.
- In EMEA, South Africa fell 9.0% as weakness in precious metals and a risk-off backdrop offset support from other commodity exposures. Turkey declined 8.8% amid liquidity strains and heightened scrutiny of parts of the domestic fund industry, while Poland bucked the trend with a 1.1% gain.
- Performance across Latin America was mixed. The MSCI Emerging Markets Latin America Index declined 0.3%, with a 3.2% gain in Brazil offset by weakness in Argentina (-7.9%), Chile (-7.3%), and Mexico (-6.8%).
- Monetary policy paths remained divergent. Brazil lowered its benchmark rate for a fifth consecutive meeting, while South Africa raised its policy rate amid inflation concerns.
Fixed Income
Global government bonds fell in September as sovereign yields marched higher across major markets. The selloff was most pronounced in U.S. Treasuries, while government bonds in the UK, Germany, and Japan also declined amid resilient economic data, elevated energy prices, and expectations that interest rates could remain higher for longer.
- The Bloomberg Global Treasury Index fell 1.4% in U.S. dollar-hedged terms and was down 1.6% year to date.
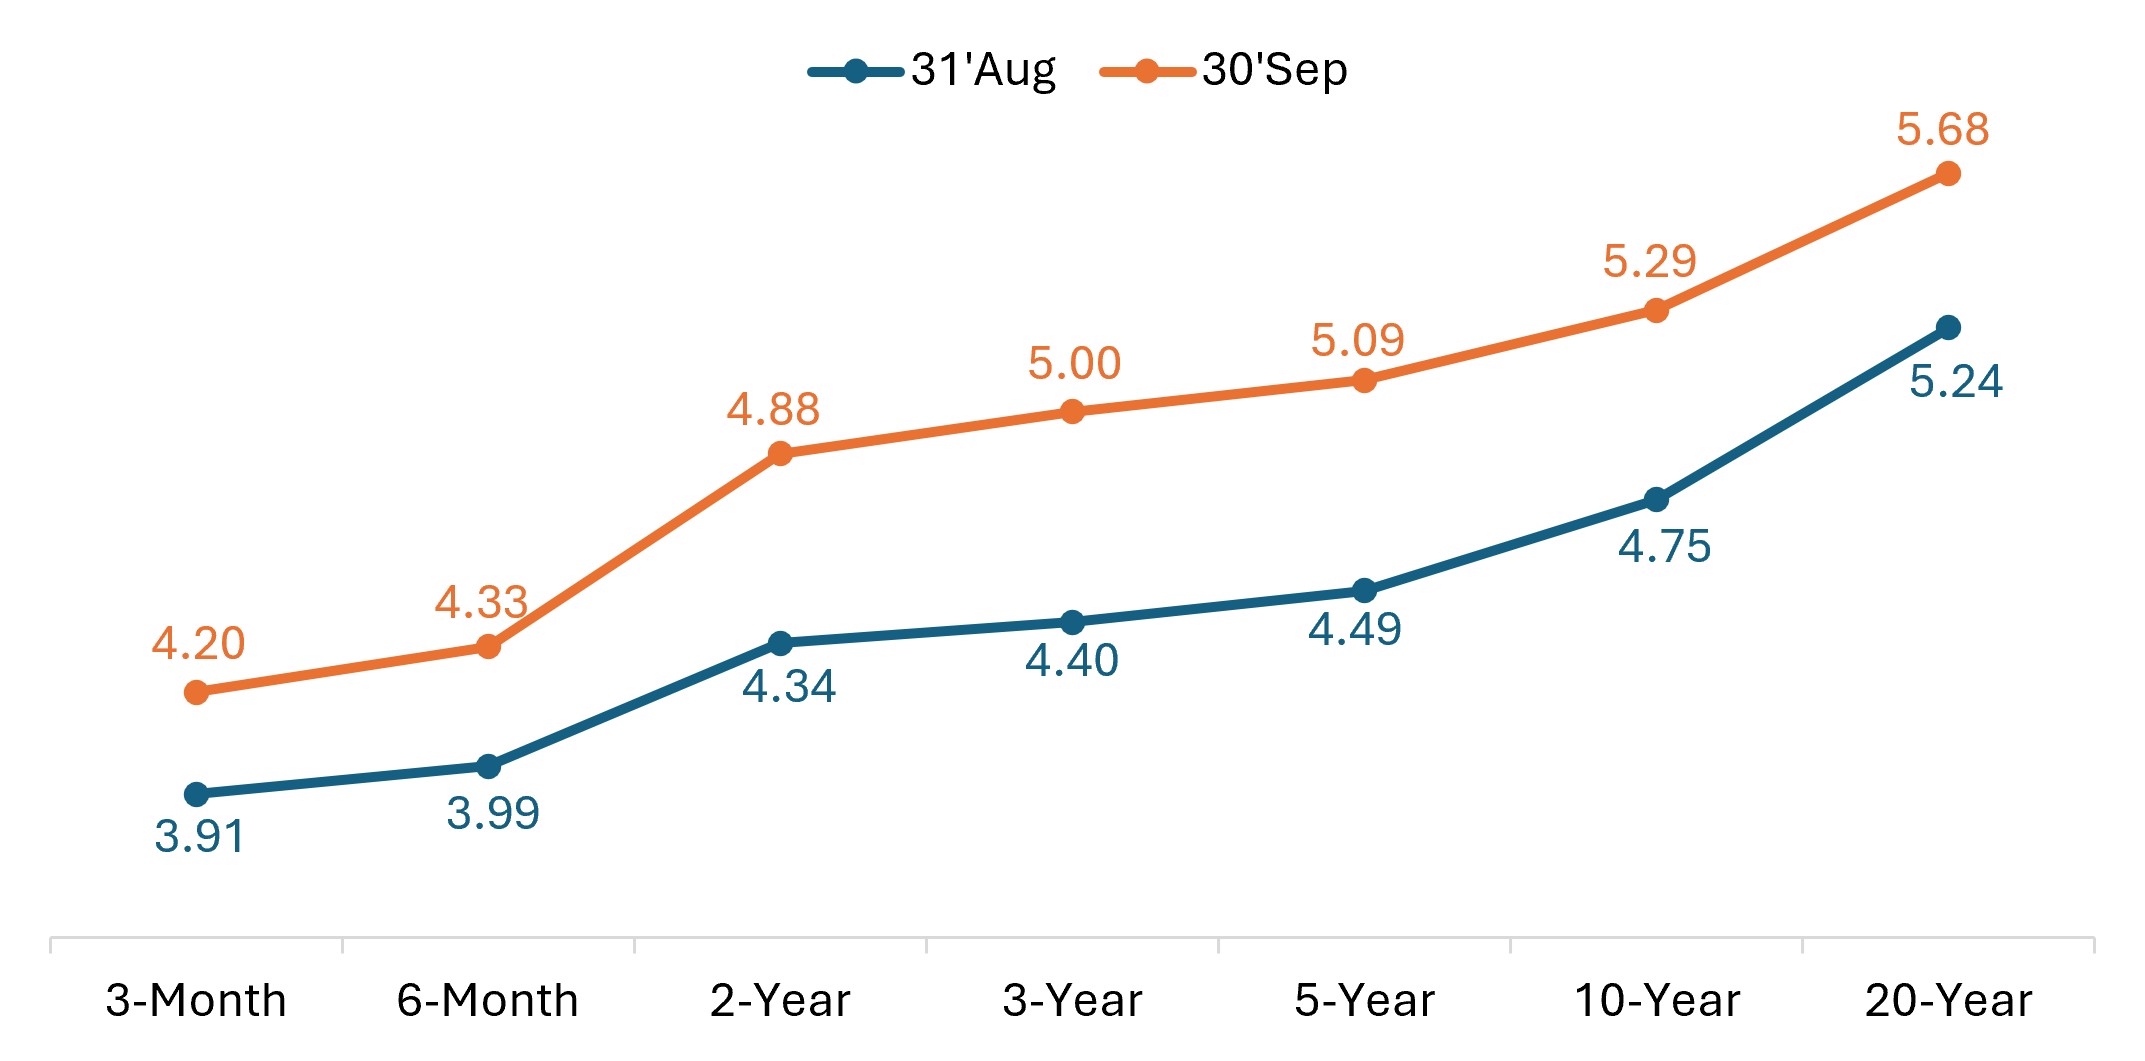
- The U.S. 10-year Treasury yield rose 54 bps to 5.29%, briefly topping 5.3% for the first time since 2002.
- The U.S. Treasury curve shifted sharply higher, with moves most pronounced in the belly of the curve as both 3-year and 5-year yields rose 60 bps during the month. The spread between 10-year and 2-year Treasury yields ended the month little changed at 41 bps, although it briefly narrowed to roughly 20 bps before re-steepening late in the month.
U.S. Treasury yield curve (month-on-month change)
Source: Bloomberg, as of 30 September 2026. Past performance is no guarantee of future results.
- In Europe, UK government bonds came under pressure as the yield on the 10-year gilt rose approximately 36 bps to 5.42%, while the 30-year climbed to 5.95%, approaching 6% for the first time since 1998.
- German sovereign bonds were also broadly weaker. The German 10-year bund yield increased approximately 26 bps to 3.59%, its highest level in more than 15 years.
- Japanese government bonds (JGBs) posted more modest monthly declines, as the yield on the 10-year JGB rose approximately 11 bps to 3.06%, ending the month at levels last seen in 1996.
Emerging market hard-currency debt declined as higher U.S. Treasury yields weighed on returns.
- The J.P. Morgan EMBI Global Diversified Index, which tracks U.S. dollar-denominated debt issued by emerging market governments, fell 3.3% in September.
- Emerging market sovereign spreads were little changed, widening by approximately 1 bp to 218 bps over U.S. Treasuries.
Spread sectors declined in September, with both high yield and investment-grade corporate bonds posting steep monthly declines. Investment-grade spreads widened only modestly, while high-yield spreads moved materially wider amid weaker risk sentiment and elevated issuance across credit markets.
- The Bloomberg Global Aggregate Corporate Index fell 2.1% in U.S. dollar-hedged terms, while the Bloomberg Global High Yield Index declined 2.5% on a hedged basis.
- Global investment-grade option-adjusted spreads (OAS) widened by approximately 5 bps to 85 bps, while global high-yield spreads widened by approximately 42 bps to 314 bps.
- US. investment-grade corporate bonds, as measured by the Bloomberg U.S. Corporate Index, declined 2.7%, while the Bloomberg U.S. Corporate High Yield Index fell 2.5%.
- U.S. investment-grade spreads widened by approximately 2 bps to 80 bps, while U.S. high-yield spreads widened by approximately 50 bps to 311.
- In securitized markets, the Bloomberg U.S. Securitized Index, which includes mortgage-backed securities (MBS), commercial mortgage-backed securities (CMBS), and asset-backed securities (ABS), declined 3.2%. Composite spreads widened by approximately 12 bps, although ABS spreads narrowed.
Central Bank Watch
September saw several major central banks shift to a more hawkish stance amid renewed inflation concerns tied in part to higher energy prices. The most closely watched decision came from the Federal Reserve, which delivered its first rate increase since July 2023. While the Bank of Canada and Bank of England left rates unchanged, the ECB, Fed, BoJ, and RBA each raised policy rates by 25 bps. Policymakers generally emphasized upside inflation risks and maintained a readiness to tighten further if necessary.
- Bank of Canada (Sep. 2): The BoC left its overnight lending rate unchanged at 2.25% for a seventh consecutive meeting, in line with expectations. Policymakers acknowledged ongoing economic resilience but maintained that current policy settings remain appropriate while they assess incoming inflation and growth data.
- European Central Bank (Sep. 10): The ECB raised its key policy rates by 25 bps, as expected, lifting the deposit rate to 2.50%. While officials cited upside risks to inflation, particularly from higher energy prices, President Lagarde also noted increasing downside risks to economic growth.
- U.S. Federal Reserve (Sep. 16): The Fed raised its benchmark policy rate by 25 bps to a range of 3.75%-4.00% in a unanimous 12-0 vote, marking its first rate increase since 2023. Chair Kevin Warsh struck a relatively hawkish tone, with markets pricing in expectations for at least one additional rate hike by the end of this year.
- Bank of England (Sep. 17): The BoE left its policy rate unchanged at 3.75% in a 6-3 split vote, with three officials favoring a rate hike. Separately, the central bank announced a slowdown to its quantitative-tightening strategy, including a six-month pause in bond sales and an outright halt to sales of long-dated gilts.
- Bank of Japan (Sep. 18): The BoJ raised its policy rate by 25 bps to 1.25%, taking rates to their highest level in more than three decades. However, the split 7-2 vote included two dissents in favor of holding rates steady, with the yen weakening as investors pared expectations for the pace of further rate increases.
- People’s Bank of China (Sep. 21): China left rates unchanged for a sixteenth consecutive meeting, holding its one-year and five-year loan prime rates at 3.00% and 3.50%, respectively.
- Reserve Bank of Australia (Sep. 29): The RBA raised its benchmark rate by 25 bps to 4.60% in a move that was widely expected. Policymakers maintained a hawkish tone, citing elevated inflation and a still-resilient labor market, while signaling they are prepared to tighten policy further if inflationary pressures persist.
- Other central banks: Among other notable policy decisions, New Zealand (Sep. 2) raised its official cash rate by 25 bps to 2.75%, marking a second consecutive increase. Brazil (Sep. 16) lowered its benchmark Selic rate by 25 bps for a fifth consecutive meeting ahead of October’s presidential election, bringing the cumulative easing since March to 125 bps. South Africa (Sep. 23) hiked its policy rate by 25 bps to 7.25%. Norway (Sep. 24) raised its policy rate by 25 bps to 4.50%, as expected, and indicated that another increase remains possible. Meanwhile, Switzerland (Sep. 24) left its policy rate unchanged at 0.0% with inflation at 0.8% in August and well within the central bank’s target range.
- Looking ahead: October’s policy calendar is back-end loaded, with rate decisions scheduled for the Bank of Canada (Oct. 28), Federal Reserve (Oct. 28), European Central Bank (Oct. 29), and Bank of Japan (Oct. 30). Markets will be closely watching whether policymakers continue to emphasize upside inflation risks following September’s broadly hawkish tone.
Key events on tap in October
- Oct. 1 – Global Manufacturing PMIs (September, final)
- Oct. 2 – Eurozone Consumer Price Index (September, preliminary)
- Oct. 2 – U.S. Nonfarm Payrolls, Unemployment Rate (September)
- Oct. 5 – Global Services and Composite PMIs (September, final)
- Oct. 14 – U.S. Consumer Price Index (September)
- Oct. 16 – Eurozone Consumer Price Index (September, final)
- Oct. 19 – China September Activity Data (Industrial Production, Retail Sales)
- Oct. 21 – UK Consumer Price Index (September)
- Oct. 23 – Global PMIs (October, flash estimate)
- Oct. 28 – Bank of Canada (BoC) Rate Decision
- Oct. 28 – U.S. Federal Reserve (Fed) Rate Decision
- Oct. 29 – European Central Bank (ECB) Rate Decision
- Oct. 29 – U.S. Gross Domestic Product (Q3, advance estimate)
- Oct. 30 – Eurozone Gross Domestic Product (Q3, preliminary)
- Oct. 30 – Bank of Japan (BoJ) Rate Decision
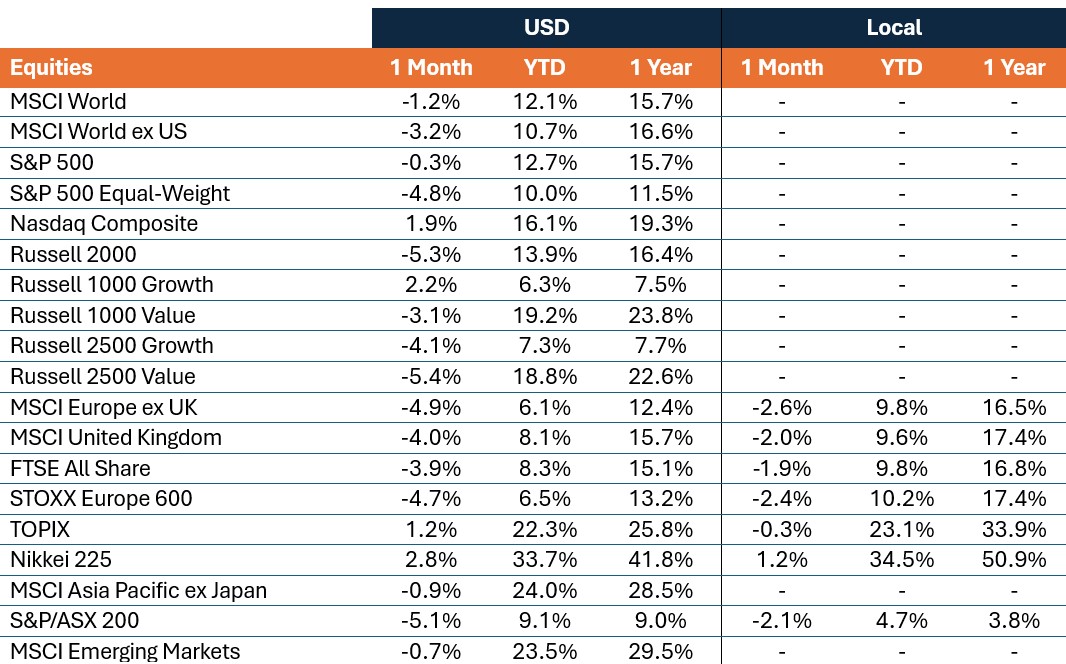
Market Performance
Total returns (%), periods ended September 30, 2026
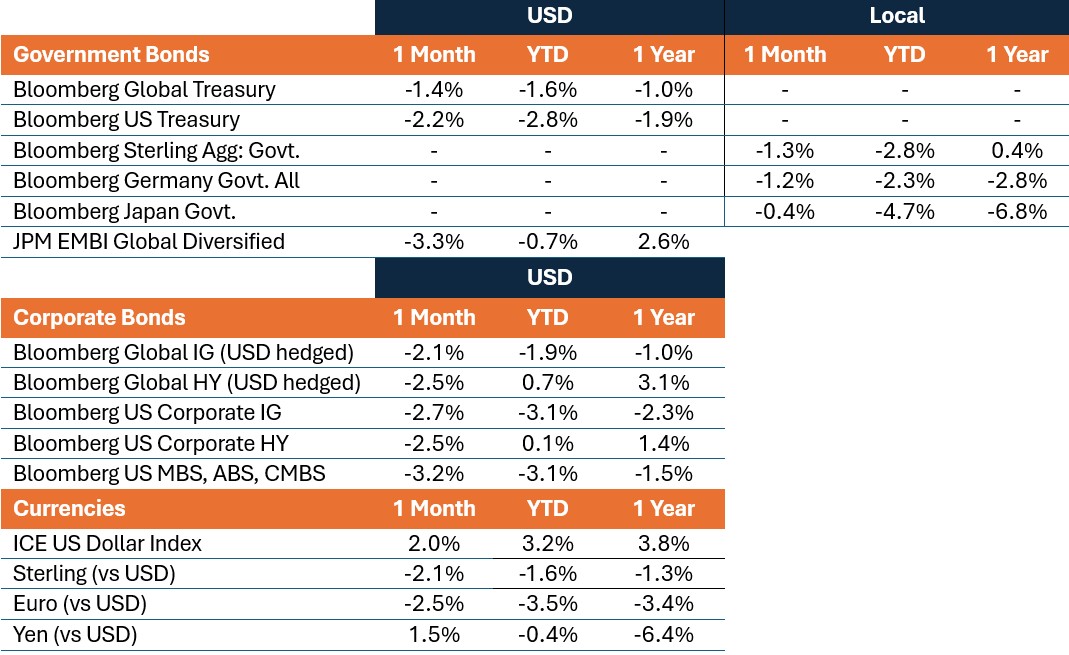
Past performance is no guarantee of future results.
IMPORTANT INFORMATION
Artificial intelligence (“AI”) focused companies, including those that develop or utilize AI technologies, may face rapid product obsolescence, intense competition, and increased regulatory scrutiny. These companies often rely heavily on intellectual property, invest significantly in research and development, and depend on maintaining and growing consumer demand. Their securities may be more volatile than those of companies offering more established technologies and may be affected by risks tied to the use of AI in business operations, including legal liability or reputational harm.
Equity securities are subject to risks including market risk. Returns will fluctuate in response to issuer, political and economic developments.
Fixed income securities are subject to interest rate, inflation, credit and default risk. As interest rates rise, bond prices usually fall, and vice versa. High-yield bonds, or “junk” bonds, involve a greater risk of default and price volatility. Foreign securities, including sovereign debt, are subject to currency fluctuations, political and economic uncertainty and increased volatility and lower liquidity, all of which are magnified in emerging markets.
Foreign securities are subject to additional risks including currency fluctuations, political and economic uncertainty, increased volatility, lower liquidity and differing financial and information reporting standards, all of which are magnified in emerging markets.
Sovereign debt securities are subject to the additional risk that, under some political, diplomatic, social or economic circumstances, some developing countries that issue lower quality debt securities may be unable or unwilling to make principal or interest payments as they come due.
Bloomberg Asian-Pacific Japan Government-Related Index is a fixed-rate, investment grade, JPY-denominated benchmark that includes debt from government-related issuers.
Bloomberg Germany Government All Bonds Index measures the performance of German government bonds (Bunds) issued by the German government.
Bloomberg Global 10+ Year Total Return Index tracks investment-grade government and government-related bonds with maturities of 10 years or greater.
Bloomberg Global Aggregate – Corporate Index is a flagship measure of global investment grade, fixed-rate corporate debt. This multi-currency benchmark includes bonds from developed and emerging markets issuers.
Bloomberg Global High Yield Index is a multi-currency flagship measure of the global high yield debt market. The index represents the union of the US High Yield, the Pan-European High Yield, and Emerging Markets (EM) Hard Currency High Yield Indices.
Bloomberg Global Treasury Index tracks fixed-rate, local currency government debt of investment grade countries, including both developed and emerging markets.
Bloomberg Sterling Aggregate: Government Index measures the performance of UK government bonds (Gilts) within the broader Bloomberg Sterling Aggregate Index, which covers the investment-grade, fixed-rate, sterling-denominated bond market.
Bloomberg US Corporate Bond Index measures the investment grade, fixed-rate, taxable corporate bond market. It includes USD-denominated securities from US and non-US issuers.
Bloomberg US Corporate High Yield Bond Index measures the USD-denominated, high yield, fixed-rate corporate bond market. Bonds from issuers with an emerging markets country of risk, based on Bloomberg EM country definition, are excluded.
Bloomberg US Securitized: MBS, ABS, and CMBS Index tracks all USD-denominated, investment grade, securitized issues within the Bloomberg US Aggregate Index.
Bloomberg US Treasury Index measures U.S. dollar-denominated, fixed-rate, nominal debt issued by the U.S. Treasury.
The DAX is a blue-chip stock market index consisting of the 40 major German companies trading on the Frankfurt Stock Exchange.
The France CAC 40 Index is a market value weighted index, composed of the 40 highest levels among the 100 highest market caps on the Paris Bourse.
FTSE All-Share Index reflects the equity market performance of the United Kingdom. The index includes nearly all eligible companies on the London Stock Exchange, covering large, mid, and small-cap stocks.
J.P. Morgan EMBI Global Diversified Index tracks U.S. dollar-denominated emerging market fixed and floating-rate debt instruments issued by sovereign and quasi-sovereign entities, with country weights capped to limit concentration in the largest issuers.
ICE U.S. Dollar Index is a benchmark measuring the U.S. dollar’s value against a basket of six major world currencies (Euro, Yen, Pound Sterling, Canadian Dollar, Swedish Krona, Swiss Franc).
MSCI AC Asia Pacific ex Japan Index reflects the equity market performance of the Asia Pacific region, excluding Japan, covering both developed and emerging markets.
MSCI ACWI ex USA Index captures large- and mid-cap representation across 22 of 23 developed markets (excluding the US) and 24 emerging markets countries.
MSCI China Index captures large and mid cap representation across China A shares, H shares, B shares, Red chips, P chips and foreign listings (e.g. ADRs).
MSCI Emerging Markets Index reflects the equity market performance of emerging markets.
MSCI Emerging Markets (EM) Latin America Index captures large and mid cap representation across Emerging Markets (EM) countries in Latin America. The index covers approximately 85% of the free float-adjusted market capitalization in each country.
MSCI Europe Index reflects the equity market performance of large and mid-sized companies listed in developed markets in Europe.
MSCI Europe ex UK Index reflects the equity market performance of large and mid-sized companies listed in developed markets in Europe excluding the United Kingdom.
MSCI United Kingdom Index reflects the equity market performance of large and mid-sized companies listed in the UK market.
MSCI World Index reflects the equity market performance of global developed markets.
MSCI World ex USA Index reflects the equity market performance of global developed markets excluding the United States.
NASDAQ Composite Stock Index: National Association of Securities Dealers Automated Quotation System (NASDAQ) is a nationwide computerized quotation system for over 5,500 over-the-counter stocks. The index is compiled of more than 4,800 stocks that are traded via this system.
Nikkei 225 Index (also known as Nikkei Stock Average): A measure of Japanese equity market performance. The index includes 225 of the largest companies listed on the Tokyo Stock Exchange.
PHLX Semiconductor Sector Index (SOX) is a specialized, modified market capitalization-weighted index composed of companies primarily involved in the design, distribution, manufacture, and sale of semiconductors.
Purchasing Managers’ Index (PMI) is an index of the prevailing direction of economic trends in the manufacturing and service sectors, based on a survey of private sector companies.
Russell 1000® Growth Index reflects the performance of U.S. large-cap equities with higher price-to-book ratios and higher forecasted growth values.
Russell 1000® Value Index reflects the performance of U.S. large-cap equities with lower price-to-book ratios and lower forecasted growth values.
Russell 2000® Index reflects the performance of U.S. small-cap equities.
Russell 2500™ Growth Index reflects the performance of U.S. small to mid-cap equities with higher price-to-book ratios and higher forecasted growth values.
Russell 2500™ Value Index reflects the performance of U.S. small to mid-cap equities with lower price-to-book ratios and lower forecasted growth values.
S&P 500® Index reflects U.S. large-cap equity performance and represents broad U.S. equity market performance.
S&P 500® Equal Weight Index (EWI) is the equal-weight version of the S&P 500. The index includes the same constituents as the capitalization weighted index, but each company is allocated a fixed weight – or 0.2% of the index total at each quarterly rebalance.
S&P/ASX 200 Index reflects the performance of the 200 largest, most liquid companies listed on the Australian Securities Exchange (ASX).
STOXX Europe 600 Index: An index of the 600 largest listed stocks in the European equity market, comprising 17 countries and 11 industries.
TOPIX: A capitalization-weighted index of all the companies listed on the First Section of the Tokyo Stock Exchange and is widely regarded as a broad benchmark for Japanese stock prices.
10-year bond: A bond that is set to mature (repay the principal value) in 10 years.
10-Year Treasury Yield is the interest rate on U.S. Treasury bonds that will mature 10 years from the date of purchase.
Agency Mortgage-backed Securities (Agency MBS): A type of asset-backed security that is specifically secured by a collection of mortgages.
Asset-backed Securities (ABS): These are financial instruments that are backed by a pool of assets—typically those that generate a cash flow from debt, such as loans, leases, credit card balances, or receivables.
Basis point: One basis point (bp) equals 1/100 of a percentage point, 1bp = 0.01%.
Bund yield: Bund yields are viewed as benchmark yield indicators for European government bonds; those with a 10-year maturity are considered to be the German equivalent of U.S. Treasury bonds.
Commercial Mortgage-backed Securities (CMBS): A type of mortgage-backed security that is secured by the loan on commercial real estate properties rather than residential real estate.
Consumer Price Index (CPI): A measure that examines the price change of a basket of consumer goods and services over time. It is used to estimate inflation.
Credit spread: The difference in yield between securities with similar maturity but different credit quality. Widening spreads generally indicate deteriorating creditworthiness of corporate borrowers, and narrowing indicate improving.
Curve/Yield curve: A yield curve plots the yields (interest rate) of bonds with equal credit quality but differing maturity dates. Typically bonds with longer maturities have higher yields.
The Federal Open Market Committee (FOMC) is the body of the Federal Reserve System that sets national monetary policy.
Fiscal policy: Describes government policy relating to setting tax rates and spending levels. Fiscal policy is separate from monetary policy, which is typically set by a central bank.
Gilt yield: Gilt yields are viewed as benchmark yield indicators for United Kingdom government bonds; those with a 10-year maturity are considered to be the UK equivalent of U.S. Treasury bonds.
Hawkish policy aims to curb inflation and slow down growth in the economy by raising interest rates and reducing the supply of money.
High yield bond: Also known as a sub-investment grade bond, or ‘junk’ bond. These bonds usually carry a higher risk of the issuer defaulting on their payments, so they are typically issued with a higher interest rate (coupon) to compensate for the additional risk.
Inflation: The rate at which the prices of goods and services are rising in an economy. The Consumer Price Index (CPI) and Retail Price Index (RPI) are two common measures.
Investment grade bond: A bond typically issued by governments or companies perceived to have a relatively low risk of defaulting on their payments, reflected in the higher rating given to them by credit ratings agencies.
JGB yield: JGB yields are viewed as benchmark yield indicators for Japanese government bonds; those with a 10-year maturity are considered to be the Japanese equivalent of U.S. Treasury bonds.
Monetary policy: The policies of a central bank, aimed at influencing the level of inflation and growth in an economy. Monetary policy tools include setting interest rates and controlling the supply of money. Dovish policy aims to stimulate economic growth by lowering interest rates and increasing the money supply.
Producer Price Index (PPI) measures the average change over time in the selling prices received by domestic producers for their output.
Securitization: The process in which certain types of assets are pooled so that they can be repackaged into interest-bearing securities. The interest and principal payments from the assets are passed through to the purchasers of the securities.
U.S. Treasury securities are direct debt obligations issued by the U.S. Government. Treasury Bills and U.S. Government Bonds are guaranteed by the full faith and credit of the U.S. government, are generally considered to be free of credit risk.
Volatility measures risk using the dispersion of returns for a given investment.
Quantitative Easing (QE) is a government monetary policy occasionally used to increase the money supply by buying government securities or other securities from the market.
Yield: The level of income on a security over a set period, typically expressed as a percentage rate. For equities, a common measure is the dividend yield, which divides recent dividend payments for each share by the share price. For a bond, this is calculated as the coupon payment divided by the current bond price.
Yield to Worst (YTW) is a portfolio characteristic that represents the lowest potential yield a bond or portfolio may achieve, assuming no default and that issuers exercise any applicable call or prepayment features. At the portfolio level, YTW generally represents the weighted average YTW of the underlying holdings. YTW does not represent actual investor return, past performance, or a guarantee of future income. It is an analytical measure based on current portfolio holdings and assumptions and may differ from realized results.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.