Key takeaways:
- Global equity returns were mixed in October as a sharp retreat in AI-related technology stocks contrasted with broader strength across defensive sectors and several developed markets.
- Global government bonds rallied as risk aversion restored demand for sovereign debt and pushed yields lower, reversing part of September’s selloff despite persistent inflation pressures and rising oil prices.
- Markets saw powerful rotation dynamics in October, echoing patterns that have been on display periodically throughout the year. Value meaningfully outperformed growth, while the equal-weight S&P 500 posted its largest monthly outperformance versus the market-cap-weighted benchmark since 2009.
Market overview
Global equity returns were mixed in October as weakness in AI-related technology stocks contrasted with strength across other sectors and regions. The MSCI World Index fell 0.8% in U.S. dollar terms but remained up 11.3% year to date. Global government bonds rallied as risk aversion restored demand for sovereign debt, pushing benchmark yields lower across major markets. Global corporate bonds also advanced, although credit spreads widened as concerns around AI-related financing and weaker risk sentiment weighed on lower-quality credit.
Oil prices continued to rise amid heightened geopolitical tensions and uncertainty surrounding Middle East supply, with Brent crude advancing more than 13% during the month. The U.S. Dollar Index rose 0.4%, while the euro weakened against the dollar amid political and fiscal uncertainty in France. Gold fell nearly 7% as precious metals failed to benefit from the broader flight to safety.
Global equity performance diverged as the AI trade came under pressure
Australia and the UK led gains, while Asian equities, emerging markets, and the Nasdaq fell sharply.
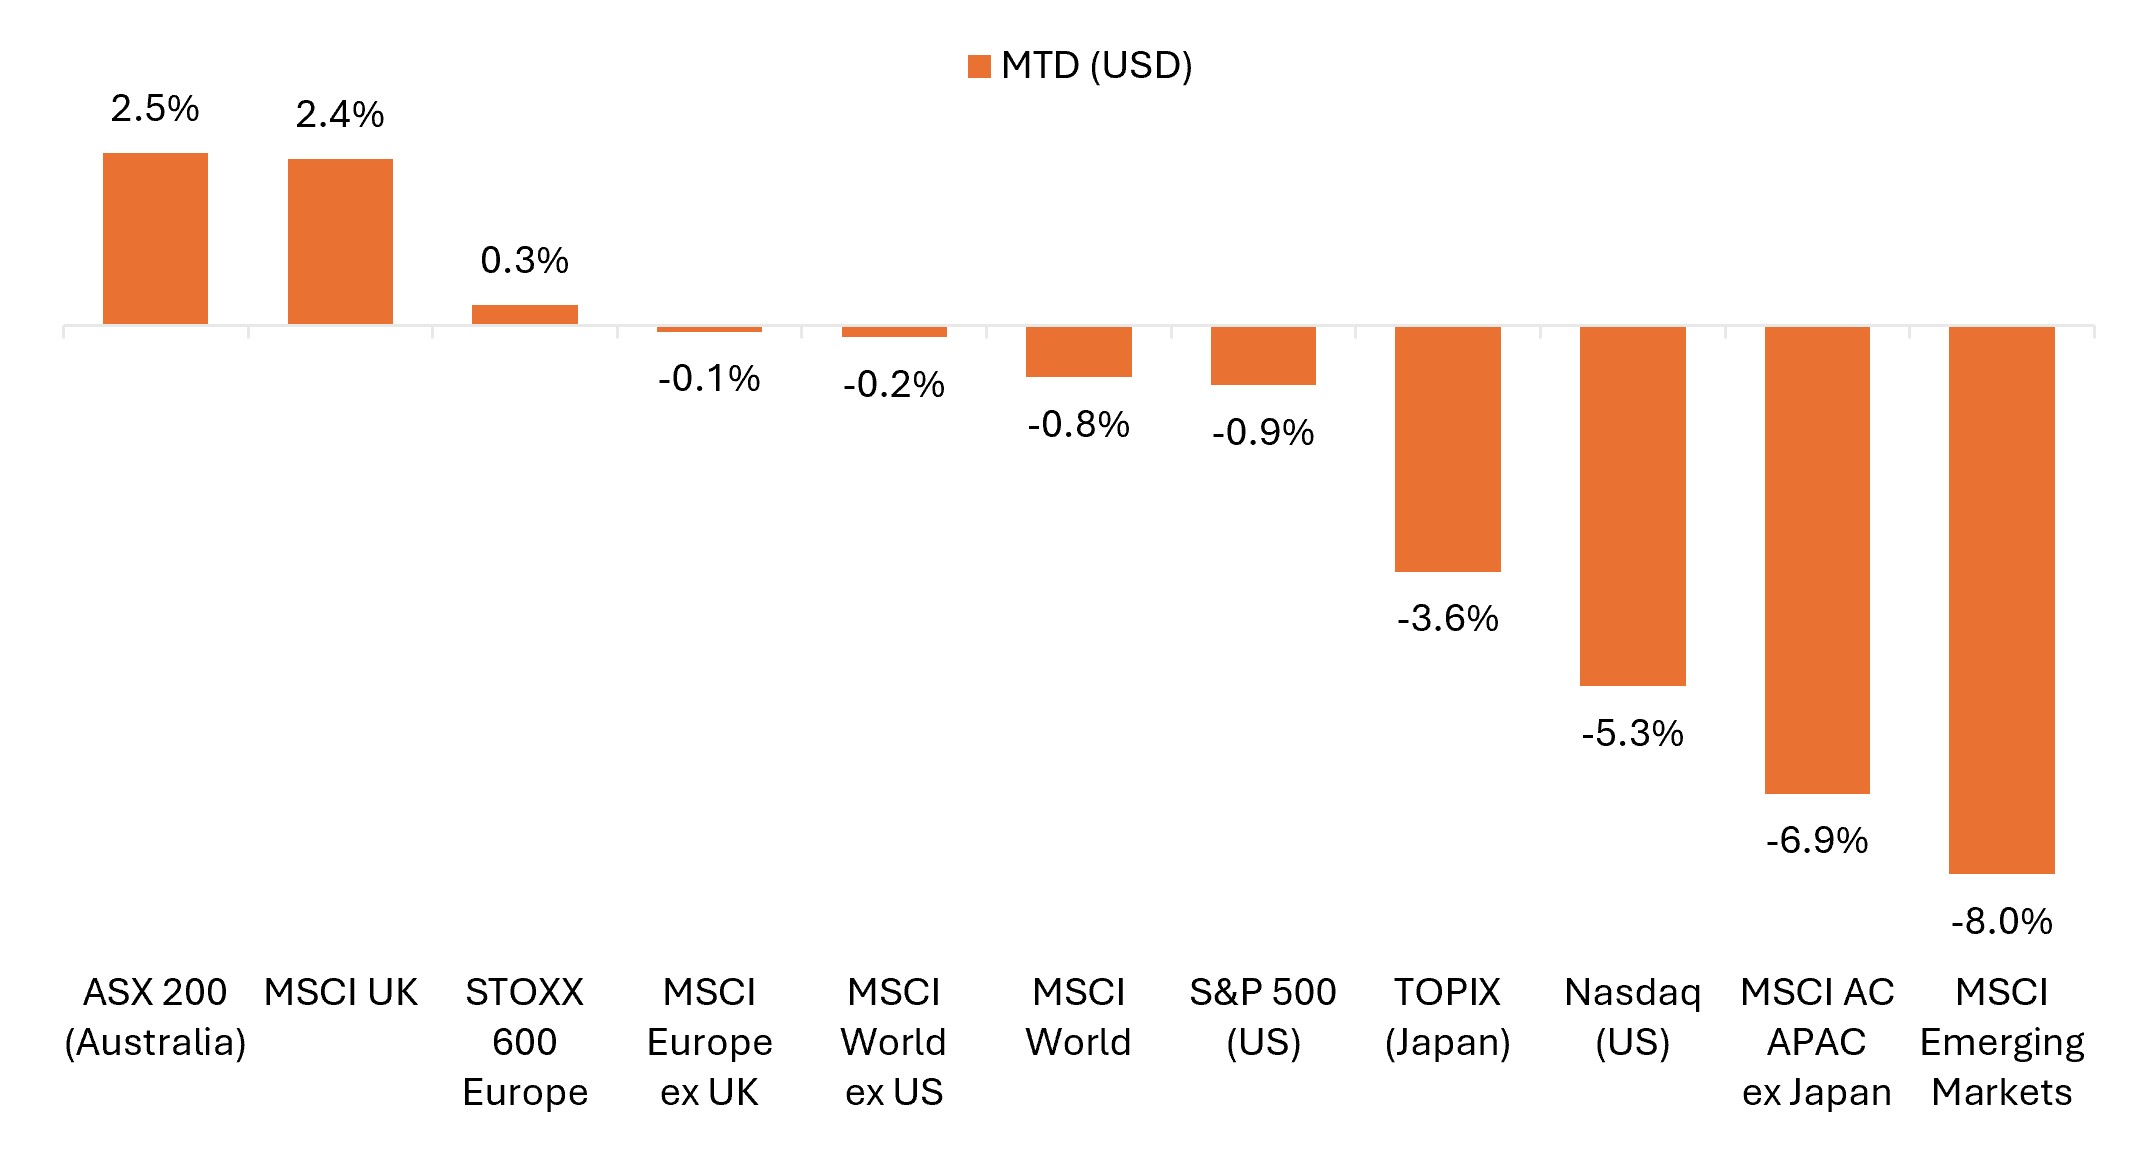
Source: Bloomberg, data from 30 September 2026 to 31 October 2026. Represents index total returns in U.S. dollar terms. Past performance is no guarantee of future results.
Key themes that mattered for markets
- The AI spending boom came under greater funding scrutiny: Concerns around heavy AI-related capital expenditure (and the returns on that investment) along with pressure on hyperscaler free cash flow and signs of credit stress among so-called “neocloud” providers weighed on AI-related stocks, with renewed selling in Big Tech driving a sharp rotation into month end. The Nasdaq Composite had its worst month since March 2025, even as earnings from tech bellwethers and global chipmakers pointed to continued strong demand for AI computing capacity.
- Sovereign bonds appeared to regain their safe-haven status: The shift in risk sentiment prompted a defensive rotation that pushed government bond yields lower as traditional flight-to-safety dynamics kicked in. The move marked a sharp contrast from September, when inflation concerns, fiscal uncertainty, and heavy debt issuance sent long-dated bond yields to multi-year highs. Notably, the rate reprieve came despite oil prices marching higher again, with bond yields and crude prices diverging after largely moving in lockstep since June.
Oil and bond yields decoupled as Treasuries regained defensive appeal
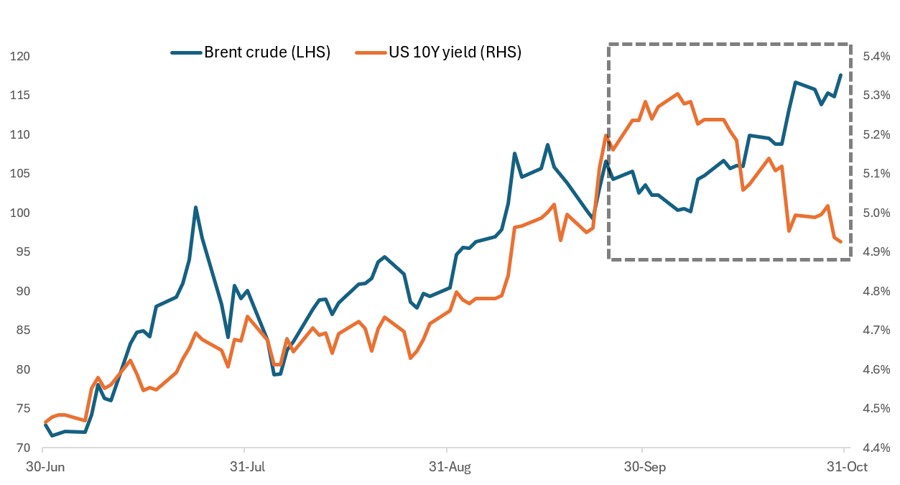
Source: Bloomberg, data from 30 June 2026 to 31 October 2026. Represents front-month Brent crude futures and the U.S. 10-year Treasury yield. Past performance is no guarantee of future results.
- Broadening and rotation, not total “risk off”, across equity markets: The weakness in tech stocks was offset by strength elsewhere as market breadth showed meaningful improvement. Most sectors posted strong monthly gains, and more than 70% of S&P® 500 Index members were higher on the month. European equities also proved resilient amid the AI-driven volatility. Importantly, the shift was supported by fundamentals, with earnings tracking strong double-digit year-over-year growth in both Europe and the U.S., and much of the latter coming from companies outside the Magnificent 7.
- Geopolitical tensions kept upward pressure on energy prices: Unresolved conflicts in the Middle East and Russia-Ukraine continued to create uncertainty around global energy supplies and refining capacity. Brent crude jumped more than 13%, building on September’s gains. Sustained Houthi attacks on Saudi infrastructure and Russia’s extension of its diesel export ban added to supply concerns. Persistently high energy prices remained a potential headwind for inflation and growth, complicating the outlook for interest rates and creating another source of dispersion across regions and sectors.
United States
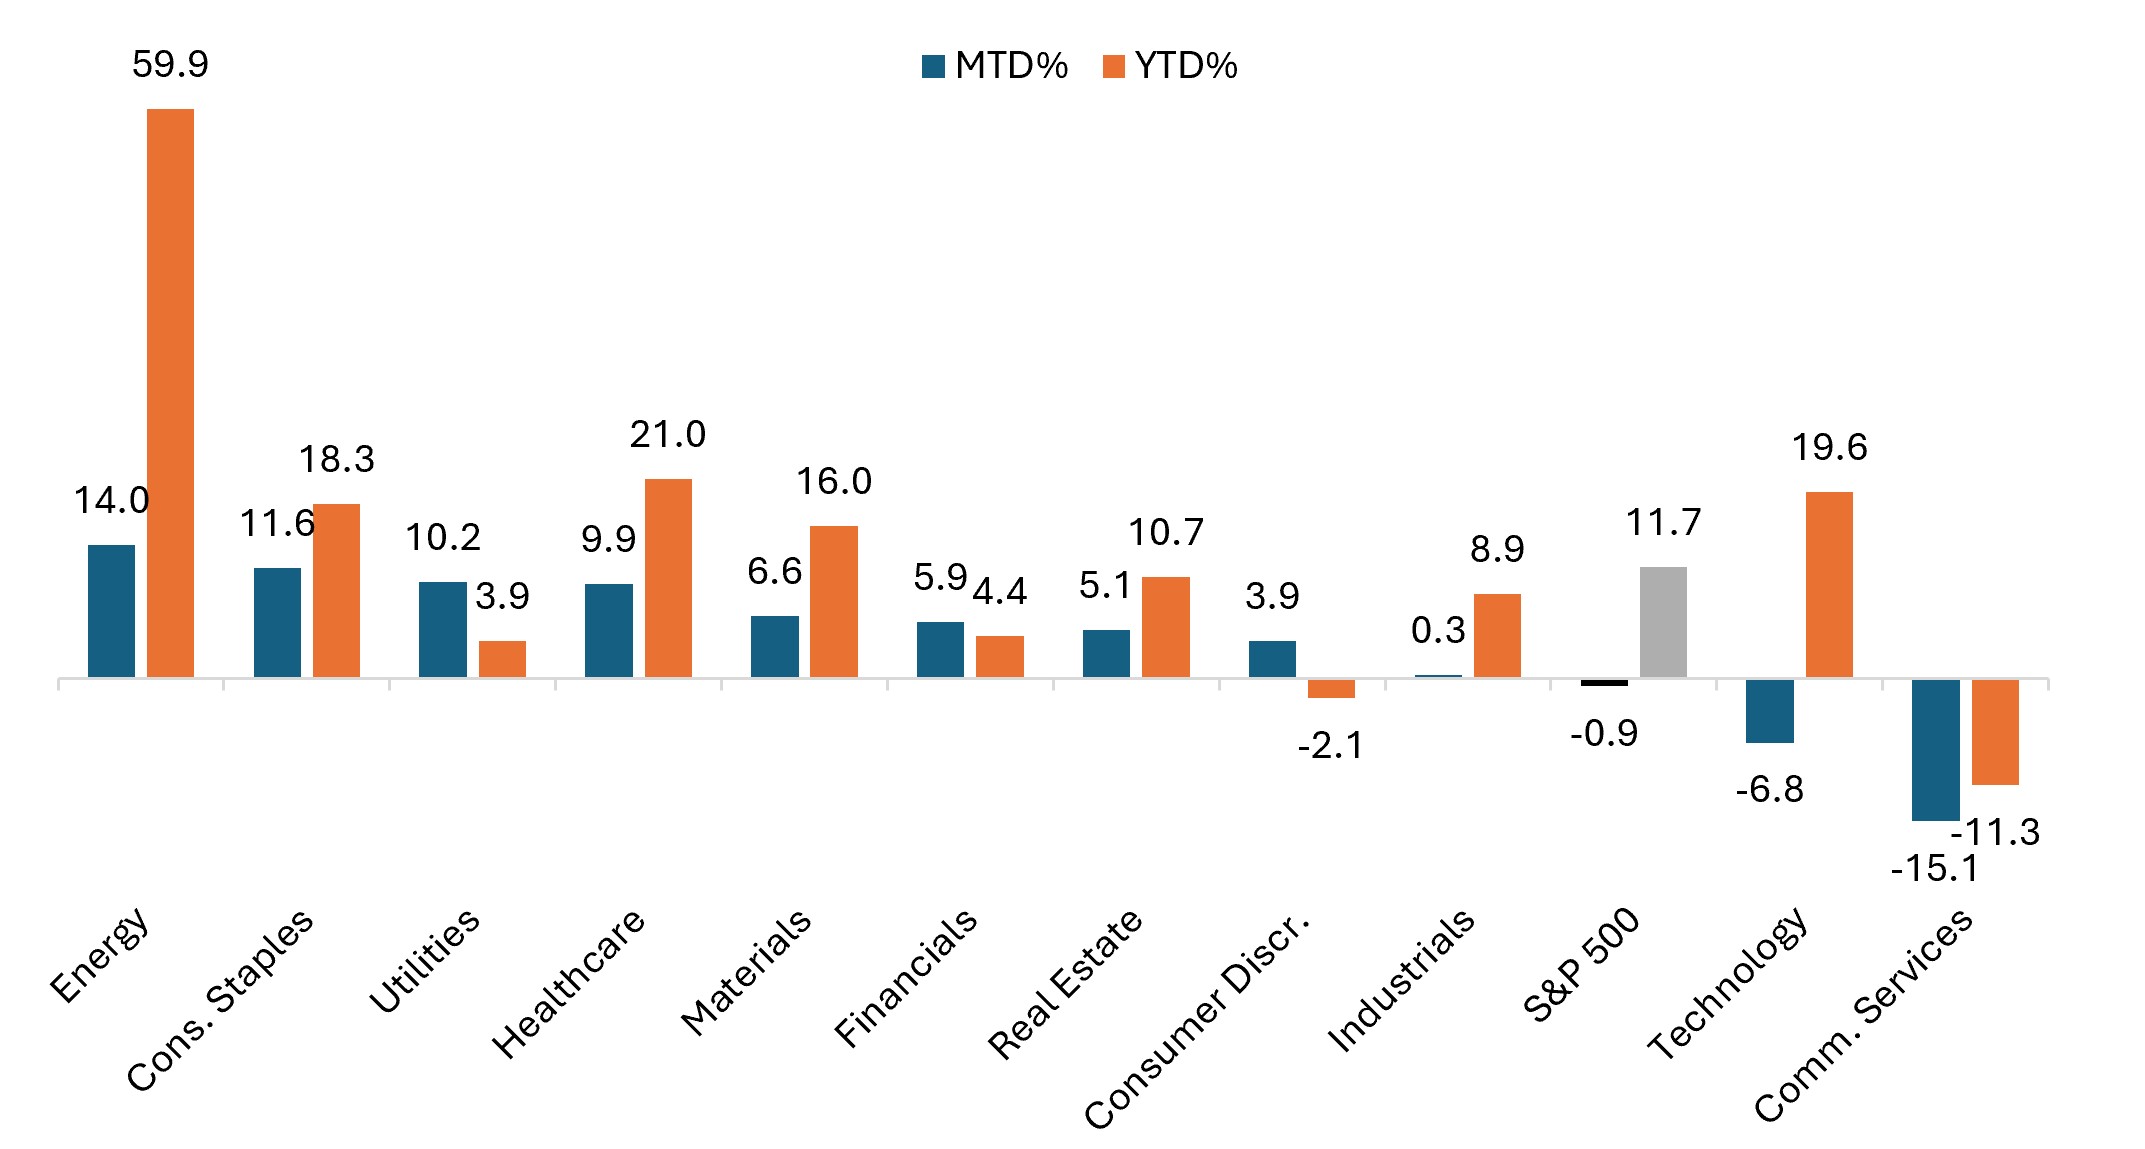
U.S. equities diverged sharply in October as weakness in AI-related technology stocks contrasted with significant strength across the broader market. The S&P 500 Index declined modestly, while the equal-weight S&P 500 rose 5.0%, marking its biggest outperformance relative to the market-cap-weighted benchmark since April 2009. Meanwhile, the tech-heavy Nasdaq Composite had its worst month in more than a year. Value significantly outperformed growth, while Energy, Consumer Staples, Utilities, and Healthcare led a broad rotation away from technology-oriented sectors.
- The S&P 500 declined 0.9% in October but remained up 11.7% year to date, while the S&P 500 Equal Weight Index rose 5.0% and was up 15.5% year to date.
- The Nasdaq Composite fell 5.3%, its steepest monthly decline since March 2025, while the Philadelphia Semiconductor Index (SOX) tumbled 15.3%.
- The small-cap Russell 2000 Index rose 0.6% and was up 14.5% year to date.
- Value meaningfully outperformed growth. The Russell 1000 Value Index advanced 4.4%, while the Russell 1000 Growth Index fell 6.1%. Among small- and mid-cap companies, the Russell 2500 Value Index rose 3.2%, while the Russell 2500 Growth Index declined 2.9%.
- Energy (+14.0%), Consumer Staples (+11.6%), Utilities (+10.2%), and Healthcare (+9.9%) led the S&P 500 sectors. Communication Services and Information Technology were the only sectors to post monthly declines, falling 15.1% and 6.8%, respectively.
Energy and defensive sectors led as technology-related stocks retreated
S&P 500 sector performance (October and year to date)
Source: Bloomberg, as of 31 October 2026. Past performance is no guarantee of future results.
U.S. economic data painted a mixed picture, with resilient growth and business activity offset by softer hiring and renewed inflation pressures:
- The Federal Reserve (Fed) left its benchmark policy rate unchanged at 3.75%-4.00%, as widely expected, following September’s 25-basis-point (bp) increase. The decision passed by a 10-2 vote, with two policymakers favoring another rate increase. Chair Kevin Warsh pointed to strong economic activity and solid labor market conditions but noted that inflation remained elevated, with the Fed opting for patience to allow for the accumulation of further data ahead of its December meeting.
- The labor market showed signs of cooling but remained broadly stable. Nonfarm payrolls increased by 29,000 in September, well below expectations for roughly 90,000, while the unemployment rate edged up to 4.2% from 4.1%. Initial jobless claims remained historically low, however, ending October at 194,000, just above July’s 189,000 reading that was the lowest since 1969.
- Inflation accelerated, fueled in part by higher energy prices. The Consumer Price Index (CPI) rose 3.7% year over year in September, up from 3.4% in August, with higher gas prices accounting for more than half of the monthly increase. Core CPI rose 2.6% year over year, up from 2.4% prior. The Fed’s preferred inflation gauge also moved higher, with core personal consumption expenditures (PCE) inflation rising to 3.1% from 3.0%.
- Economic activity remained strong. Real U.S. GDP expanded at a 3.4% annualized rate in the third quarter, up from 2.2% in Q2 and ahead of expectations for 3.2%. Meanwhile, the S&P Global flash U.S. composite PMI eased to 57.6 in October from 58.4 in September but remained firmly in expansion territory, with new orders reaching their highest level in more than four years.
Europe
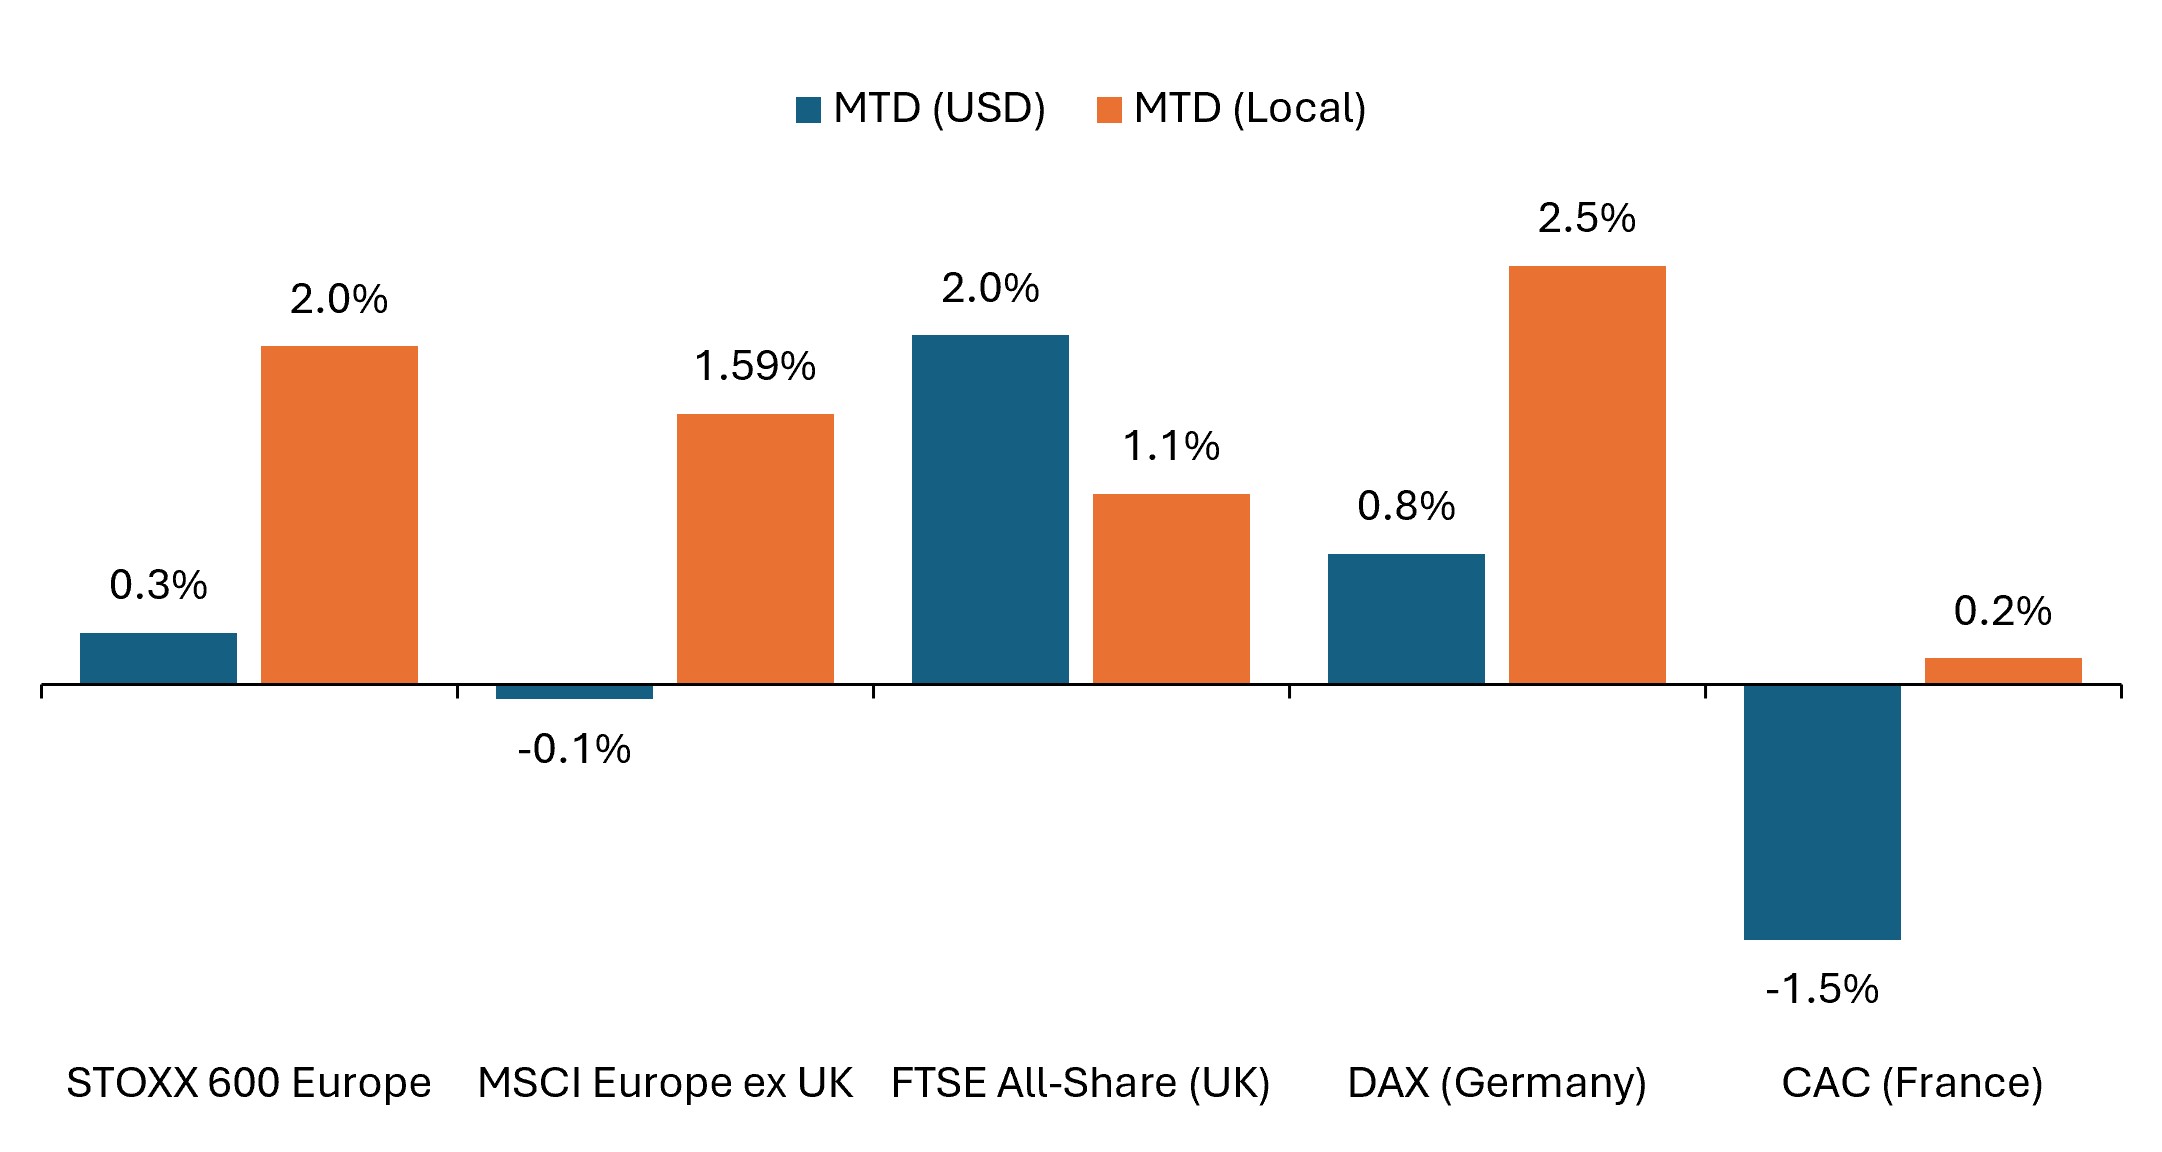
Eurozone equities were mostly higher in October as resilient economic growth and corporate earnings competed with higher energy costs and renewed political and fiscal uncertainty. The MSCI Europe ex United Kingdom Index rose 1.6% in local currency terms but declined 0.1% in U.S. dollar terms as the euro weakened. Germany advanced, while France was a notable laggard as fiscal and political concerns weighed on domestic assets, pushing French government bond yields higher and their spread over German bunds to the widest level since the early 2010s.
- The European Central Bank (ECB) left its key policy rate unchanged at 2.5%, as expected, after hiking in September. While the October statement leaned less hawkish than September’s, acknowledging that higher bond yields and tighter financial conditions were weighing on economic growth and inflation, markets continued to price in greater than 80% odds of another rate increase in December.
- Inflation accelerated in September, driven largely by higher energy costs. Eurozone CPI rose to 3.8% year over year from 3.2% in August, its highest level in three years. Energy inflation jumped to 18.9%, while core inflation edged up to 2.5% from 2.4%.
- Business activity lost momentum in October. The flash eurozone composite PMI fell to 51.9 (from 53.1 in September), a four-month low, as activity contracted in France amid widespread political protests, while growth also softened in Germany. Input-cost inflation accelerated for a second month. However, Eurostat’s preliminary estimate showed GDP grew 1.3% year over year in Q3, up from 1.2% in the prior quarter.
UK equities advanced in October amid resilient economic data, firmer business activity, and strength in energy-related companies and defensive sectors. The MSCI United Kingdom Index rose 1.5% in sterling terms and 2.4% in U.S. dollar terms. The FTSE All-Share Index gained 1.1% in sterling and 2.0% in U.S. dollars, with sterling appreciating against the dollar during the month. The publication of the October Budget late in the month broadly met expectations, with its relatively neutral policy package leading to a muted market reaction.
- UK inflation accelerated more than expected in September. CPI inflation rose to 3.5% year over year, up from 3.1% in August and ahead of expectations for 3.4%, solidifying expectations for a rate increase from the Bank of England (BoE) in November. Motor-fuel inflation reached 29.8% year over year, its highest level since August 2022.
- The UK labor market showed signs of stabilizing. The unemployment rate edged down to 4.7% in the three months through August, coming in below expectations for 4.9%, while payrolls rose by 13,000 in September, their strongest monthly gain since August 2025.
- Business activity strengthened despite elevated price pressures. The flash UK composite PMI rose to 53.1 in October from 52.0 in September, its highest level since February, as new orders increased and manufacturers recorded their strongest output growth in more than two years. Companies also added workers for the first time since the 2024 payroll-tax increase, although business cost inflation accelerated to its strongest pace since June. On a monthly basis, UK GDP edged up 0.1% in August following 0.4% growth in July.
European markets were mostly higher, with France a notable laggard
A stronger pound and weaker euro had contrasting effects on returns in U.S. dollar terms.
Source: Bloomberg, data from 30 September 2026 to 31 October 2026. Past performance is no guarantee of future results.
Within the STOXX Europe 600 Index – comprising companies from 17 countries across developed Europe including the UK – sector performance diverged sharply, with defensive areas and Energy outperforming while Banks, Industrials, and Basic Resources lagged.
- Healthcare (+14.1% in euro terms) was the strongest-performing sector, supported by defensive demand, resilient earnings, and positive drug-development news. Food, Beverage & Tobacco (+13.5%), Media (+8.8%), Personal Care, Drug & Grocery (+8.7%), Retail (+7.8%), Insurance (+6.9%), Chemicals (+6.5%), and Utilities (+6.2%) all posted strong gains.
- Energy (+8.7%) rallied as ongoing geopolitical tensions in the Middle East and in the Russia-Ukraine war kept upward pressure on oil and fuel prices.
- Technology (-1.5%) and Industrials (-2.9%) declined amid heightened scrutiny of AI-related investment, which weighed on technology and data-center infrastructure companies.
- Basic Resources (-8.4%) fell as weaker metals prices and concerns over Chinese demand weighed on the sector. Banks (-10.3%) were the weakest-performing sector, pressured by heightened sovereign-bond volatility and mixed earnings results.
Asia Pacific
Japanese equities fell in October as weakness in semiconductors and technology-related companies weighed on performance. The TOPIX declined 3.5% in yen terms and 3.6% in U.S. dollar terms, while the Nikkei 225 fell 5.2% locally and 5.3% in U.S. dollars, with the Nikkei’s heavier technology weighting contributing to the wider gap between the two indices. The yen was little changed against the U.S. dollar.
- The Bank of Japan (BoJ) left its policy rate unchanged at 1.25%, as expected, after raising rates in September. Policymakers continued to signal that further tightening would likely be needed, with markets pricing in strong odds of another 25-bp rate increase in December.
- Japan’s September CPI report showed core inflation accelerating to 2.1% year over year (from 1.7% in August), its highest reading of 2026 and the first time in nine months that core CPI exceeded the BoJ’s 2% target.
- Economic activity remained resilient. Japan’s flash composite PMI held at 52.3, marking a 19th consecutive month of expansion, as stronger services activity offset slower manufacturing growth. Input-cost inflation accelerated slightly amid higher raw material and labor costs.
Equities across Asia Pacific ex Japan declined sharply as concerns around AI-related investment and financing weighed on technology-heavy markets. The MSCI AC Asia Pacific ex Japan Index fell 6.9% in U.S. dollar terms but remained up 15.7% year to date. South Korea, Taiwan, and China posted steep declines, while Australia advanced. The MSCI China Index declined 7.0% in U.S. dollar terms. China’s economy grew approximately 4.5% year over year in Q3, supported by exports and industrial activity, but weak retail sales, fixed investment, and continued property-market softness highlighted persistently sluggish domestic demand. Australia’s S&P/ASX 200 Index advanced 1.4% in local currency terms and 2.5% in U.S. dollar terms as strength in defensive areas offset weakness among miners. Higher-than-expected inflation increased expectations for additional policy tightening from the Reserve Bank of Australia.
Emerging Markets
Emerging market equities fell sharply in October as AI-related weakness across Asian technology markets, a stronger U.S. dollar, elevated oil prices, and country-specific political risks weighed on returns. The MSCI Emerging Markets Index declined 8.0% in U.S. dollar terms but remained up 13.8% year to date. Performance diverged substantially, with India and Mexico advancing while South Korea, Indonesia, Brazil, and Turkey posted steep declines. Performance figures below reference MSCI country indexes reported in U.S. dollar terms.
- South Korea fell 15.4% and Taiwan declined 8.3% as the global selloff in semiconductor and other AI-related stocks weighed heavily on both markets, despite continued evidence of strong underlying chip demand.
- Indonesia declined 13.8% amid heightened market-access concerns after MSCI indicated it was considering reclassifying the country’s equity market from emerging to frontier market status. India, by contrast, rose 1.4%, supported by relatively low exposure to AI and semiconductor names, alongside upgraded GDP growth forecasts.
- Latin American equities came under pressure, with the MSCI EM Latin America Index falling 7.6%. Brazil (-12.0%) was among the weakest markets, reversing an early-month rally as Luiz Inácio Lula da Silva staged a surprise comeback in the presidential election, fueling concerns about a potentially more expansionary policy agenda and the country’s fiscal outlook. Peru (-10.6%), Chile (-9.8%), and Argentina (-6.2%) also declined, while Mexico (+4.6%) and Colombia (+0.3%) bucked the broader regional weakness.
- In EMEA, Turkey (-9.8%) led declines after MSCI froze certain index-related changes for Turkish equities amid an ongoing domestic fund crisis, raising concerns about the country’s emerging-market status. South Africa (-3.7%) also declined as weakness among mining companies, particularly precious-metals producers, and pressure on the rand weighed on the market. Poland (-2.7%), Hungary (-2.3%), and the Czech Republic (-0.3%) posted more modest declines, while the Polish zloty fell to a three-year low against the euro amid fiscal and monetary policy uncertainty.
Fixed Income
Global government bonds rallied in October as sovereign debt regained its traditional safe-haven role amid volatility in AI-related equities and credit. After reaching multi-year highs in September, yields fell across the U.S., UK, Germany, and Japan despite continued inflation pressures and rising oil prices, reversing a portion of the prior month’s bond selloff.
- The Bloomberg Global Treasury Index rose 1.7% in U.S. dollar-hedged terms and was up 0.1% year to date.
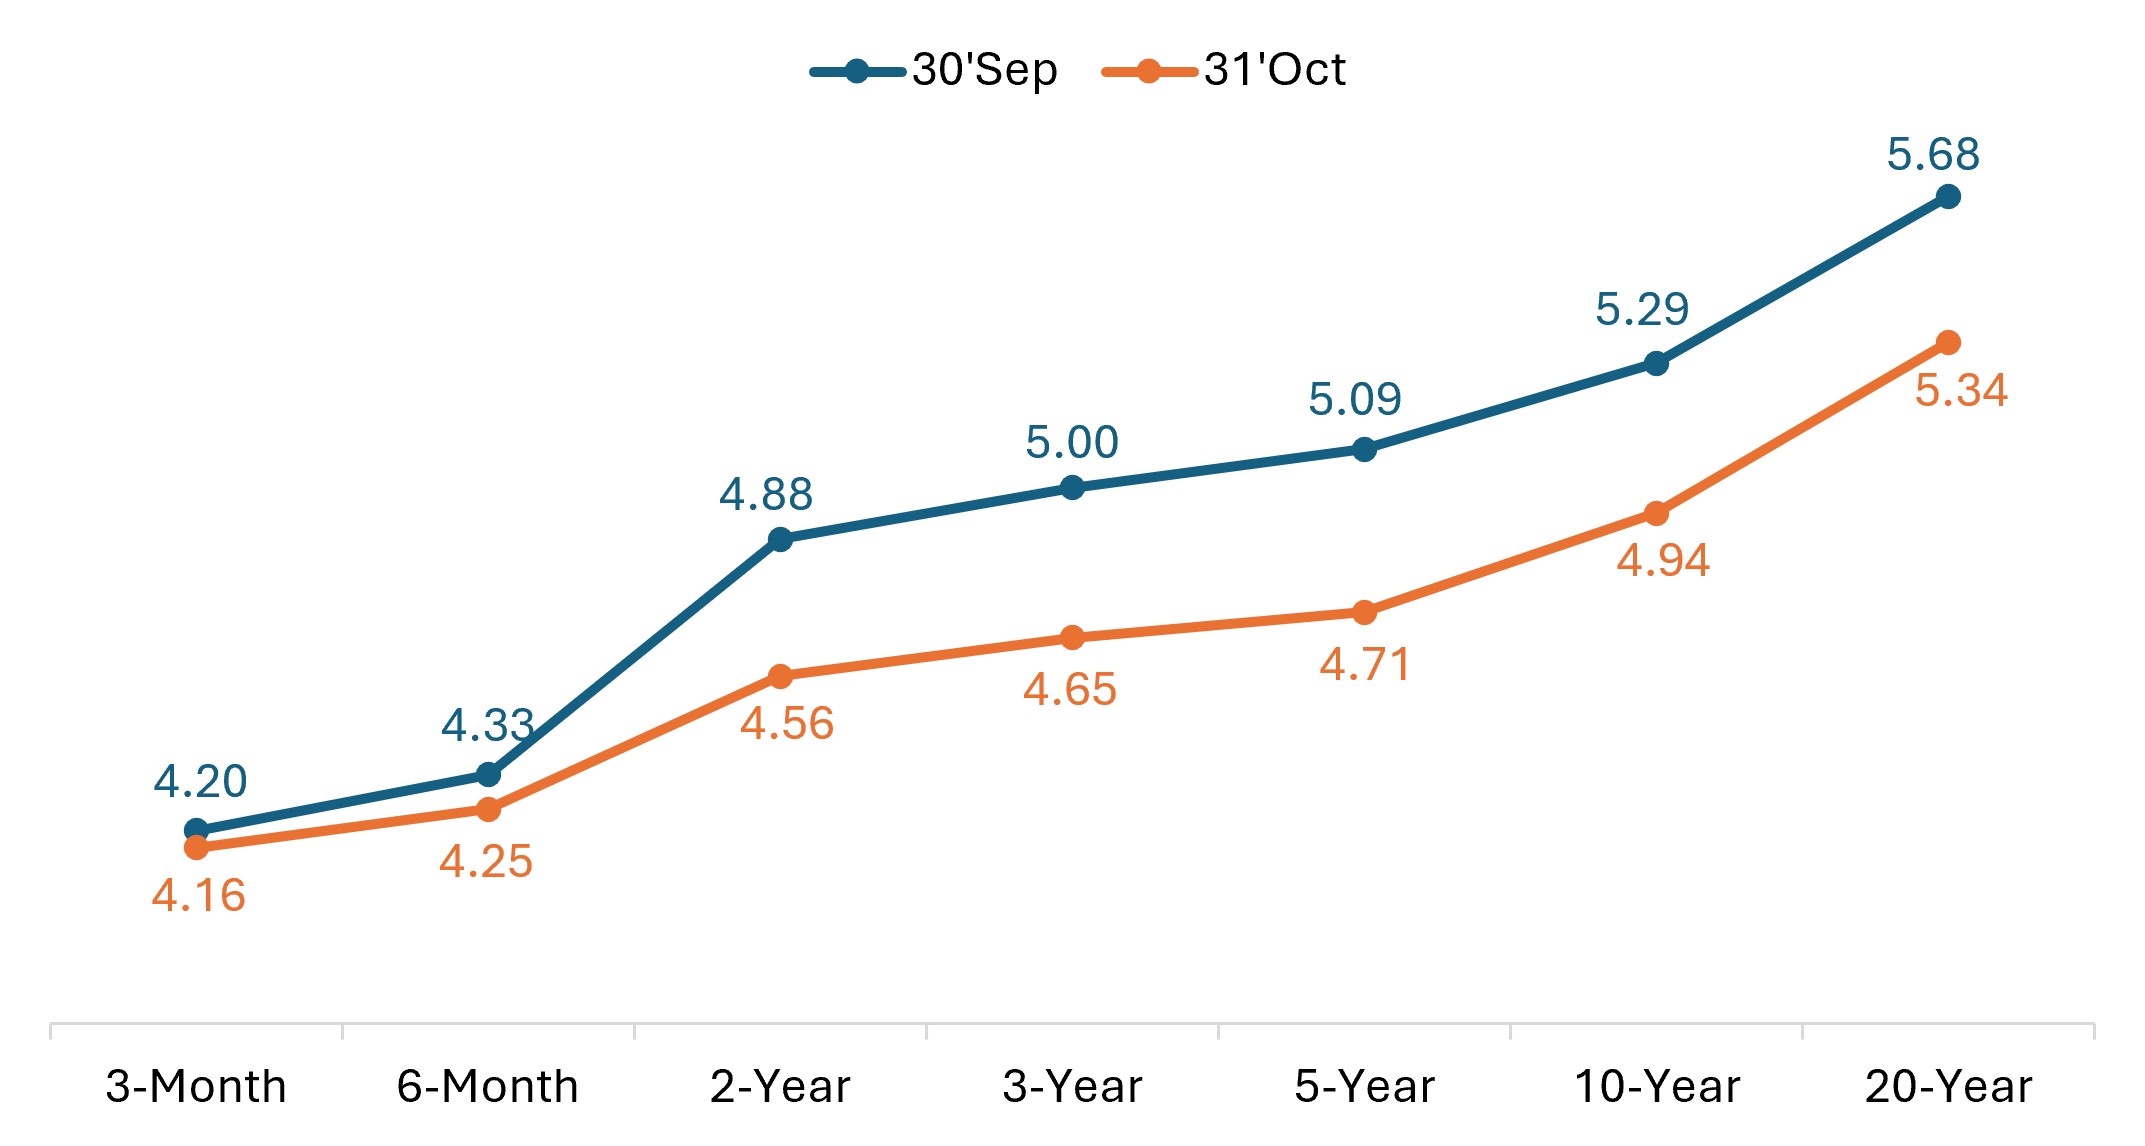
- The U.S. 10-year Treasury yield fell 35 bps to 4.94%, with Treasuries rallying as anxiety around the AI trade and broader growth concerns outweighed inflation and fiscal concerns.
- The U.S. Treasury curve shifted lower across maturities during the month. The spread between 10-year and 2-year Treasury yields narrowed slightly to 38 bps from 41 bps prior.
U.S. Treasury yield curve (month-on-month change)
Source: Bloomberg, as of 31 October 2026. Past performance is no guarantee of future results.
- In Europe, UK government bonds rallied, with the 10-year gilt yield declining approximately 14 bps to 5.28%.
- German sovereign bonds also advanced, with the 10-year bund yield falling approximately 26 bps to 3.32%. French government bonds bucked the broader rally, however, as fiscal and political uncertainty pushed yields higher and widened the spread over German bunds to levels not seen since the early 2010s.
- Japanese government bonds (JGBs) also gained, as the 10-year JGB yield declined approximately 18 bps to 2.88%.
Emerging market hard-currency debt advanced as falling U.S. Treasury yields provided support. The 2026 IMF and World Bank Annual Meetings highlighted the resilience of many emerging economies, while also underscoring increasingly uneven growth, fiscal capacity, and financing conditions across countries.
- The J.P. Morgan EMBI Global Diversified Index, which tracks U.S. dollar-denominated debt issued by emerging market governments, rose 1.4% in October, recouping some of September’s steep drop.
Spread sectors generally posted positive returns in October as declining government bond yields offset pockets of weakness in lower-quality credit. Investment-grade bonds outperformed high yield, while corporate credit spreads widened as investors became more selective amid AI-related financing concerns.
- The Bloomberg Global Aggregate Corporate Index rose 1.6% in U.S. dollar-hedged terms, while the Bloomberg Global High Yield Index edged up 0.1% on a hedged basis.
- Global investment-grade option-adjusted spreads (OAS) widened approximately 11 bps to 96 bps, while global high-yield spreads widened approximately 39 bps to 353 bps.
- U.S. investment-grade corporate bonds, as measured by the Bloomberg U.S. Corporate Index, rose 2.2%, while the Bloomberg U.S. Corporate High Yield Index gained 0.3%.
- U.S. investment-grade spreads widened approximately 10 bps to 90 bps, while U.S. high-yield spreads widened approximately 29 bps to 340 bps.
- In securitized markets, the Bloomberg U.S. Securitized Index, which includes mortgage-backed securities (MBS), commercial mortgage-backed securities (CMBS), and asset-backed securities (ABS), rose 2.9% amid the pullback in Treasury yields. Composite spreads narrowed approximately 8 bps, with MBS spreads tightening approximately 9 bps, while CMBS and ABS spreads widened approximately 8 bps and 11 bps, respectively.
Central Bank Watch
October saw several major central banks take a patient approach to further tightening, with policymakers balancing elevated inflation risks against an uncertain growth outlook. While the Fed, ECB, and BoJ left policy unchanged, the Bank of Canada (BoC) became the latest to resume tightening, raising rates for the first time in over three years. Despite the holds elsewhere, further rate increases remain widely anticipated across several major economies before year end.
- People’s Bank of China (Oct. 20): China left its benchmark lending rates unchanged for a 17th consecutive month, maintaining the one-year and five-year loan prime rates at their existing levels. Separately, the PBOC indicated it is studying a potential shift toward making the overnight rate its primary policy rate.
- Bank of Canada (Oct. 28): The BoC raised its policy rate by 25 bps to 2.50%, as expected, marking its first rate increase since July 2023. Governor Macklem cited more persistent inflation and a resilient economy, while indicating further rate increases could be needed. Markets are currently pricing in roughly 75 bps of additional tightening over the next year.
- U.S. Federal Reserve (Oct. 28): The Fed left its benchmark policy rate unchanged at a range of 3.75%-4.00%, as widely expected, following September’s 25 bp increase. The decision passed by a 10-2 vote, with two policymakers dissenting in favor of another rate hike. Chair Kevin Warsh also announced changes to the FOMC calendar that will maintain eight meetings per year but reduce the number of rate decisions to seven in 2027 and six in 2028, with the remaining meetings dedicated to broader monetary policy strategy.
- European Central Bank (Oct. 29): The ECB kept its deposit facility rate unchanged at 2.5%, matching expectations, while flagging continued upside risks to inflation from higher energy prices and downside risks to growth. Separately, the ECB confirmed that President Christine Lagarde will step down in February, approximately nine months before the end of her term.
- Bank of Japan (Oct. 30): The BoJ left its policy rate unchanged at 1.25%, as widely expected, after raising rates in September. Policymakers continued to signal that further tightening would likely be needed as underlying inflation reached the central bank’s long-sought 2% target, with markets anticipating another 25 bp rate increase as early as December.
- Other central banks: The Reserve Bank of India (Oct. 7) raised its benchmark policy rate for the first time in nearly four years, to 5.5% from 5.25%, and shifted its policy stance to “calibrated tightening” from neutral. South Korea (Oct. 21) left rates unchanged, while signaling that future increases could be warranted amid an improved economic outlook. Turkey (Oct. 22) cut its policy rate by 100 bps to 36%, while maintaining that a tight monetary policy stance remained necessary to support disinflation. New Zealand (Oct. 28) defied expectations for a rate hike, leaving its official cash rate unchanged at 2.75% in a narrow 4-3 decision amid heightened global uncertainty.
- Looking ahead: November’s policy calendar is relatively light, with the Reserve Bank of Australia (RBA) and Bank of England (BoE) on Nov. 3 and Nov. 5, respectively, the most noteworthy rate decisions on tap. Both were widely expected to raise rates by 25 bps as of this writing. Other central bank decisions will include Brazil (Nov. 4), Mexico (Nov. 5), Indonesia (Nov. 18), South Africa (Nov. 19), and the Bank of Korea (Nov. 26).
Key events on tap in November
- Nov. 2 – Global Manufacturing PMIs (October, final)
- Nov. 3 – Reserve Bank of Australia (RBA) Rate Decision
- Nov. 3 – U.S. Midterm Elections
- Nov. 4 – Global Services PMIs (October, final)
- Nov. 4 – Eurozone Consumer Price Index (October, preliminary)
- Nov. 5 – Bank of England (BoE) Rate Decision
- Nov. 6 – U.S. Nonfarm Payrolls, Unemployment Rate (October)
- Nov. 10 – U.S. Consumer Price Index (October)
- Nov. 12 – UK Gross Domestic Product (Q3, preliminary)
- Nov. 13 – Eurozone Gross Domestic Product (Q3, second estimate)
- Nov. 16 – China October Activity Data (Industrial Production, Retail Sales)
- Nov. 18 – Eurozone Consumer Price Index (October, final)
- Nov. 18 – UK Consumer Price Index (October)
- Nov. 23 – Global PMIs (November, flash estimate)
- Nov. 25 – U.S. Gross Domestic Product (Q3, second estimate)
- Nov. 25 – U.S. Personal Consumption Expenditures (PCE) Price Index (October)
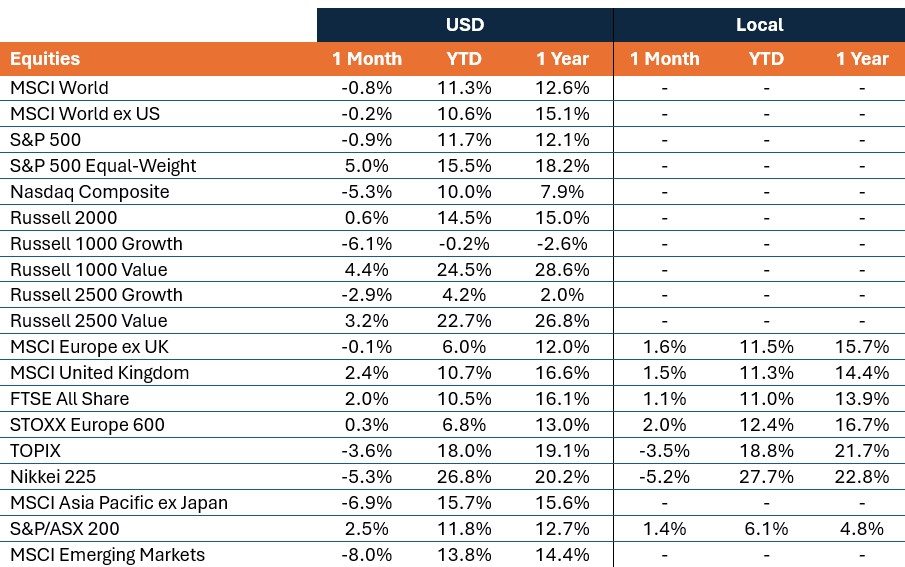
Market Performance
Total returns (%), periods ended October 31, 2026
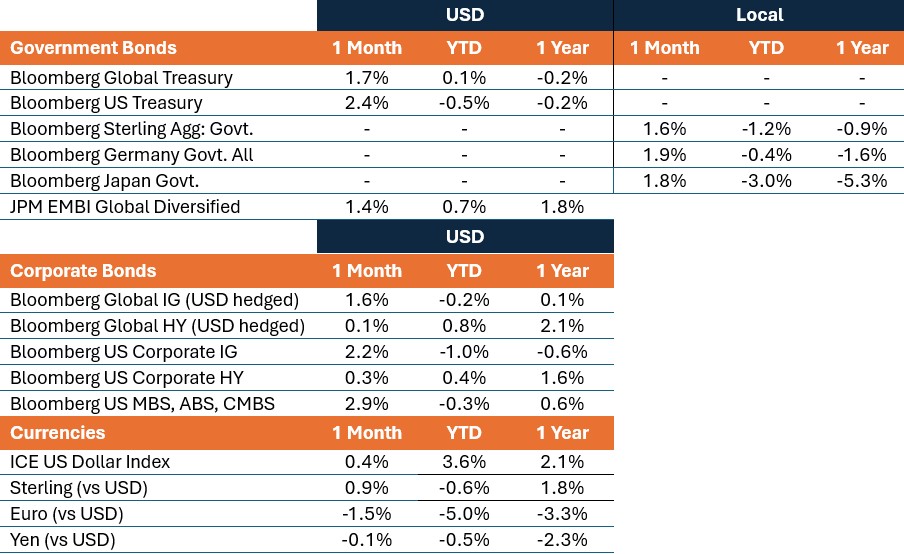
Past performance is no guarantee of future results.
IMPORTANT INFORMATION
Artificial intelligence (“AI”) focused companies, including those that develop or utilize AI technologies, may face rapid product obsolescence, intense competition, and increased regulatory scrutiny. These companies often rely heavily on intellectual property, invest significantly in research and development, and depend on maintaining and growing consumer demand. Their securities may be more volatile than those of companies offering more established technologies and may be affected by risks tied to the use of AI in business operations, including legal liability or reputational harm.
Equity securities are subject to risks including market risk. Returns will fluctuate in response to issuer, political and economic developments.
Fixed income securities are subject to interest rate, inflation, credit and default risk. As interest rates rise, bond prices usually fall, and vice versa. High-yield bonds, or “junk” bonds, involve a greater risk of default and price volatility. Foreign securities, including sovereign debt, are subject to currency fluctuations, political and economic uncertainty and increased volatility and lower liquidity, all of which are magnified in emerging markets.
Foreign securities are subject to additional risks including currency fluctuations, political and economic uncertainty, increased volatility, lower liquidity and differing financial and information reporting standards, all of which are magnified in emerging markets.
Sovereign debt securities are subject to the additional risk that, under some political, diplomatic, social or economic circumstances, some developing countries that issue lower quality debt securities may be unable or unwilling to make principal or interest payments as they come due.
Bloomberg Asian-Pacific Japan Government-Related Index is a fixed-rate, investment grade, JPY-denominated benchmark that includes debt from government-related issuers.
Bloomberg Germany Government All Bonds Index measures the performance of German government bonds (Bunds) issued by the German government.
Bloomberg Global 10+ Year Total Return Index tracks investment-grade government and government-related bonds with maturities of 10 years or greater.
Bloomberg Global Aggregate – Corporate Index is a flagship measure of global investment grade, fixed-rate corporate debt. This multi-currency benchmark includes bonds from developed and emerging markets issuers.
Bloomberg Global High Yield Index is a multi-currency flagship measure of the global high yield debt market. The index represents the union of the US High Yield, the Pan-European High Yield, and Emerging Markets (EM) Hard Currency High Yield Indices.
Bloomberg Global Treasury Index tracks fixed-rate, local currency government debt of investment grade countries, including both developed and emerging markets.
Bloomberg Sterling Aggregate: Government Index measures the performance of UK government bonds (Gilts) within the broader Bloomberg Sterling Aggregate Index, which covers the investment-grade, fixed-rate, sterling-denominated bond market.
Bloomberg US Corporate Bond Index measures the investment grade, fixed-rate, taxable corporate bond market. It includes USD-denominated securities from US and non-US issuers.
Bloomberg US Corporate High Yield Bond Index measures the USD-denominated, high yield, fixed-rate corporate bond market. Bonds from issuers with an emerging markets country of risk, based on Bloomberg EM country definition, are excluded.
Bloomberg US Securitized: MBS, ABS, and CMBS Index tracks all USD-denominated, investment grade, securitized issues within the Bloomberg US Aggregate Index.
Bloomberg US Treasury Index measures U.S. dollar-denominated, fixed-rate, nominal debt issued by the U.S. Treasury.
The DAX is a blue-chip stock market index consisting of the 40 major German companies trading on the Frankfurt Stock Exchange.
The France CAC 40 Index is a market value weighted index, composed of the 40 highest levels among the 100 highest market caps on the Paris Bourse.
FTSE All-Share Index reflects the equity market performance of the United Kingdom. The index includes nearly all eligible companies on the London Stock Exchange, covering large, mid, and small-cap stocks.
J.P. Morgan EMBI Global Diversified Index tracks U.S. dollar-denominated emerging market fixed and floating-rate debt instruments issued by sovereign and quasi-sovereign entities, with country weights capped to limit concentration in the largest issuers.
ICE U.S. Dollar Index is a benchmark measuring the U.S. dollar’s value against a basket of six major world currencies (Euro, Yen, Pound Sterling, Canadian Dollar, Swedish Krona, Swiss Franc).
MSCI AC Asia Pacific ex Japan Index reflects the equity market performance of the Asia Pacific region, excluding Japan, covering both developed and emerging markets.
MSCI ACWI ex USA Index captures large- and mid-cap representation across 22 of 23 developed markets (excluding the US) and 24 emerging markets countries.
MSCI China Index captures large and mid cap representation across China A shares, H shares, B shares, Red chips, P chips and foreign listings (e.g. ADRs).
MSCI Emerging Markets Index reflects the equity market performance of emerging markets.
MSCI Emerging Markets (EM) Latin America Index captures large and mid cap representation across Emerging Markets (EM) countries in Latin America. The index covers approximately 85% of the free float-adjusted market capitalization in each country.
MSCI Europe Index reflects the equity market performance of large and mid-sized companies listed in developed markets in Europe.
MSCI Europe ex UK Index reflects the equity market performance of large and mid-sized companies listed in developed markets in Europe excluding the United Kingdom.
MSCI United Kingdom Index reflects the equity market performance of large and mid-sized companies listed in the UK market.
MSCI World Index reflects the equity market performance of global developed markets.
MSCI World ex USA Index reflects the equity market performance of global developed markets excluding the United States.
NASDAQ Composite Stock Index: National Association of Securities Dealers Automated Quotation System (NASDAQ) is a nationwide computerized quotation system for over 5,500 over-the-counter stocks. The index is compiled of more than 4,800 stocks that are traded via this system.
Nikkei 225 Index (also known as Nikkei Stock Average): A measure of Japanese equity market performance. The index includes 225 of the largest companies listed on the Tokyo Stock Exchange.
PHLX Semiconductor Sector Index (SOX) is a specialized, modified market capitalization-weighted index composed of companies primarily involved in the design, distribution, manufacture, and sale of semiconductors.
Purchasing Managers’ Index (PMI) is an index of the prevailing direction of economic trends in the manufacturing and service sectors, based on a survey of private sector companies.
Russell 1000® Growth Index reflects the performance of U.S. large-cap equities with higher price-to-book ratios and higher forecasted growth values.
Russell 1000® Value Index reflects the performance of U.S. large-cap equities with lower price-to-book ratios and lower forecasted growth values.
Russell 2000® Index reflects the performance of U.S. small-cap equities.
Russell 2500™ Growth Index reflects the performance of U.S. small to mid-cap equities with higher price-to-book ratios and higher forecasted growth values.
Russell 2500™ Value Index reflects the performance of U.S. small to mid-cap equities with lower price-to-book ratios and lower forecasted growth values.
S&P 500® Index reflects U.S. large-cap equity performance and represents broad U.S. equity market performance.
S&P 500® Equal Weight Index (EWI) is the equal-weight version of the S&P 500. The index includes the same constituents as the capitalization weighted index, but each company is allocated a fixed weight – or 0.2% of the index total at each quarterly rebalance.
S&P/ASX 200 Index reflects the performance of the 200 largest, most liquid companies listed on the Australian Securities Exchange (ASX).
STOXX Europe 600 Index: An index of the 600 largest listed stocks in the European equity market, comprising 17 countries and 11 industries.
TOPIX: A capitalization-weighted index of all the companies listed on the First Section of the Tokyo Stock Exchange and is widely regarded as a broad benchmark for Japanese stock prices.
10-Year Treasury Yield is the interest rate on U.S. Treasury bonds that will mature 10 years from the date of purchase.
Agency Mortgage-backed Securities (Agency MBS): A type of asset-backed security that is specifically secured by a collection of mortgages.
Asset-backed Securities (ABS): These are financial instruments that are backed by a pool of assets—typically those that generate a cash flow from debt, such as loans, leases, credit card balances, or receivables.
Basis point: One basis point (bp) equals 1/100 of a percentage point, 1bp = 0.01%.
Bund yield: Bund yields are viewed as benchmark yield indicators for European government bonds; those with a 10-year maturity are considered to be the German equivalent of U.S. Treasury bonds.
Commercial Mortgage-backed Securities (CMBS): A type of mortgage-backed security that is secured by the loan on commercial real estate properties rather than residential real estate.
Consumer Price Index (CPI): A measure that examines the price change of a basket of consumer goods and services over time. It is used to estimate inflation.
Credit spread: The difference in yield between securities with similar maturity but different credit quality. Widening spreads generally indicate deteriorating creditworthiness of corporate borrowers, and narrowing indicate improving.
Curve/Yield curve: A yield curve plots the yields (interest rate) of bonds with equal credit quality but differing maturity dates. Typically bonds with longer maturities have higher yields.
The Federal Open Market Committee (FOMC) is the body of the Federal Reserve System that sets national monetary policy.
Fiscal policy: Describes government policy relating to setting tax rates and spending levels. Fiscal policy is separate from monetary policy, which is typically set by a central bank.
Free cash flow (FCF) yield is a financial ratio that measures how much cash flow a company has in case of its liquidation or other obligations by comparing the free cash flow per share with the market price per share and indicates the level of cash flow the company will earn against its share market value.
Frontier markets are smaller, less accessible, and earlier-stage developing economies that sit between traditional developing nations and more mature emerging markets.
Gilt yield: Gilt yields are viewed as benchmark yield indicators for United Kingdom government bonds; those with a 10-year maturity are considered to be the UK equivalent of U.S. Treasury bonds.
Hawkish policy aims to curb inflation and slow down growth in the economy by raising interest rates and reducing the supply of money.
High yield bond: Also known as a sub-investment grade bond, or ‘junk’ bond. These bonds usually carry a higher risk of the issuer defaulting on their payments, so they are typically issued with a higher interest rate (coupon) to compensate for the additional risk.
Inflation: The rate at which the prices of goods and services are rising in an economy. The Consumer Price Index (CPI) and Retail Price Index (RPI) are two common measures.
Investment grade bond: A bond typically issued by governments or companies perceived to have a relatively low risk of defaulting on their payments, reflected in the higher rating given to them by credit ratings agencies.
JGB yield: JGB yields are viewed as benchmark yield indicators for Japanese government bonds; those with a 10-year maturity are considered to be the Japanese equivalent of U.S. Treasury bonds.
Magnificent 7: A group of seven dominant tech companies – Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla – that have helped drive strong returns in the US stock market in recent years. Neocloud companies are specialized cloud providers built specifically to rent out high-performance graphics processing units (GPUs) and infrastructure for artificial intelligence workloads.
Monetary policy: The policies of a central bank, aimed at influencing the level of inflation and growth in an economy. Monetary policy tools include setting interest rates and controlling the supply of money. Dovish policy aims to stimulate economic growth by lowering interest rates and increasing the money supply.
Option-Adjusted Spread (OAS) measures the spread between a fixed-income security rate and the risk-free rate of return, which is adjusted to take into account an embedded option.
Securitization: The process in which certain types of assets are pooled so that they can be repackaged into interest-bearing securities. The interest and principal payments from the assets are passed through to the purchasers of the securities.
U.S. Treasury securities are direct debt obligations issued by the U.S. Government. Treasury Bills and U.S. Government Bonds are guaranteed by the full faith and credit of the U.S. government, are generally considered to be free of credit risk.
Volatility measures risk using the dispersion of returns for a given investment.
Yield: The level of income on a security over a set period, typically expressed as a percentage rate. For equities, a common measure is the dividend yield, which divides recent dividend payments for each share by the share price. For a bond, this is calculated as the coupon payment divided by the current bond price.