Please ensure Javascript is enabled for purposes of website accessibility UK Investment Trusts
Back to Insights

Why the highest dividend yield isn’t always the best investment

A dividend yield of 8% may look more attractive than one of 4%, but a high yield can be a misleading sign of value. Henderson High Income Trust’s (HHI) fund manager David Smith explains why exceptionally high yields can sometimes be a warning signal and what investors should look for instead.

Income investors are naturally drawn to companies offering attractive dividend yields. The appeal is easy to understand. If one share offers a yield of 8% and another offers 4%, the first may appear to provide twice as much income.

But that comparison only tells us what the shares are yielding today. It says nothing about whether the dividend can be sustained, whether the business can grow or what might happen to the investor’s capital.

Indeed, an exceptionally high yield is sometimes less a sign of opportunity than a warning from the market.

What is the market telling us?

A company’s dividend yield is calculated by comparing the annual dividend with its share price. As the share price falls, the yield rises, provided the dividend remains unchanged.
This means a rising yield does not necessarily reflect a company becoming more profitable. It may indicate that investors are increasingly concerned about its earnings, balance sheet or ability to maintain the dividend.

If investors expect profits to weaken and the dividend to be reduced, the apparent yield can become very high shortly before the dividend is cut or passed.

This is the classic yield trap: a share looks cheap and offers a seemingly exceptional level of income, but the dividend proves unsustainable and the investor suffers both a reduction in income and a fall in capital.

That does not mean every high-yielding share should be avoided. There are occasions when the market becomes too pessimistic and creates a genuine opportunity. But a high yield should be the beginning of the analysis, not its conclusion.

The sweet spot is often in the middle

Historical data shows that companies with moderate dividend yields have often generated stronger total returns than those at either end of the yield spectrum. Very low-yielding companies provide little immediate income, while the highest-yielding shares offer limited dividend growth and can include businesses facing pressures to sustain their dividend.

The more interesting area is often in the middle: companies able to pay a worthwhile dividend while retaining enough cash to invest in their operations to support future dividend growth.
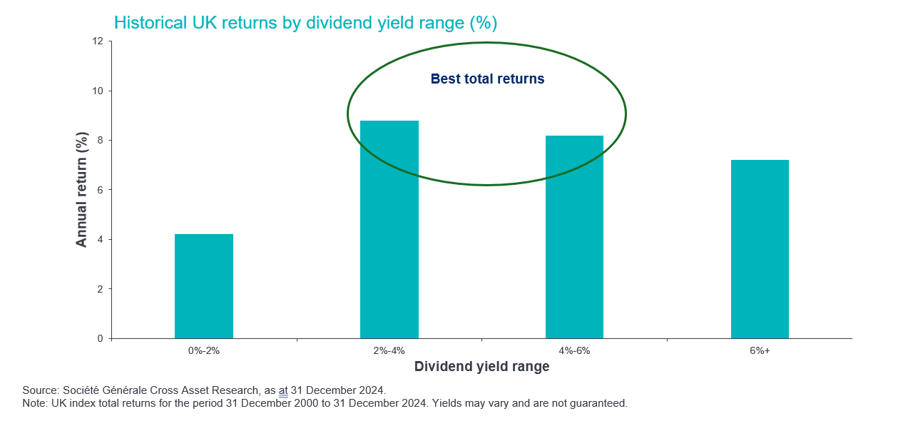
The highest yielding stocks have not delivered the strongest return

Historically, UK shares with moderate dividend yields have often generated stronger total returns than both low-yielding and very high-yielding shares. Past performance is not a guide to future returns.

This balance matters because dividends do not exist independently of the business. They ultimately have to be funded by profits and cash flow. A company that distributes too much today may leave itself with too little to invest for tomorrow.

Conversely, a business that can grow its earnings and cash generation may be able to increase its dividend progressively, even if its starting yield is not the highest in the market.

For a long-term income investor, a 4% dividend yield capable of growing may prove more valuable than an 8% yield that becomes unsustainable.

In conclusion

A high dividend yield can be an attractive starting point, but successful income investing involves looking beyond the headline number. Cash generation, financial strength and growth prospects all play a role in determining whether a dividend can be sustained over the long term.

The highest yield may occasionally lead to an overlooked opportunity. Just as often, it raises an important question: what risk has the market already identified?

Either way, yield should be treated as the start of the analysis, not the conclusion.

The next article in this series explores three important questions that can help investors evaluate income opportunities and assess the long-term sustainability of dividends, highlighting why factors such as cash generation, growth potential and valuation matter just as much as headline yield.
Dividend

A variable discretionary payment made by a company to its shareholders.

Share price

The price to purchase (or sell) one share in a company, not including fees or taxes. For investment trusts: The closing mid-market share price at month end.

Yield

The level of income on a security over a set period, typically expressed as a percentage rate. For equities, a common measure is the dividend yield, which divides recent dividend payments for each share by the share price. For a bond, in its simplest form, this is calculated as the coupon payment divided by the current bond price.

These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.


Before investing in an investment trust referred to in this article, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Tax assumptions and reliefs depend upon an investor’s particular circumstances and may change if those circumstances or the law change.


Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.


The information in this article does not qualify as an investment recommendation.


There is no guarantee that past trends will continue, or forecasts will be realised.


Marketing Communication.


Glossary


Important information

Please read the following important information regarding funds related to this article.

Before investing in an investment trust referred to in this document, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. This is a marketing communication. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions.
    Specific risks
  • Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
  • Some of the administrative expenses are taken from capital. This allows more income to be paid but it may also restrict capital growth or even reduce the capital over time.
  • Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
  • If a Company's portfolio is concentrated towards a particular country or geographical region, the investment carries greater risk (as well as the potential for greater reward) than a portfolio that is diversified across more countries.
  • This investment should be held as part of a broader diversified portfolio. Balancing it with investments that have different risk profiles can help reduce the impact of any single investment underperforming.
  • The Company may borrow to invest, which could magnify gains or losses.
  • As the Company may borrow to invest, changes in interest rates could increase or decrease the cost of any borrowings.
  • The Company invests in debt securities, exposing the portfolio to credit risk. This means that the issuer of a bond which may be held in the portfolio, could become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
  • The Company invests in the shares of other companies. These shares may become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
  • Your return on investment is directly related to the market price of the Company's shares, which may be higher (trading at a premium) or lower (trading at a discount) than the value of its underlying net asset value assets. This means your returns may differ from the performance of those assets.
  • While active management techniques are typically positive for performance, this approach may also result in periods of underperformance relative to the benchmark and comparable passive and index-tracking funds, particularly during unexpected market shifts.
  • Shares can gain and lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may rise and fall in line with the underlying equity markets.
  • If the companies in which the portfolio is invested persistently reduce their dividend payments, the Company will find it more difficult to maintain or grow its own dividend payments each year.
  • The Company maintains a portfolio with a bias towards income-generating companies. This may result in the Company significantly underperforming or outperforming the wider market.