Please ensure Javascript is enabled for purposes of website accessibility UK Investment Trusts
Back to Insights

UK equities: Income today, growth tomorrow?

The UK market has been overlooked by many investors in recent years. Lowland Investment Company’s fund manager Laura Foll explains why attractive valuations, reliable dividend income and global business exposure could make UK shares worth a closer look.

The UK equity market has spent much of the past decade out of favour, with weak sentiment and subdued domestic growth weighing on investor appetite. Yet this overlooks a key point: the UK economy and stock market are not the same.

Many UK-listed companies generate a significant share of revenues overseas, meaning investors can access global businesses at discounted valuations. In simple terms, investors may be able to buy shares in companies with international operations at lower prices than similar businesses listed elsewhere. For patient investors, this may create an opportunity to capture both income and capital growth where expectations remain low.

Out of favour creates opportunity

UK equities continue to be seen as a contrarian allocation, allowing valuation gaps to persist even as fundamentals improve. Over time, however, earnings and valuations tend to reconnect. In other words, if a company’s profits continue to improve, its share price often follows eventually, even if investors are sceptical in the short term.

Identifying companies where sentiment is anchored to the past while operational performance strengthens is key to unlocking returns.

Valuation and income: A powerful combination

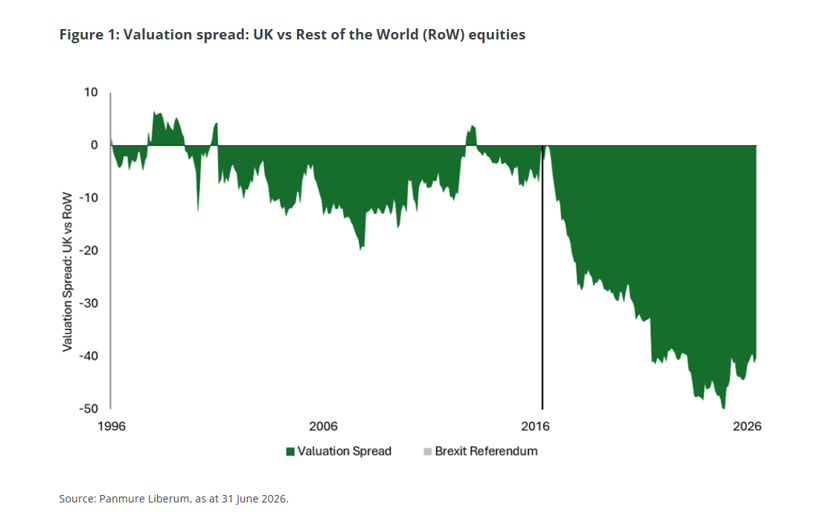
The UK market trades at a significant discount to global peers (Figure 1), particularly the US. This means investors can currently buy many UK companies at lower share price valuations than comparable businesses in other major markets. While valuation alone is not a catalyst, it becomes compelling when paired with improving fundamentals, such as company’s profits, cash flows and business outlook.

This also supports dividend income. Higher yields allow investors to be paid while waiting for sentiment to recover. Ongoing takeover activity further suggests strategic buyers recognise value that public markets may still overlook.

Figure 1: UK shares remain cheaper than many overseas markets. The further below zero the line falls, the cheaper UK equities are relative to the rest of the world. Historically, valuation gaps of this size have been uncommon.
Global exposure at UK prices

A common misconception is that UK equities reflect purely domestic growth. In reality, many companies have substantial international exposure.

Zigup, a commercial vehicle rental provider, is a good example. While it is often seen as a UK-focused business, its operations in Spain are helping to drive growth and improve profitability. This shows how some UK-listed companies can benefit from growth overseas, even when sentiment towards the UK remains weak, creating opportunities that may not yet be reflected in their share prices.

Income as ‘patient capital’

Dividend income remains a defining feature of UK equities. Beyond providing returns, it enables investors to hold positions through uncertainty.

Business recoveries rarely happen quickly. Companies such as Halfords, Marshalls and Hilton Food are focused on improving performance and building on their strengths, but it can take time for these efforts to be reflected in results. During this period, dividend income can provide investors with a return while they wait for the company’s prospects to improve.

Turning points and structural growth

New management and strategic change can unlock value, as seen in companies like Marks & Spencer and Babcock. These turning points are often underappreciated early on.

At the same time, companies do not need a strong UK economy to deliver growth. While GDP (Gross Domestic Product) measures economic activity, businesses can still grow profits even when overall GDP growth is modest. Longer-term trends, such as increased investment in infrastructure and defence, are supporting companies such as Costain, Balfour Beatty and Babcock. These trends could help drive demand for their products and services for many years to come.

Conclusion: Paid to wait for potential

UK equities remain overlooked, but that is where opportunity lies. Low valuations, strong income and underappreciated growth drivers create a compelling combination.

For investors, the appeal is balance: income provides stability and patience, while improving fundamentals offer capital growth potential. In many cases, investors are being paid to wait for that growth to emerge.
Balance sheet

A financial statement that summarises a company’s assets, liabilities and shareholders’ equity at a particular point in time.

Benchmark

A standard (usually an index) that an investment portfolio’s performance can be measured against.

Blue chip stock

Stock issued by a widely known, well-established and financially stable company, typically with a long record of reliable and stable growth, and often with a track record of paying dividends to investors.

Buy and hold

An investment strategy where an investment is purchased with the intention of being retained for a long period of time, regardless of short-term fluctuations in the market.

Capital

The financial value invested in a company or investment portfolio.

Capital expenditure

Money invested to acquire or upgrade fixed assets such as buildings, machinery, equipment or vehicles in order to maintain or improve operations and foster future growth.

Cash flow

The net balance of cash that moves in and out of a company. Positive cash flow shows more money is moving in than out, while negative cash flow means more money is moving out than into the company.

Discount/premium (investment trusts)

The amount by which the price-per-share of an investment company is either lower (at a discount) or higher (at a premium) than the net-asset value per share (cum income), expressed as a percentage of the net-asset value per share.

Dividend

A variable, discretionary payment made by a company to its shareholders.

Dividend yield

A stock’s annual dividend payments to shareholders expressed as a percentage of the stock’s current price.

Valuation

The analytical process of determining the current economic worth (fair value) of an asset, security or company.


These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.


Before investing in an investment trust referred to in this article, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Tax assumptions and reliefs depend upon an investor’s particular circumstances and may change if those circumstances or the law change.


Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.


The information in this article does not qualify as an investment recommendation.


There is no guarantee that past trends will continue, or forecasts will be realised.


Marketing Communication.


Glossary


Important information

Please read the following important information regarding funds related to this article.

Before investing in an investment trust referred to in this document, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. This is a marketing communication. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions.
    Specific risks
  • Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
  • Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
  • Some of the administrative expenses are taken from capital. This allows more income to be paid but it may also restrict capital growth or even reduce the capital over time.
  • If a Company's portfolio is concentrated towards a particular country or geographical region, the investment carries greater risk (as well as the potential for greater reward) than a portfolio that is diversified across more countries.
  • This investment should be held as part of a broader diversified portfolio. Balancing it with investments that have different risk profiles can help reduce the impact of any single investment underperforming.
  • The Company may borrow to invest, which could magnify gains or losses.
  • As the Company may borrow to invest, changes in interest rates could increase or decrease the cost of any borrowings.
  • The Company invests in the shares of other companies. These shares may become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
  • Your return on investment is directly related to the market price of the Company's shares, which may be higher (trading at a premium) or lower (trading at a discount) than the value of its underlying net asset value assets. This means your returns may differ from the performance of those assets.
  • While active management techniques are typically positive for performance, this approach may also result in periods of underperformance relative to the benchmark and comparable passive and index-tracking funds, particularly during unexpected market shifts.
  • Shares can gain and lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may rise and fall in line with the underlying equity markets.
  • If the companies in which the portfolio is invested persistently reduce their dividend payments, the Company will find it more difficult to maintain or grow its own dividend payments each year.
  • The Company maintains a portfolio with a bias towards income-generating companies. This may result in the Company significantly underperforming or outperforming the wider market.