Please ensure Javascript is enabled for purposes of website accessibility UK Investment Trusts
Back to Insights

What successful dividend growers have in common

RELX, Cranswick and Intermediate Capital Group operate in very different industries, but they share several characteristics that have helped them deliver years of profit growth, rising dividends and strong shareholder returns. Henderson High Income Trust's fund manager David Smith explains what income investors can learn from their success.

The previous article, Beyond yield: three questions every income investor should ask, explored how sustainable dividends, disciplined capital allocation and sensible valuations are key inputs to find attractive income investments

These principles are important because the strongest long-term outcomes are not always generated by the highest-yielding shares. Companies that can grow their earnings, cash flows and dividends over many years often deliver stronger total returns than companies with just a high dividend yield.

Several long-term holdings in the HHI portfolio help illustrate this approach in practice.

RELX

RELX  provides data, analytics and information services to professionals working in fields such as healthcare, law, insurance and scientific research. The company’s value lies less in physical assets and more in the information, data and insights that its customers use every day to make important decisions.

Over many years, RELX has invested consistently in its data and technology platforms at attractive returns to generate good organic growth. But it has balanced this with shareholder returns, paying out approximately 50% of cash flow each year as a dividend.  Over the last 10 years the company has grown its dividend by an average 8.5% per year.

This compounding impact of growing dividends has had a significant impact for investors with the stock delivering a 187% 10-year total return since the end of 2015.  More recently, artificial intelligence has provided another opportunity to increase the value of its datasets and analytical tools, helping customers extract more insight from the proprietary data and analytics RELX provides.

Cranswick

Cranswick supplies pork and chicken products to supermarkets and food service businesses in the UK. It operates in an industry where growth is often driven less by breakthrough innovation and more by investments to maximise quality, service and value for customers. This constant investment at good returns has seen Cranswick grow with its customers, winning market share, expanding categories and increasing capacity leading to sustainable profit, cash flow and dividend growth.

This year the company delivered its 36th year of consecutive dividend growth.  The power of that dividend growth has also delivered for investors in total returns, with the stock returning 247% over the last 10 years.

Intermediate Capital Group (ICG)

ICG shows how companies can create value by adapting and expanding their business over time.

Originally focused on private lending to businesses, ICG has evolved into a global alternative asset manager, investing on behalf of pension funds, insurers and other institutions. This shift has created new opportunities for growth and helped the company generate more consistent earnings and cash flow.  They have also invested to diversify the business into other private asset classes underpinning its dividend growth.

The business has increased its dividend for 16 consecutive years, with annual dividend growth averaging around 11% over that period.

ICG’s success shows that businesses do not need to stand still to remain successful. Companies that adapt, grow and seize new opportunities can often create significant value for shareholders, with ICG delivering a 10-year total return of 394%.
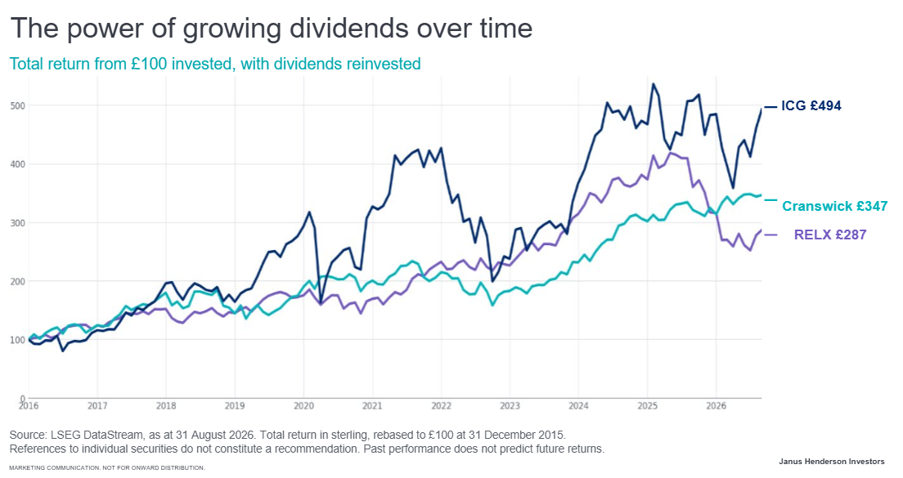
RELX, Cranswick and ICG may operate in different industries, but they share a common characteristic: each have invested appropriately to grow their businesses while increasing the income paid to shareholders.

Their stories highlight an important lesson for income investors. The highest-yielding shares are not always the most attractive opportunities. Companies that can steadily grow their profits and dividends often have the potential to deliver stronger long-term outcomes.

That’s why dividend growth is just as important as dividend yield when investing for the long term.

The final article in this series explores another way of building portfolio income, examining how a combination of equities and bonds can offer exposure to a wider range of income sources while supporting portfolio diversification.

Cash flow

The net balance of cash that moves in and out of a company. Positive cash flow shows more money is moving in than out, while negative cash flow means more money is moving out than into the company.

Dividend

A variable discretionary payment made by a company to its shareholders.

Portfolio

A grouping of financial assets such as equities, bonds, commodities, properties, or cash. Also often called a ‘fund’.

Valuation metrics

Metrics used to gauge a company’s performance, financial health, and expectations for future earnings, e.g. P/E ratio and ROE.

Yield

The level of income on a security over a set period, typically expressed as a percentage rate. For equities, a common measure is the dividend yield, which divides recent dividend payments for each share by the share price. For a bond, in its simplest form, this is calculated as the coupon payment divided by the current bond price.

Important information

Holdings are subject to change without notice. Yields may vary and are not guaranteed.

Use of third party names, marks or logos is purely for illustrative purposes and does not imply any association between any third party and Janus Henderson Investors, nor any endorsement or recommendation by or of any third party. Unless stated otherwise, trademarks are the exclusive property of their respective owners.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.


Before investing in an investment trust referred to in this article, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Tax assumptions and reliefs depend upon an investor’s particular circumstances and may change if those circumstances or the law change.


Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.


The information in this article does not qualify as an investment recommendation.


There is no guarantee that past trends will continue, or forecasts will be realised.


Marketing Communication.


Glossary


Important information

Please read the following important information regarding funds related to this article.

Before investing in an investment trust referred to in this document, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. This is a marketing communication. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions.
    Specific risks
  • Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
  • Some of the administrative expenses are taken from capital. This allows more income to be paid but it may also restrict capital growth or even reduce the capital over time.
  • Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
  • If a Company's portfolio is concentrated towards a particular country or geographical region, the investment carries greater risk (as well as the potential for greater reward) than a portfolio that is diversified across more countries.
  • This investment should be held as part of a broader diversified portfolio. Balancing it with investments that have different risk profiles can help reduce the impact of any single investment underperforming.
  • The Company may borrow to invest, which could magnify gains or losses.
  • As the Company may borrow to invest, changes in interest rates could increase or decrease the cost of any borrowings.
  • The Company invests in debt securities, exposing the portfolio to credit risk. This means that the issuer of a bond which may be held in the portfolio, could become unable or unwilling to pay interest or repay capital. If this happens or the market perceives this may happen, the value of the bond will fall.
  • The Company invests in the shares of other companies. These shares may become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
  • Your return on investment is directly related to the market price of the Company's shares, which may be higher (trading at a premium) or lower (trading at a discount) than the value of its underlying net asset value assets. This means your returns may differ from the performance of those assets.
  • While active management techniques are typically positive for performance, this approach may also result in periods of underperformance relative to the benchmark and comparable passive and index-tracking funds, particularly during unexpected market shifts.
  • Shares can gain and lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may rise and fall in line with the underlying equity markets.
  • If the companies in which the portfolio is invested persistently reduce their dividend payments, the Company will find it more difficult to maintain or grow its own dividend payments each year.
  • The Company maintains a portfolio with a bias towards income-generating companies. This may result in the Company significantly underperforming or outperforming the wider market.