The UK equity market has spent much of the past decade out of favour, with weak sentiment and subdued domestic growth weighing on investor appetite. Yet this overlooks a key point: the UK economy and stock market are not the same.
Many UK-listed companies generate a significant share of revenues overseas, meaning investors can access global businesses at discounted valuations. In simple terms, investors may be able to buy shares in companies with international operations at lower prices than similar businesses listed elsewhere. For patient investors, this may create an opportunity to capture both income and capital growth where expectations remain low.
UK equities continue to be seen as a contrarian allocation, allowing valuation gaps to persist even as fundamentals improve. Over time, however, earnings and valuations tend to reconnect. In other words, if a company’s profits continue to improve, its share price often follows eventually, even if investors are sceptical in the short term.
Identifying companies where sentiment is anchored to the past while operational performance strengthens is key to unlocking returns.
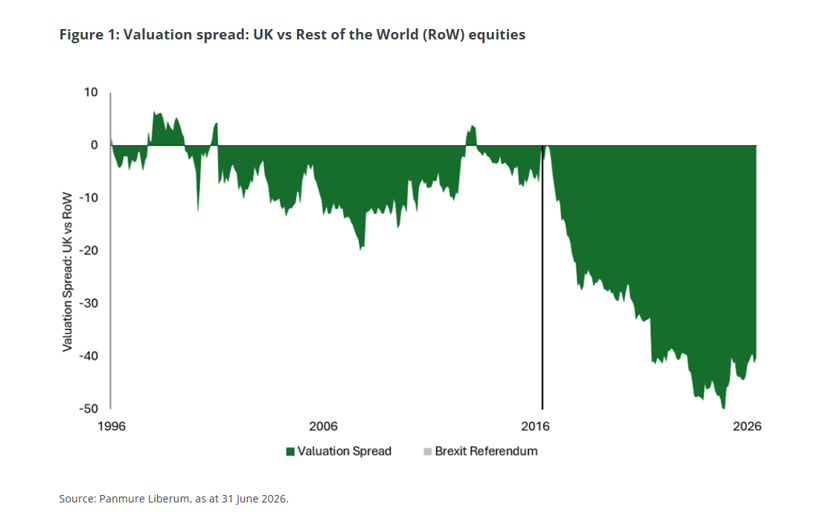
The UK market trades at a significant discount to global peers (Figure 1), particularly the US. This means investors can currently buy many UK companies at lower share price valuations than comparable businesses in other major markets. While valuation alone is not a catalyst, it becomes compelling when paired with improving fundamentals, such as company’s profits, cash flows and business outlook.
This also supports dividend income. Higher yields allow investors to be paid while waiting for sentiment to recover. Ongoing takeover activity further suggests strategic buyers recognise value that public markets may still overlook.
Figure 1: UK shares remain cheaper than many overseas markets. The further below zero the line falls, the cheaper UK equities are relative to the rest of the world. Historically, valuation gaps of this size have been uncommon.
A common misconception is that UK equities reflect purely domestic growth. In reality, many companies have substantial international exposure.
Zigup, a commercial vehicle rental provider, is a good example. While it is often seen as a UK-focused business, its operations in Spain are helping to drive growth and improve profitability. This shows how some UK-listed companies can benefit from growth overseas, even when sentiment towards the UK remains weak, creating opportunities that may not yet be reflected in their share prices.
Dividend income remains a defining feature of UK equities. Beyond providing returns, it enables investors to hold positions through uncertainty.
Business recoveries rarely happen quickly. Companies such as Halfords, Marshalls and Hilton Food are focused on improving performance and building on their strengths, but it can take time for these efforts to be reflected in results. During this period, dividend income can provide investors with a return while they wait for the company’s prospects to improve.
New management and strategic change can unlock value, as seen in companies like Marks & Spencer and Babcock. These turning points are often underappreciated early on.
At the same time, companies do not need a strong UK economy to deliver growth. While GDP (Gross Domestic Product) measures economic activity, businesses can still grow profits even when overall GDP growth is modest. Longer-term trends, such as increased investment in infrastructure and defence, are supporting companies such as Costain, Balfour Beatty and Babcock. These trends could help drive demand for their products and services for many years to come.
UK equities remain overlooked, but that is where opportunity lies. Low valuations, strong income and underappreciated growth drivers create a compelling combination.
For investors, the appeal is balance: income provides stability and patience, while improving fundamentals offer capital growth potential. In many cases, investors are being paid to wait for that growth to emerge.