Income investors are naturally drawn to companies offering attractive dividend yields. The appeal is easy to understand. If one share offers a yield of 8% and another offers 4%, the first may appear to provide twice as much income.
But that comparison only tells us what the shares are yielding today. It says nothing about whether the dividend can be sustained, whether the business can grow or what might happen to the investor’s capital.
Indeed, an exceptionally high yield is sometimes less a sign of opportunity than a warning from the market.
A company’s dividend yield is calculated by comparing the annual dividend with its share price. As the share price falls, the yield rises, provided the dividend remains unchanged.
This means a rising yield does not necessarily reflect a company becoming more profitable. It may indicate that investors are increasingly concerned about its earnings, balance sheet or ability to maintain the dividend.
If investors expect profits to weaken and the dividend to be reduced, the apparent yield can become very high shortly before the dividend is cut or passed.
This is the classic yield trap: a share looks cheap and offers a seemingly exceptional level of income, but the dividend proves unsustainable and the investor suffers both a reduction in income and a fall in capital.
That does not mean every high-yielding share should be avoided. There are occasions when the market becomes too pessimistic and creates a genuine opportunity. But a high yield should be the beginning of the analysis, not its conclusion.
Historical data shows that companies with moderate dividend yields have often generated stronger total returns than those at either end of the yield spectrum. Very low-yielding companies provide little immediate income, while the highest-yielding shares offer limited dividend growth and can include businesses facing pressures to sustain their dividend.
The more interesting area is often in the middle: companies able to pay a worthwhile dividend while retaining enough cash to invest in their operations to support future dividend growth.
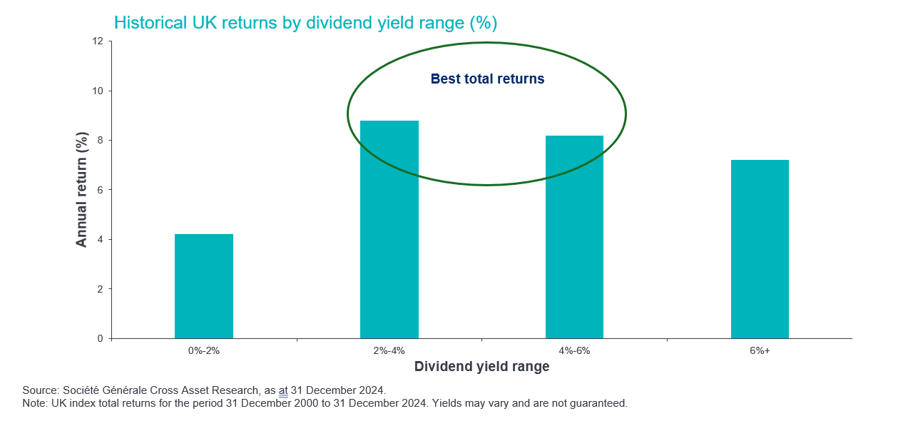
Historically, UK shares with moderate dividend yields have often generated stronger total returns than both low-yielding and very high-yielding shares. Past performance is not a guide to future returns.
This balance matters because dividends do not exist independently of the business. They ultimately have to be funded by profits and cash flow. A company that distributes too much today may leave itself with too little to invest for tomorrow.
Conversely, a business that can grow its earnings and cash generation may be able to increase its dividend progressively, even if its starting yield is not the highest in the market.
For a long-term income investor, a 4% dividend yield capable of growing may prove more valuable than an 8% yield that becomes unsustainable.
A high dividend yield can be an attractive starting point, but successful income investing involves looking beyond the headline number. Cash generation, financial strength and growth prospects all play a role in determining whether a dividend can be sustained over the long term.
The highest yield may occasionally lead to an overlooked opportunity. Just as often, it raises an important question: what risk has the market already identified?
Either way, yield should be treated as the start of the analysis, not the conclusion.
The next article in this series explores three important questions that can help investors evaluate income opportunities and assess the long-term sustainability of dividends, highlighting why factors such as cash generation, growth potential and valuation matter just as much as headline yield.