Please ensure Javascript is enabled for purposes of website accessibility Hidden Gems: Hill & Smith | Janus Henderson Investment Trusts | UK Investment Trusts

CTY

The City of London Investment Trust plc

Hidden Gems: Hill & Smith

The infrastructure behind everyday life isn’t always visible, but it plays a vital role in economic growth. Discover Hill & Smith, a company helping keep roads, energy networks and data centres running.

Everyone knows the big names of the UK stock market – companies like Unilever, BP or HSBC that dominate headlines and investor attention. But beyond these household names sits a much larger group of UK smaller companies that receive far less coverage, despite playing important roles in the economy.

Through our Hidden Gems series, we shine a light on some of the under‑the‑radar businesses The Henderson Smaller Companies Investment Trust invests in – explaining what they do, why they matter, and the key factors we focus on when identifying long‑term opportunities early.

Hill & Smith – Building the foundations behind everyday infrastructure

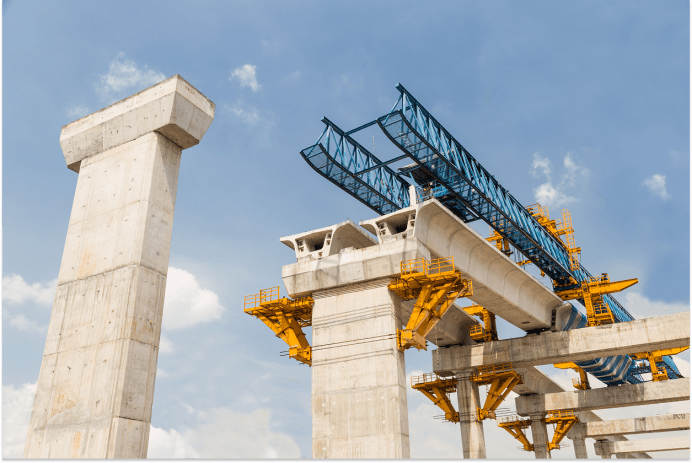
Some companies don’t sit in the spotlight, but their products are all around us. From roads and bridges to energy networks and data centres, modern infrastructure depends on businesses that quietly keep things running.

Hill & Smith is one of those companies. Founded in 1824 and listed on the London Stock Exchange in 1969, it has evolved into an international infrastructure products and services group, with operations across the US, UK and India. Today, the US is its largest driver of earnings and growth, reflecting the scale of infrastructure investment currently underway.

Rather than building infrastructure itself, Hill & Smith focuses on supplying the specialist products and services that support it – for example helping protect steel used in roads, bridges and energy networks so it lasts longer. That behind‑the‑scenes role makes it an important enabler of long‑term economic growth.

Why this matters now

Infrastructure investment is rising globally, driven by the need to modernise ageing assets, support energy transition, and build capacity for a more digital economy.

In the US in particular, government initiatives are channelling significant funding into areas such as transport, energy networks and data centres – providing strong visibility of demand for years to come. This creates a supportive backdrop for companies like Hill & Smith, whose products are used throughout these projects.

A business built for long-term growth

What stands out about Hill & Smith is not just what it does, but how it grows. Demand for its products tends to be steady, and the company expands in a measured, disciplined way.

A key part of this is acquisitions. Management has a strong track record of buying smaller, complementary businesses in niche infrastructure markets, often at sensible valuations. These acquisitions have consistently added to both revenue growth and profitability over time.

This is supported by a decentralised operating structure, where local management teams run individual businesses. This allows decisions to be made close to customers, helping the group remain responsive while maintaining the financial strength of a larger organisation.

Hill & Smith at a glance

What the company does Hill & Smith supplies infrastructure products and services, including engineered solutions and protective coatings for steel used in construction and industrial projects.
Why this matters now Growing investment in infrastructure – particularly in the US – is driving demand for the products needed to build, maintain and upgrade essential assets.
How it makes money The group generates revenue through a mix of product sales and services across three core divisions, with a growing contribution from higher-margin US operations.
What’s changing The business is increasingly focused on the US, where strong structural growth drivers and supportive policy are creating long-term opportunities. Ongoing acquisitions continue to expand its capabilities and market reach.
What we like A high-quality business with a strong track record of returns on invested capital, resilient demand, and a proven track record of reinvesting profits to drive steady growth. Its exposure to essential infrastructure gives it a durable role in the economy.
What could go right Continued infrastructure spending, combined with successful acquisitions, could help the company grow earnings steadily over time – with more of each pound of revenue translating into profit.
What we’re watching Execution of the acquisition strategy, continued strength in US markets, and the group’s ability to maintain strong returns as it scales.


Earnings per share (EPS)

EPS is the bottom-line measure of a company’s profitability, defined as net income (profit after tax) divided by the number of outstanding shares.

Profit margin

The amount by which the sales of a product or service exceeds business and production costs.

Valuation metrics

Metrics used to gauge a company’s performance, financial health, and expectations for future earnings, e.g. P/E ratio and ROE.

Important Information

Use of third party names, marks or logos is purely for illustrative purposes and does not imply any association between any third party and Janus Henderson Investors, nor any endorsement or recommendation by or of any third party. Unless stated otherwise, trademarks are the exclusive property of their respective owners.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.


Before investing in an investment trust referred to in this article, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Tax assumptions and reliefs depend upon an investor’s particular circumstances and may change if those circumstances or the law change.


Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.


The information in this article does not qualify as an investment recommendation.


There is no guarantee that past trends will continue, or forecasts will be realised.


Marketing Communication.


Glossary


Important information

Please read the following important information regarding funds related to this article.

Before investing in an investment trust referred to in this document, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. This is a marketing communication. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions.
    Specific risks
  • Some of the administrative expenses are taken from capital. This allows more income to be paid but it may also restrict capital growth or even reduce the capital over time.
  • Derivatives may be used with the aim of reducing risk or managing the portfolio more efficiently. However, this introduces other risks, in particular, that a derivative counterparty may not meet its contractual obligations.
  • Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
  • If a Company's portfolio is concentrated towards a particular country or geographical region, the investment carries greater risk (as well as the potential for greater reward) than a portfolio that is diversified across more countries.
  • This investment should be held as part of a broader diversified portfolio. Balancing it with investments that have different risk profiles can help reduce the impact of any single investment underperforming.
  • The Company may borrow to invest, which could magnify gains or losses.
  • As the Company may borrow to invest, changes in interest rates could increase or decrease the cost of any borrowings.
  • The Company follows a growth investment style that creates a bias towards certain types of companies, which may result in the Company underperforming or outperforming the wider market.
  • The Company invests in the shares of other companies. These shares may become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
  • Your return on investment is directly related to the market price of the Company's shares, which may be higher (trading at a premium) or lower (trading at a discount) than the value of its underlying net asset value assets. This means your returns may differ from the performance of those assets.
  • While active management techniques are typically positive for performance, this approach may also result in periods of underperformance relative to the benchmark and comparable passive and index-tracking funds, particularly during unexpected market shifts.
  • Shares can gain and lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may rise and fall in line with the underlying equity markets.
  • If the companies in which the portfolio is invested persistently reduce their dividend payments, the Company will find it more difficult to maintain or grow its own dividend payments each year.
  • The Company maintains a portfolio with a bias towards income-generating companies. This may result in the Company significantly underperforming or outperforming the wider market.
  • The portfolio invests in smaller company shares, which may be more difficult to buy and sell, and their share prices may fluctuate more than those of larger companies.