Please ensure Javascript is enabled for purposes of website accessibility Postcard from Asia: Malaysia - stability returns, but is growth next? | Janus Henderson Investment Trusts | UK Investment Trusts

HFEL

Henderson Far East Income Limited

Postcard from Asia: Malaysia – stability returns, but is growth next?

Henderson Far East Income’s fund manager, Sat Duhra, shares insights from his recent visit to Malaysia, where calm politics and rising data-centre projects offer glimpses of future opportunities.

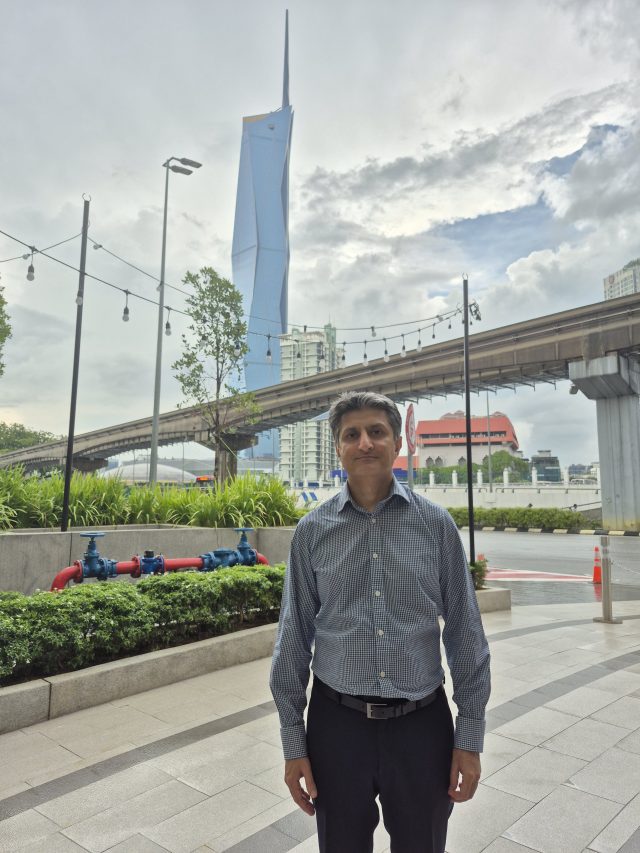
Malaysia is a market I monitor closely. Yet I always come to the same conclusion: it is hard to identify a clear, compelling reason to invest aggressively – though perhaps that, in itself, may become its eventual appeal. After years of political turbulence and headline-grabbing scandals, Malaysia is enjoying a period of relative calm. But calm does not necessarily equate to growth.

Today, Malaysia is calmer and better managed than it was during the 1MDB (Malaysia Development Berhad – a Malaysian state investment fund set up in 2009 to promote economic development, which became the center of a major global financial scandal) years, with a more stable government, clearer economic policies, and far fewer headline-grabbing scandals dominating public life. Inflation is low, and the country recently finalised a 19% tariff agreement with the US, something companies were relieved to see resolved. Malaysia is also benefitting from an improvement in electronics exports, especially in semiconductors where it has long-standing manufacturing expertise.

But despite these positives, this isn’t a fast-growing economy right now. Local consumers remain under pressure, so the government has stepped in with cash support and tourism campaigns to keep spending going. Meanwhile, government debt has risen to about 66% of gross domestic product (GDP), and the budget deficit (what the country overspends each year) is still large.
However, there are areas showing real potential. One area attracting investment is Johor, the state closest to Singapore. New data centres are being built at speed. Much of this is led by Chinese companies, who are also expanding into electric vehicles and renewable energy in Malaysia. These developments help explain why Malaysia’s currency, the ringgit, has strengthened recently. However, these data-centre projects don’t always create many local jobs. They boost investment numbers, but not necessarily everyday economic activity.

Malaysia’s market remains dominated by local institutions, and valuations are not especially cheap given the low-growth environment. There aren’t a lot of buyers and sellers for stocks, so it can be harder to buy or sell shares easily, and many companies seem to be concentrating on keeping their profits steady instead of trying to grow their sales.

During my trip, I met corporates across banking, telecoms, infrastructure and utilities. Several stood out, though none quite enough to shift our investment focus more to the region.

Malaysia remains a market where stability may ultimately become its main selling point, but it is not yet offering the growth, liquidity, or valuation appeal that would justify a meaningful overweight. Foreign investors are still wary, and the domestic story – though improving – lacks a transformative catalyst.

For these reasons, our focus at HFEL will remain on gaining Malaysian economic exposure indirectly through companies in neighbouring markets that benefit from Malaysia’s supply-chain role, such as Singaporean banks and regional tech-infrastructure providers.

That said, I will continue to monitor developments. Especially the Johor-Singapore Special Economic Zone (a new area designed to boost business between Malaysia and Singapore), the semiconductor upcycle (which could mean more jobs and investment in technology), and the trajectory of data-centre investment. And I will certainly be back. Malaysia is a slow-moving story, but as long as political stability holds and capital formation continues, the opportunity set may eventually broaden.

Gross domestic product (GDP)

The value of all finished goods and services produced by a country within a specific time period (usually quarterly or annually). When GDP is increasing, people are spending more and businesses may be expanding. GDP is a broad measure of the size and health of a country’s economy and can be used to compare different economies.

Inflation

The rate at which the prices of goods and services are rising in an economy. The consumer price index (CPI) and retail price index (RPI) are two common measures; the opposite of deflation.

Valuation metrics

Metrics used to gauge a company’s performance, financial health, and expectations for future earnings, e.g. P/E ratio and ROE.

Important information

Henderson Far East Income Limited is a Jersey fund, registered at IFC-1 The, Esplanade, St Helier JE1 4BP, Jersey, and is regulated by the Jersey Financial Services Commission.

These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.


Before investing in an investment trust referred to in this article, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Tax assumptions and reliefs depend upon an investor’s particular circumstances and may change if those circumstances or the law change.


Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.


The information in this article does not qualify as an investment recommendation.


There is no guarantee that past trends will continue, or forecasts will be realised.


Marketing Communication.


Glossary


Important information

Please read the following important information regarding funds related to this article.

Before investing in an investment trust referred to in this document, you should satisfy yourself as to its suitability and the risks involved, you may wish to consult a financial adviser. This is a marketing communication. Please refer to the AIFMD Disclosure document and Annual Report of the AIF before making any final investment decisions. Henderson Far East Income Limited is a Jersey fund, registered at Liberté, 19-23 La Motte Street, St Helier, Jersey JE2 4SY and is regulated by the Jersey Financial Services Commission] Ref: 34V
    Specific risks
  • The portfolio has significant exposure to Emerging Markets, which tend to be less stable than more established markets. These markets can be affected by local political and economic conditions as well as variations in the reliability of trading systems, buying and selling practices, and financial reporting standards.
  • Losses could be incurred if a counterparty became unwilling or unable to meet its obligations, or as a result of failure or delay in operational processes or the failure of a third party provider.
  • Some of the administrative expenses are taken from capital. This allows more income to be paid but it may also restrict capital growth or even reduce the capital over time.
  • If a Company's portfolio is concentrated towards a particular country or geographical region, the investment carries greater risk (as well as the potential for greater reward) than a portfolio that is diversified across more countries.
  • The Company may use options for efficient portfolio management and to increase income. Options can be volatile and may sometimes result in loss of capital.
  • This investment should be held as part of a broader diversified portfolio. Balancing it with investments that have different risk profiles can help reduce the impact of any single investment underperforming.
  • The Company may borrow to invest, which could magnify gains or losses.
  • As the Company may borrow to invest, changes in interest rates could increase or decrease the cost of any borrowings.
  • The Company invests in the shares of other companies. These shares may become hard to value or to sell at a desired time and price, especially in extreme market conditions when asset prices may be falling, increasing the risk of investment losses.
  • Your return on investment is directly related to the market price of the Company's shares, which may be higher (trading at a premium) or lower (trading at a discount) than the value of its underlying net asset value assets. This means your returns may differ from the performance of those assets.
  • While active management techniques are typically positive for performance, this approach may also result in periods of underperformance relative to the benchmark and comparable passive and index-tracking funds, particularly during unexpected market shifts.
  • Shares can gain and lose value rapidly, and typically involve higher risks than bonds or money market instruments. The value of your investment may rise and fall in line with the underlying equity markets.
  • If the companies in which the portfolio is invested persistently reduce their dividend payments, the Company will find it more difficult to maintain or grow its own dividend payments each year.
  • The portfolio invests in currencies other than sterling, meaning fluctuations in exchange rates could affect returns.
  • The Company maintains a portfolio with a bias towards income-generating companies. This may result in the Company significantly underperforming or outperforming the wider market.