Key takeaways:
- Recent biotech weakness appears driven more by broader deleveraging and technical factors than a deterioration in fundamentals, in our view, with the sharpest declines concentrated in AI-linked genomics and life science tools companies where expectations and valuations had become stretched.
- In contrast to the post-COVID downturn, when elevated valuations were widespread, pockets of froth in today’s biotech landscape are concentrated in a relatively narrow group. Meanwhile, we believe the sector is fundamentally healthier, and many companies with validated platforms, commercial products, and late-stage assets continue to trade at what we view as attractive valuations.
- Beyond biotech, we believe the Democratic sweep could have more nuanced, and potentially more benign, implications for healthcare than the initial market reaction suggested. Greater emphasis on access and coverage could support healthcare utilization, which appears to be a top legislative priority. While we recognize that drug pricing will always be a political focus, meaningful changes in the current framework appear less likely.
A sharp selloff in technology and artificial intelligence (AI)-related stocks in the aftermath of the U.S. midterm elections spilled over to healthcare and other sectors on November 5, with biotechnology stocks particularly hard hit. Notably, the decline was most acute among genomics, diagnostics, and life science tools companies that had benefited from growing AI enthusiasm, which, in our view, had pushed expectations and valuations for some of these companies to increasingly stretched levels.
We believe recent price action reflects broader deleveraging dynamics and other technical factors rather than a deterioration in fundamentals across the biotech landscape.
Pullback in AI-linked biotech stocks could refocus attention on fundamentals
In recent months, surging interest in AI-enabled drug development and personalized medicine had created a widening disconnect within the sector (Exhibit 1). While AI-linked life science tools stocks rallied sharply through September, many more traditional biotech companies, including those advancing promising new treatments, continued to trade at attractive valuations. We believe the recent volatility since early October could help refocus investor attention on fundamentals and the attractive entry points in these high-quality biotech companies.
Exhibit 1: Genomics stocks retreat after AI-fueled rally
Price % change, 30 June 2026 through 5 November 2026
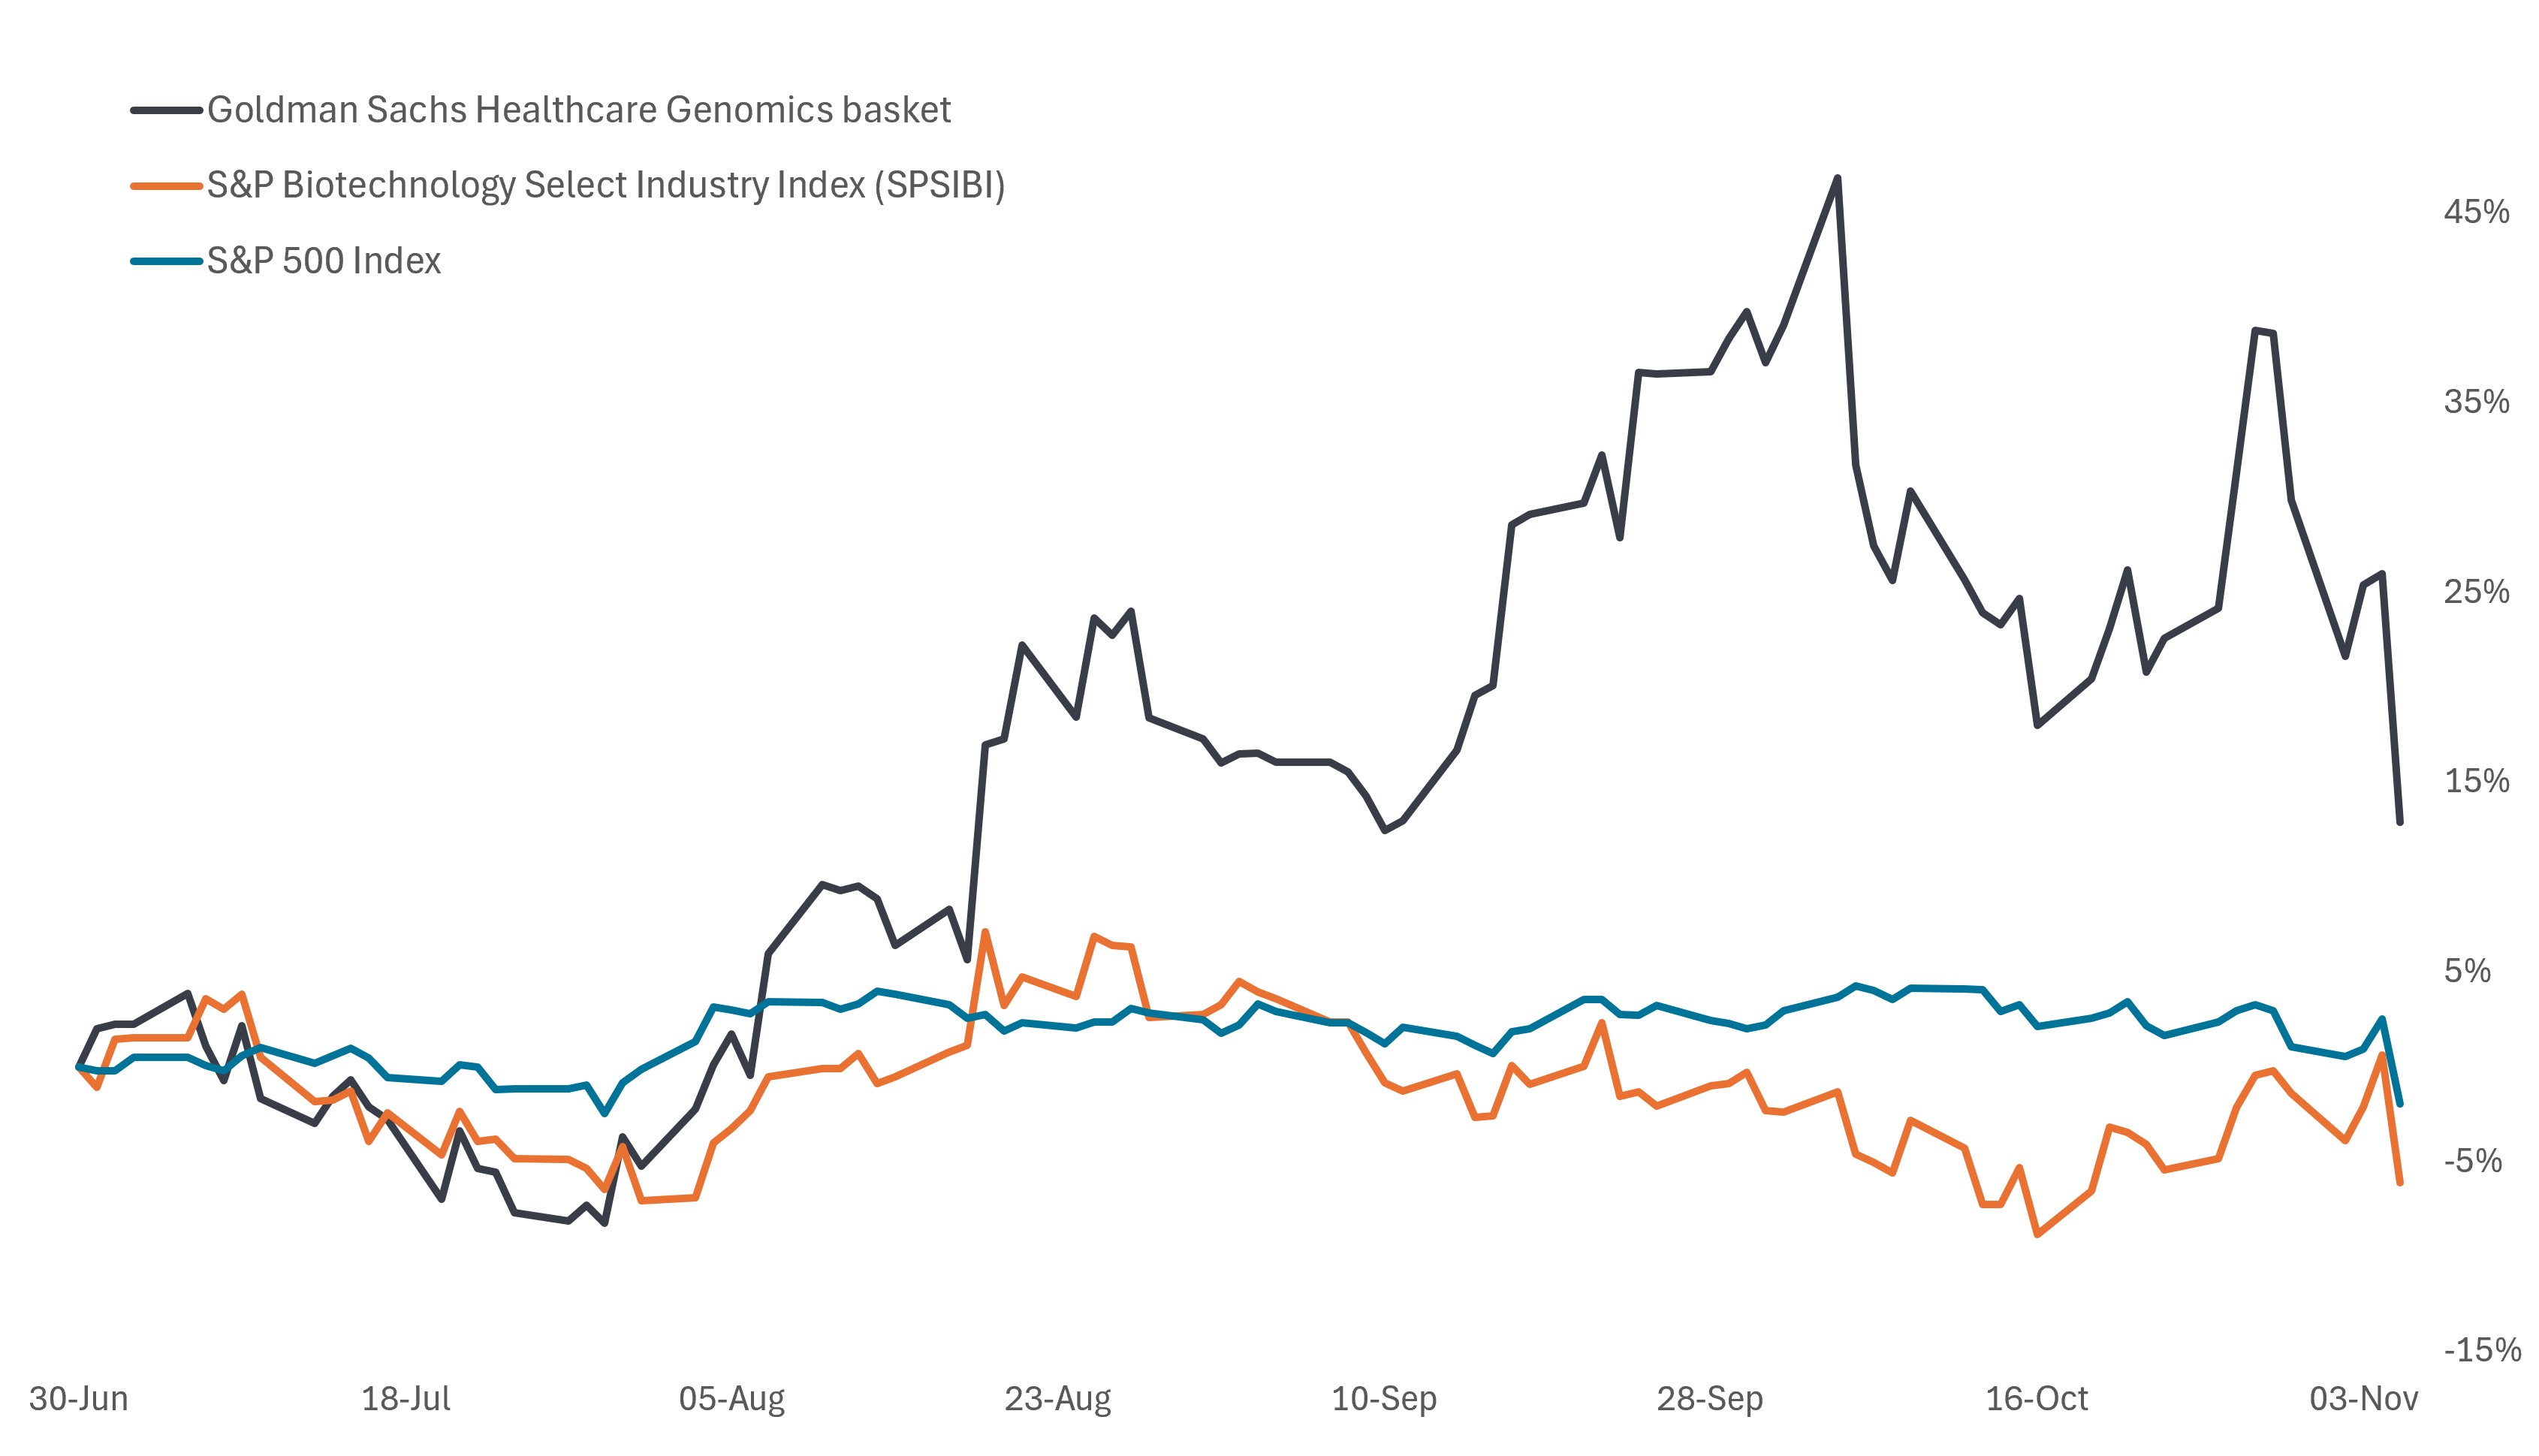
Source: Bloomberg, data from 30 June 2026 to 5 November 2026. Past performance does not predict future results. An index is unmanaged and not available for direct investment.
Importantly, while the biotech sector’s strong run over the past year may draw comparisons to the speculative froth that preceded the Covid-era downturn in 2021, today’s biotech landscape bears several key differences.
For one, having endured the post-pandemic drawdown and tighter financing conditions that accompanied the Fed’s aggressive 2022-2023 rate-hike cycle, we believe biotech has emerged as a healthier and more disciplined sector. Many companies have stronger balance sheets, more experienced management teams, and a greater number of commercial-stage assets than was the case several years ago. In addition, whereas the 2020-2021 boom was broad-based, the valuation excess in today’s market has been largely concentrated in a relatively narrow group of companies. Meanwhile, we continue to find attractive valuations among many companies with validated platforms, commercial products, and late-stage assets.
A more nuanced policy outlook for healthcare
Beyond biotech, the extent of the Democratic sweep and what it could mean for the policy outlook for healthcare warrants attention. However, we believe the implications are more nuanced and potentially more benign for parts of the sector than the initial market reaction suggested. It also remains too early to draw conclusions about how a Democratic-led Congress will engage with the Trump Administration or what ultimately could translate into healthcare policy.
What does appear clearer to us is that Democrats may be emboldened to shift the policy agenda toward expanding access and protecting healthcare coverage, with Affordable Care Act (ACA) affordability near the top of the list.
Enhanced premium subsidies expired at the end of 2025, raising concerns about affordability and coverage losses. Democrats are widely expected to prioritize restoring those subsidies while also turning their attention to protecting existing Medicaid coverage rather than pursuing another major expansion. For Medicaid specifically, much of the debate has centered on concerns around new federal work requirements that could lead to coverage losses, particularly among lower-income populations.
The upshot is that greater coverage stability could be incrementally supportive for overall healthcare utilization and patient volumes. For medtech in particular, this would be a welcome potential tailwind following a challenging operating environment marked by strained hospital budgets and coverage losses, which have helped push valuations to historically depressed levels.
As for biopharma, while drug pricing will likely remain a hot-button issue, we would not necessarily interpret the Democratic sweep as signaling a push for new legislation. Instead, we believe Democrats are more likely to defend existing Medicare drug-price negotiation and other affordability provisions enacted under the Inflation Reduction Act. That could provide some reassurance for pharmaceutical and biotech companies, where policy uncertainty around drug pricing has periodically weighed on valuations.
Ultimately, while we will continue to monitor the shifting policy landscape in the months ahead, we remain encouraged by the strong fundamental backdrop across the sector. In our view, Healthcare continues to offer investors a unique combination of long-term secular tailwinds, such as medical innovation and aging demographics, alongside defensive characteristics and a diverse set of return drivers beyond the AI theme. We also believe the recent market volatility could refocus attention on valuations, where we continue to see opportunities for investors willing to look past near-term market gyrations.
IMPORTANT INFORMATION
Artificial intelligence (“AI”) focused companies, including those that develop or utilize AI technologies, may face rapid product obsolescence, intense competition, and increased regulatory scrutiny. These companies often rely heavily on intellectual property, invest significantly in research and development, and depend on maintaining and growing consumer demand. Their securities may be more volatile than those of companies offering more established technologies and may be affected by risks tied to the use of AI in business operations, including legal liability or reputational harm.
Equity securities are subject to risks including market risk. Returns will fluctuate in response to issuer, political and economic developments.
Health care industries are subject to government regulation and reimbursement rates, as well as government approval of products and services, which could have a significant effect on price and availability, and can be significantly affected by rapid obsolescence and patent expirations.
Goldman Sachs Healthcare Genomics basket: Comprises companies within the Healthcare sector that make the tools to examine and manipulate genes. Stocks are selected fundamentally by the Goldman Sachs Healthcare sector specialist. The basket is modified liquidity weighted and rebalanced at the discretion of the specialist.
S&P 500® Index reflects U.S. large-cap equity performance and represents broad U.S. equity market performance.
The S&P® Biotechnology Select Industry Index comprises stocks in the S&P Total Market Index that are classified in the GICS Biotechnology sub-industry.
These are the views of the author at the time of publication and may differ from the views of other individuals/teams at Janus Henderson Investors. References made to individual securities do not constitute a recommendation to buy, sell or hold any security, investment strategy or market sector, and should not be assumed to be profitable. Janus Henderson Investors, its affiliated advisor, or its employees, may have a position in the securities mentioned.
Past performance does not predict future returns. The value of an investment and the income from it can fall as well as rise and you may not get back the amount originally invested.
The information in this article does not qualify as an investment recommendation.
There is no guarantee that past trends will continue, or forecasts will be realised.
Marketing Communication.