Key takeaways:
- The IRS generally treats proceeds from successful sports wagers as taxable income, while losses are generally claimed as itemized deductions, subject to applicable limitations.
- As greater accessibility to sports betting increases the frequency of wagers and the amounts won or lost, it’s important to ensure those amounts fit within your budget or financial plan.
- From a taxation perspective, it is equally important to maintain good records of gambling proceeds to ensure the thrill that comes with wagering on sports isn’t followed by the agony of a tax issue.
Now more than ever, sports and gambling are inextricably linked. You cannot turn on a game, go to a sports website, or update your fantasy lineup without being strongly reminded that you can place a wager on an upcoming match, the next inning, or some other increment of a competition. Denver Broncos in Week 3? Check. An Erling Haaland second-half goal? I’ve got you. A cricket match halfway around the world at 2 a.m.? Just click here.
The dopamine hits just keep on coming as sports betting becomes easier, the bets become shorter-term in nature, and the advertising for these betting platforms becomes more enticing.
How enticing? A recent survey from Acorns found that the average surveyed bettor spends $274 a month, or $3,284 a year, on gambling.1 Another survey from Betterment found that 26% of Gen Z investors treat sports betting as a deliberate part of their long-term financial strategy, and 52% have redirected money originally intended for investing toward it in the past year.2
To paraphrase Rick James from the famous Chapelle Show episode, “Sports betting is a hell of a drug!”
While I could jump on my soapbox and yell down to the masses about how gambling is not a long-term financial strategy or why betting shouldn’t factor into one’s budget, I’m not going to do that today.
Instead, I’m going to take on dopamine with the U.S. tax code! I may not be able to stop people from betting on sports, but I can help make sure they understand how it may affect their income taxes. Plus, let’s be honest, there’s nothing like taxes to tamp down dopamine levels.
Winnings are treated as taxable income
The first thing to understand is that winnings from sports betting are taxed at your ordinary income rates on your federal income taxes. The IRS generally treats gambling winnings, including proceeds from successful sports wagers, as taxable income.
A sportsbook may issue Form W-2G when winnings meet the applicable reporting requirements. The form includes taxable winnings and any withholding you may have elected. The sportsbook provides a copy of the form to both the bettor and the IRS. Form W-2G reporting requirements depend on the type and amount of gambling winnings.
Because the applicable thresholds and rules may change, bettors should consult current IRS guidance and the tax documents supplied by each sportsbook. Along with that, it’s important to know that these forms should be available through online sports-betting sites by January or February of the year following the current tax year.
Note that the absence of a Form W-2G does not necessarily mean the winnings are exempt from federal income tax. This certainly makes me wonder about all the NCAA brackets and fantasy leagues that go on in offices across the world. Something tells my colleague isn’t going to send me a Form W-2G if I win the Janus Henderson English Premier League Fantasy title this year (fingers crossed)!
Gambling losses can be deducted
Not every bet works out, and not everyone is going to come out in the black. Gambling losses are generally claimed as itemized deductions, subject to applicable limitations. A taxpayer who claims the standard deduction generally does not receive a separate deduction for those losses.
In the past, one would be able to deduct 100% of losses up to the amount of their winnings. However, due to changes associated with the One Big Beautiful Bill Act (OBBBA), deductions are now limited to 90% of losses up to the amount of winnings.
For example, if you won $20,000 over the course of the year but also lost $20,000, you would still have to add $2,000 in winnings to your taxable income for the year. In this simplified example, the bettor would still report $2,000 of net taxable gambling income under the stated limitation, despite having no economic profit.
State of play
Federal tax rules are only part of the picture. State treatment of gambling winnings and losses varies as well. At this point, 39 states and the District of Columbia have legalized sports gambling.
For those of us in Colorado, not only do we need to know the line on the Colorado State University game but also how the State of Colorado taxes gambling proceeds and losses. The same goes for people in other states around the country.
The map below shows states that have legalized retail and/or online sports betting.
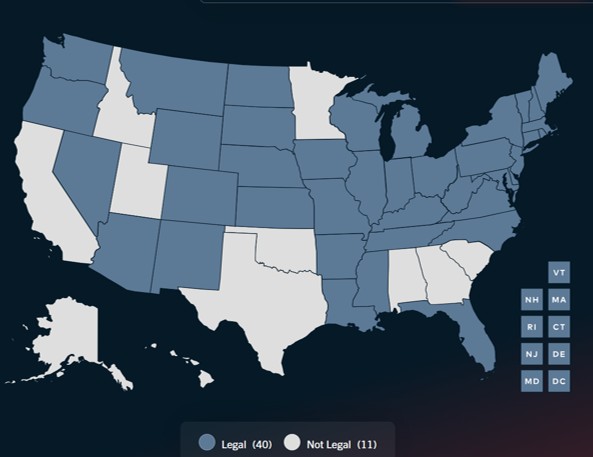
Source: American Gaming Association, “State of Play.” Legal Landscape as of Feb. 27, 2025.
When it comes to state-level taxes, most sites will only go so far as to say requirements and taxation depend on individual states and that users should work with their personal tax advisor.
Keep good records
Betting on sports is something that has been done for hundreds if not thousands of years. The issue that gamblers face today is that it is easier and faster than ever. That accessibility can increase both the frequency of wagers and the amounts won or lost. It is, of course, important to ensure that those amounts fit within your budget and financial plan. But it is also important to be able to track and account for those wins and losses.
Bettors should consider retaining the following:
- Annual statements downloaded from each sportsbook
- Forms W-2G and related tax documents
- Dates and types of wagers
- Amounts wagered, won, and lost
- Deposit and withdrawal records
- Documentation supporting claimed losses
- State or jurisdiction associated with each wager
- Copies of the tax guidance relied upon
By keeping good records of your gambling proceeds, you can ensure the thrill that comes with wagering on sports isn’t followed by the agony of a tax issue.
1 “This CEO isn’t sure about financial nihilism, but he’s horrified by sports gambling online. So this football season, he’ll pay you not to do it.” Fortune, September 9, 2026.
2 Betterment, 2026 Retail Investor Survey.